


Lazard (LAZ) has moved back into focus after reporting above-consensus net inflows in October, alongside closing the Campbell Lutyens deal and extending its private capital reach through Lazard CL and Elaia Partners.
The recent inflow surprise and Campbell Lutyens acquisition have landed at an interesting moment for Lazard. The share price trades at about $41.90 after a 1-month share price return of 13.09%. However, the year-to-date share price return is down 15.76% and the 1-year total shareholder return is also lower by 15.63%, while the 3-year total shareholder return of 71.21% points to much stronger longer run performance.
Scan beyond Lazard's inflow story and hunt for other wealth managers and financial advisory firms showing strong fundamentals, using our curated list of solid balance sheet and fundamentals (24 results) as a starting universe.
Lazard now trades only slightly below the average analyst target, yet its own fair value estimate implies a much wider gap. After the sharp recent rebound, is caution still warranted, or has the repricing gone too far?
Most Popular Narrative: 2% Undervalued
The analyst consensus Narrative on Simply Wall St sets a fair value for Lazard at about $42.88, only slightly above the latest close at $41.90. This leaves a modest implied discount and a tight margin for error around that estimate, based on a 9.23% discount rate.
The combination of Lazard's existing private capital advisory business with Campbell Lutyens into Lazard CL, with anticipated revenue of about US$500 million in 2027 and a higher share of advisory revenue tied to private capital, points to a larger fee pool that could lift advisory revenue and earnings.
See why 4 investors see Lazard as 2% undervalued.
Result: Fair Value of $42.88 (UNDERVALUED)
Still, the Lazard story can crack if private capital fees do not ramp as analysts expect or if the compensation ratio stays elevated and compresses margins.
Find out about the key risks to this Lazard narrative.
Another View: How Lazard Screens On Earnings Multiples
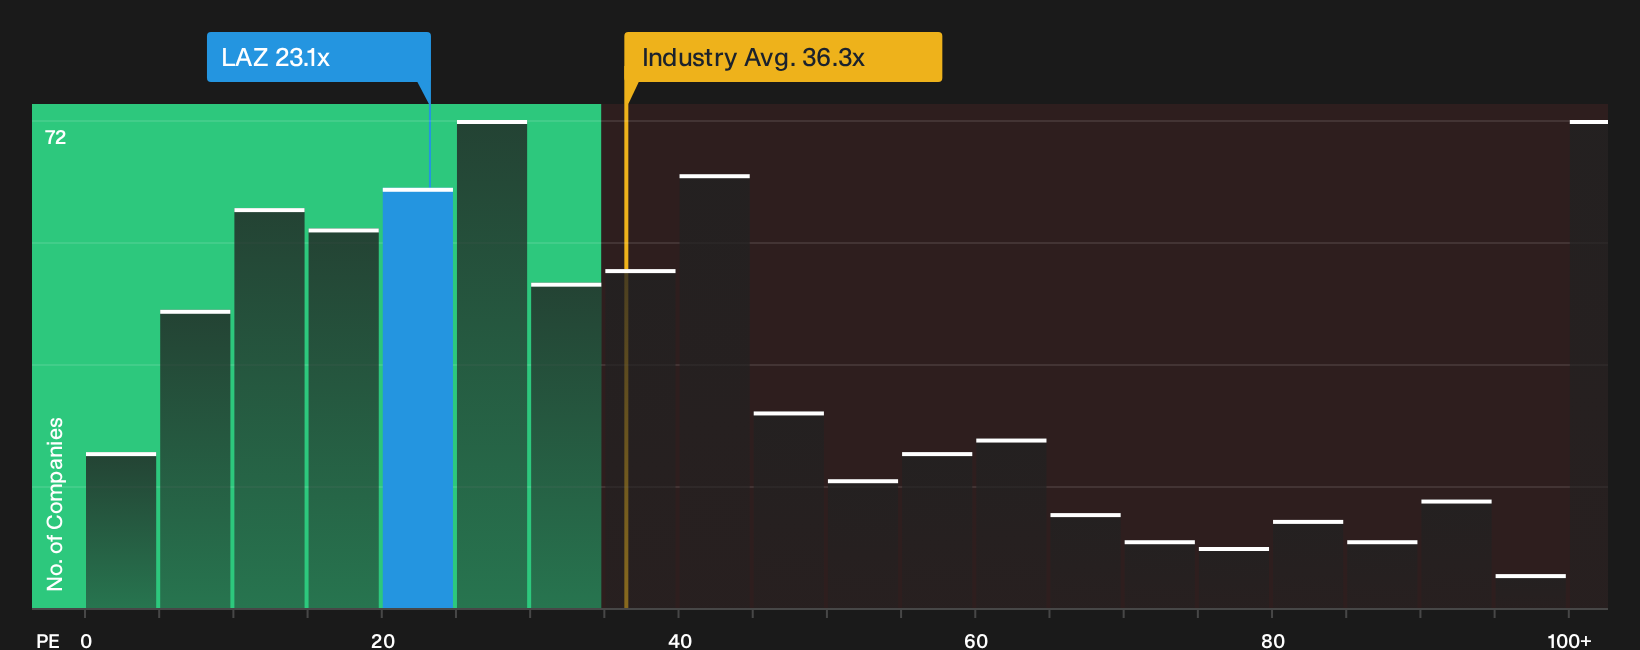
DCF work points to Lazard trading at a steep discount to an estimated future cash flow value of $76.79, which flags the stock as undervalued. The P/E picture is less generous. At 23.1x, the shares look cheap against the US Capital Markets average of 36.3x but expensive versus peers at 18.8x and above an estimated fair ratio of 21.6x. So is the opportunity as big as the DCF suggests, or closer to fully reflected in the earnings multiple already?
To test how much weight to put on that earnings multiple gap, it helps to see what the numbers say in detail, then compare that to where similar businesses trade using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Lazard's valuation and fundamentals can feel unclear, so step into the data yourself and move quickly to frame your own stance using the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Lazard?
If Lazard has sharpened your focus on quality and valuation, you can broaden your watchlist now using targeted screeners that surface clear, data backed ideas in minutes.
- Target dependable compounding potential by reviewing stocks that pass a tough quality and valuation filter through the 32 high quality undervalued stocks.
- Prioritise resilience by scanning companies that score well on balance sheet strength and core fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for under-the-radar opportunities by checking a curated pool of strong fundamental stories in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com