


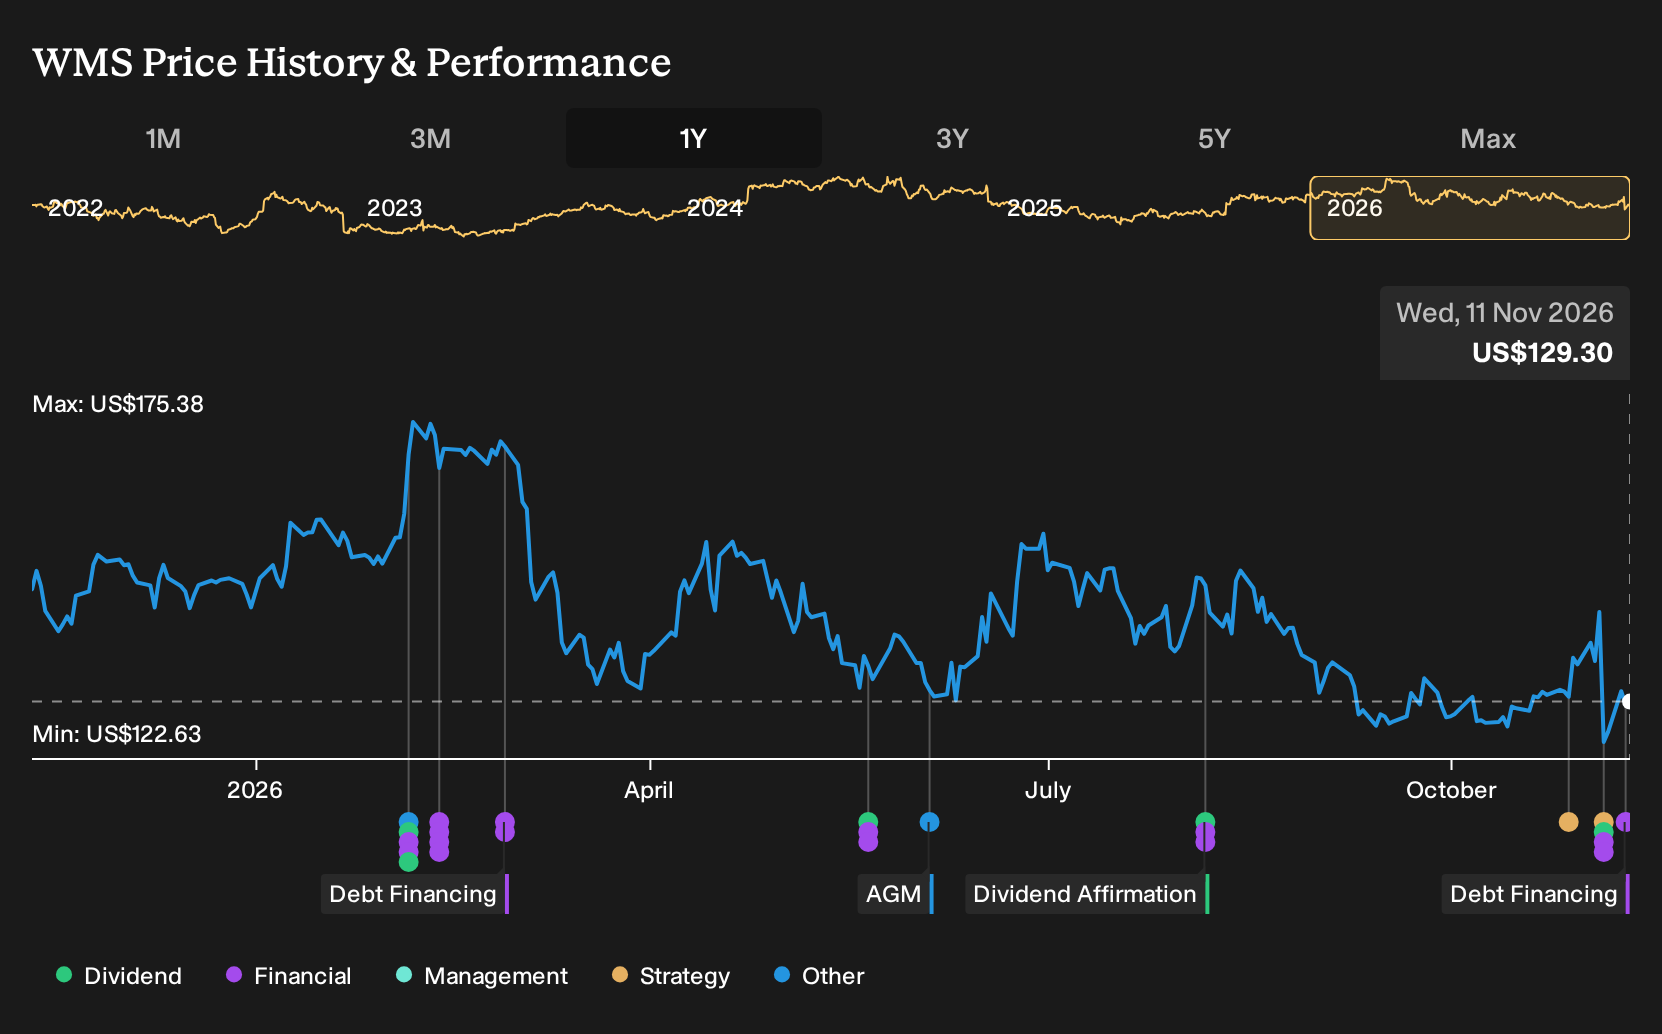
- Advanced Drainage Systems reported quarterly and six month results to September 30, 2026, with higher sales alongside lower quarterly net income, and paired this with an 11% increase in its quarterly dividend to US$0.20 per share approved for payment on December 15, 2026.
- The combination of rising revenue, softer profitability in the recent quarter and a higher dividend reflects management’s view of the company’s cash generation while the business manages cost and demand pressures.
- This article reviews how Advanced Drainage Systems' investment narrative is affected by higher sales alongside a raised quarterly dividend.
Scan other companies that are pairing active acquisition plans and expanded credit lines with shareholder payouts by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in the same capital allocation theme as Advanced Drainage Systems.
Advanced Drainage Systems Investment Narrative Recap
For an investor to stay with Advanced Drainage Systems, the core belief is that demand for stormwater and wastewater solutions remains resilient enough to support the shift toward higher margin products, even while near term construction trends stay choppy. The analyst consensus Narrative on Simply Wall St leans on that mix shift and on cost advantages from recycling and the trucking fleet.
The near term swing factor is whether resin and freight headwinds erode margins faster than higher value products and pricing can offset. Recent quarterly results, with higher sales but softer profitability, reinforce that risk, while the raised dividend signals management still sees cash generation as supportive, without changing those underlying operational questions.
The most relevant development for that story is the Fifth Amendment to the Credit Agreement, which lifts revolving commitments by US$300 million to US$1.05b and broadens access to supply chain and receivables financing. Advanced Drainage Systems now has a larger liquidity pool to fund organic projects and potential deals while it manages end market softness.
Greater borrowing capacity can help the business pursue the catalysts highlighted in the analyst consensus Narrative on Simply Wall St, including expansion of higher margin Allied Products and wastewater offerings and continued investment in recycling infrastructure. The trade off is that a higher reliance on debt funded flexibility can amplify risk if construction demand weakens or if cost inflation continues to pressure margins.
Advanced Drainage Systems' narrative projects US$4.1b revenue and US$744.9 million earnings by 2029. This is based on analysts assuming 8.0% yearly revenue growth and an earnings increase of about US$309 million from US$435.8 million today.
Uncover why Advanced Drainage Systems' fair value indicates a 38% potential upside to its current price, which could narrow quickly as expectations reset.
Exploring Other Perspectives
Fair value estimates from 2 private investors in the Simply Wall St Community cluster tightly between US$166.38 and US$178.36 per share, which still excludes the latest dividend increase, acquisition appetite and expanded US$1.05b credit facility. That combination of capital returns, deal intent and higher leverage can all influence Advanced Drainage Systems’ risk and reward profile. Readers should consider several contrasting viewpoints before reaching a conclusion.
Explore another Advanced Drainage Systems fair value estimate, including one that suggests it could be worth just $166.38!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Advanced Drainage Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advanced Drainage Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Drainage Systems' overall financial health at a glance.
Looking for more investment ideas beyond Advanced Drainage Systems?
Once you have formed a view on Advanced Drainage Systems, it can help to compare that thesis with other opportunities that share similar qualities or offer a very different risk and return profile. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If you want stocks that combine quality fundamentals with what the Screener flags as potentially attractive pricing, start with a curated set of 32 high quality undervalued stocks that pass strict balance sheet and cash flow filters.
- For readers who care most about stability, look through 30 resilient stocks with low risk scores that our models rate as having more resilient financial profiles and lower overall risk scores.
- Those hunting for less crowded opportunities can review 19 high quality undiscovered gems where underlying fundamentals screen well yet investor attention remains relatively limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com