


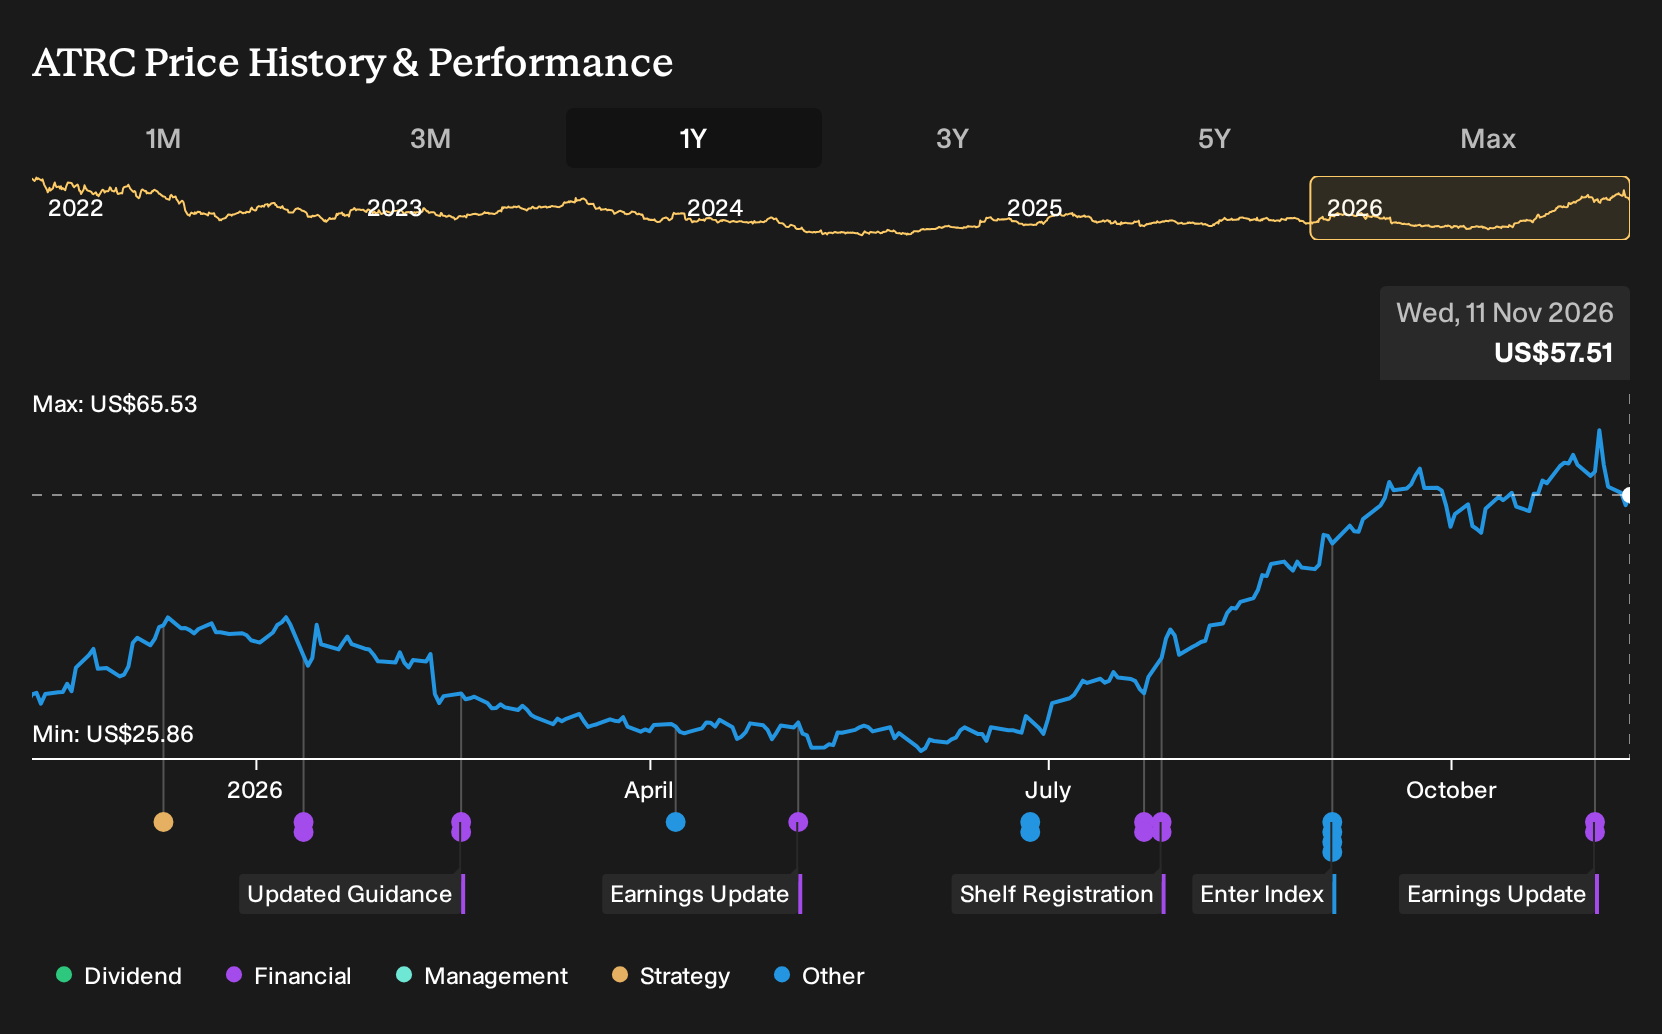
- AtriCure reported third quarter 2026 revenue of US$154.45 million and net income of US$4.06 million, with earnings of US$0.08 per diluted share. The company also issued full year 2026 guidance for revenue of US$606 million to US$610 million and net income per share of US$0.21 to US$0.27.
- The shift from a net loss over the prior year periods to positive net income for both the quarter and nine months indicates that AtriCure’s cost structure and product mix are now supporting profitability alongside higher sales.
- The focus now turns to how AtriCure’s move to consistent profitability and tighter guidance might influence the existing investment narrative.
AtriCure Investment Narrative Recap
To own AtriCure, you need to believe the cardiac surgery and cryo pain businesses can carry the story while weaker areas, like minimally invasive ablation and slower international markets, do not drag overall performance. The latest quarter shows that the current mix can support profitability, so the near term focus stays on execution rather than a reset of the thesis.
The key short term swing factor is whether hospitals keep adopting AtriCure’s platforms at a pace that sustains high single to low double digit top line progress. The biggest risk remains pressure on the minimally invasive ablation franchise and constrained overseas demand, which could cap margins if they offset gains in U.S. procedure volumes.
The most relevant update here is AtriCure’s full year 2026 outlook, which brackets revenue at US$606 million to US$610 million and earnings per share at US$0.21 to US$0.27. That range effectively ties current profitability to very specific volume and mix assumptions, so it becomes the operational yardstick to watch after a profitable nine month stretch.
If those targets hold, it suggests the company can keep funding R&D and commercial expansion while staying in the black. This aligns with the analyst consensus Narrative on Simply Wall St, which assumes ongoing profitability and cash generation. Any stumble relative to that guidance, whether from weaker international orders or sustained PFA related pressure, would directly affect the main catalysts around margin progress and confidence in longer term ambitions.
AtriCure's narrative projects US$831.7 million revenue and US$36.5 million earnings by 2029. This assumes 12.1% yearly revenue growth and an earnings increase of about US$21.6 million from US$14.9 million today.
Uncover why AtriCure's fair value aligns with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame BoxX-NoAF as the real swing factor for AtriCure. Before this earnings release, the bullish camp was pencilling in about US$843.2 million of revenue and US$65.3 million of earnings by 2029, so they already saw far more upside. Your view might shift as those trial results and the new guidance interact.
Explore another AtriCure fair value estimate, including one that suggests it could be worth as much as $57.56.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AtriCure research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AtriCure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AtriCure's overall financial health at a glance.
Looking for more investment ideas beyond AtriCure?
If AtriCure has sharpened your focus on quality, you can use that same lens to scan the wider market. The Simply Wall St Screener can help you quickly narrow the universe of stocks to a shortlist that fits your risk, income, and balance sheet preferences.
- For investors who want relatively steadier profiles, you could start with companies that pass a strict risk filter by reviewing 30 resilient stocks with low risk scores.
- If long term compounding and value appeal to you, you might focus on businesses combining solid fundamentals with attractive pricing through the 19 high quality undiscovered gems.
- For readers who care about staying power as much as returns, consider prioritising financially robust companies by scanning the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com