


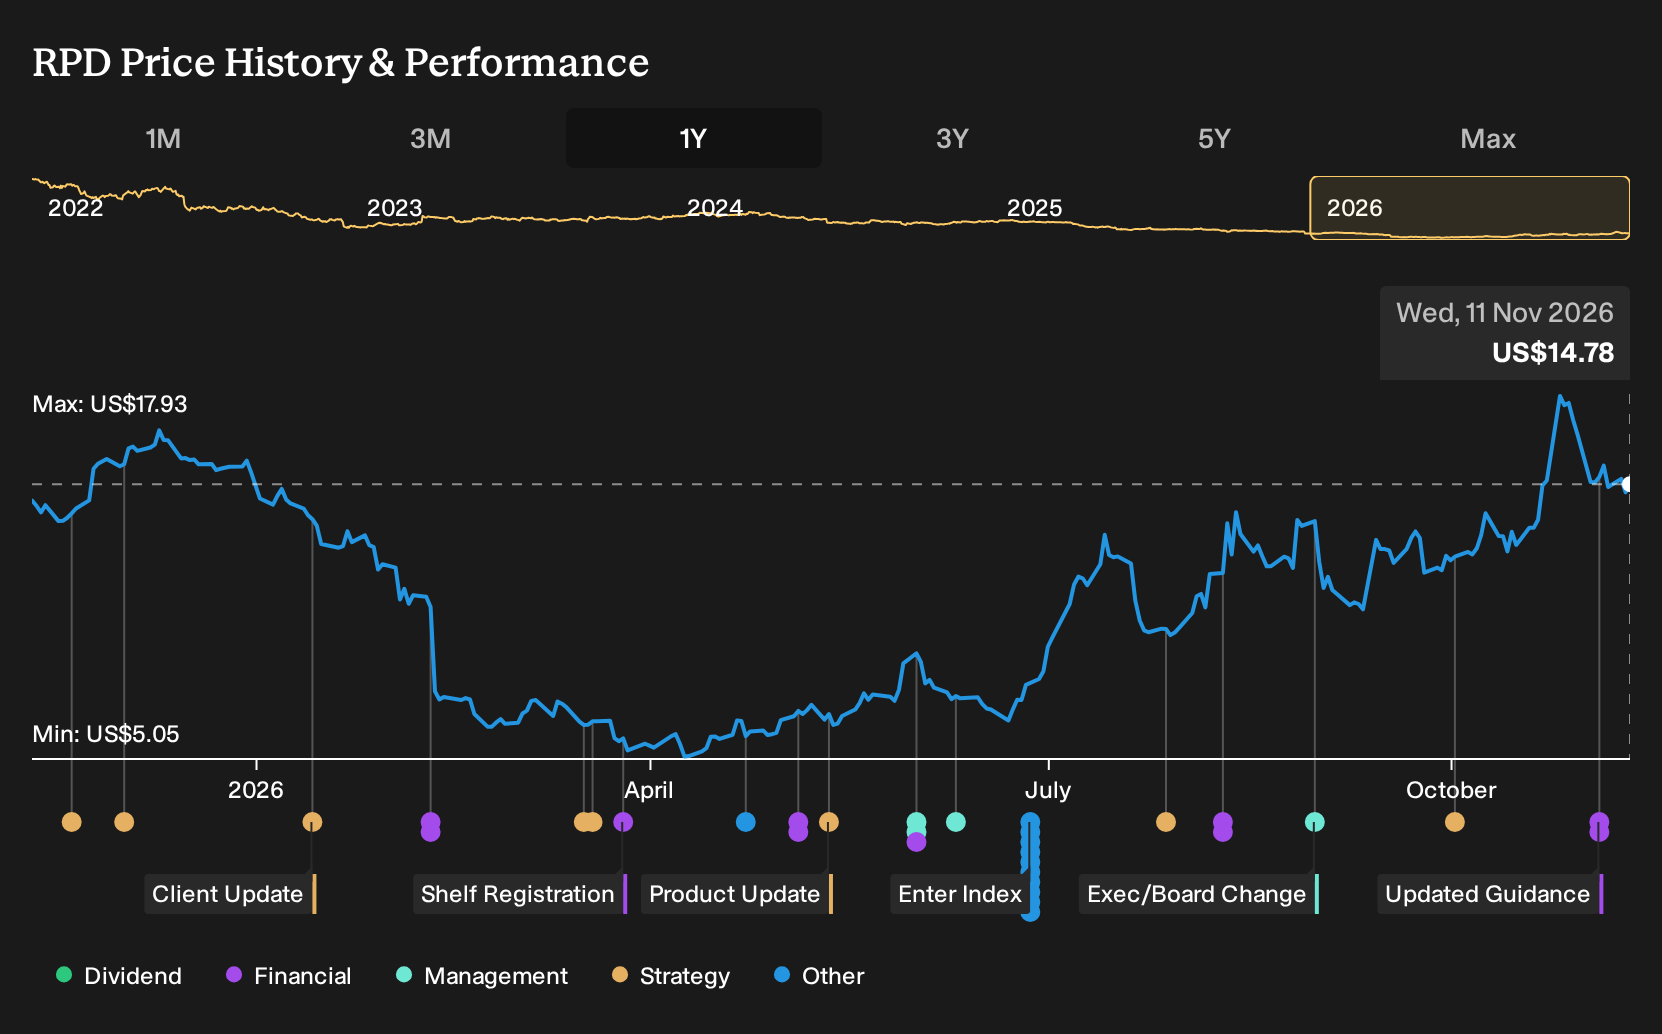
- Rapid7 reported third quarter 2026 revenue of US$212.4 million and net income of US$3.51 million, both below the prior year, and issued fourth quarter and full year 2026 guidance that points to low US$200 million quarterly revenue and about US$841 million for the year.
- The guidance explicitly links expected 2026 revenue contraction of roughly 2% to year to date ARR pressure. This highlights that Rapid7’s core subscription engine is under strain while the firm is still targeting higher profitability and cash generation.
- This article now examines how Rapid7's softer 2026 revenue outlook, tied to ARR pressure, could reshape the existing investment narrative.
Compare other security software stocks with more resilient revenue trends to Rapid7 by starting with our hand picked list of solid balance sheet and fundamentals (24 results).
Rapid7 Investment Narrative Recap
To own Rapid7 today, you need to believe the AI focused Detection & Response and Exposure Management platform can offset pressure on annual recurring revenue, while management holds the line on profitability and cash generation. The analyst consensus Narrative on Simply Wall St already assumes earnings expansion even as revenue guidance points to a softer top line.
The latest outlook for a roughly 2% revenue contraction in 2026 keeps the near term story centered on ARR stability and execution on cost discipline. The biggest short term catalyst remains evidence of steadier core ARR and progress toward higher non GAAP operating margins. The key risk is that contracting ARR persists, while operating leverage stalls.
The most relevant update here is Rapid7's new 2026 guidance, which calls for US$208 million to US$210 million in fourth quarter revenue and US$841 million to US$843 million for the full year. That explicitly ties a roughly 2% annual decline to year to date ARR trends, so it directly speaks to the core subscription engine.
For a reader tracking catalysts, this guidance sharpens the focus on whether the AI first SOC, the Kenzo Security acquisition and MDR automation efforts can stabilize ARR without sacrificing the push toward around 20% non GAAP operating margins by late 2026. It also underlines the risk that debt remains less comfortably covered by operating cash flow if ARR pressure endures.
Rapid7's current narrative points to forecast revenue of US$804.9 million and consensus earnings of US$37.3 million by 2029. This implies analysts are factoring in a yearly revenue decline of about 1.8% and an earnings increase of roughly US$23.5 million from earnings today of US$13.8 million.
Uncover why Rapid7's fair value indicates a 5% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Rapid7, the alternate story puts far more weight on the risk that gross margin stays under strain. The most cautious analysts were already baking in revenue of about US$796.9 million and earnings of roughly US$42.5 million by 2029 before this guidance. That is a harsher narrative. Use it as a prompt to compare several viewpoints and stress test your own assumptions.
Explore 3 other Rapid7 fair value estimates, including one that suggests as much as 41% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rapid7 research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Rapid7. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rapid7's overall financial health at a glance.
Looking for more Rapid7 sized investment ideas?
If the Rapid7 story leaves you wanting a broader watchlist, it helps to widen the lens and see how other businesses stack up on quality, balance sheet strength and income potential.
- For potential mispriced opportunities with stronger fundamentals, start with a curated group of quality companies using the Simply Wall St screener built around 32 high quality undervalued stocks.
- If capital preservation matters most to you, filter for businesses with sturdier finances and steadier fundamentals through the screener focused on a list of solid balance sheet and fundamentals (24 results).
- For investors who like to see cash returned regularly, sort for income ideas using the screener that highlights 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com