


Kinder Morgan (KMI) is back in focus after Executive Chairman Richard Kinder bought 500,000 shares in early November for about US$15 million, following a recent pullback in the stock.
At a share price of US$31.59, Kinder Morgan has delivered a 14.0% year to date share price return, while total shareholder return over the past year is 21.36%. The 3 year and 5 year total shareholder returns of 114.09% and 148.94% point to momentum that long term holders will care about more than the recent 4.5% 1 month share price dip or the slight 90 day pullback of 1.53%.
Scan insider-backed infrastructure ideas beyond Kinder Morgan with a curated set of 42 power grid technology and infrastructure stocks. These could benefit as energy demand and pipeline capacity needs continue to reshape the grid.
Fans point to Kinder Morgan’s record gas backlog, long term contracts and insider buying as proof the recent pullback is a chance to add. Skeptics see capital spending needs and earnings timing as a warning. Which case does the valuation support?
Most Popular Narrative: 14.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Kinder Morgan’s fair value sits at $37, which is above the last close at $31.59. This frames insider buying and the recent pullback against a wider backlog and cash flow story.
The current roughly $9.6b Board approved growth backlog, which is mainly tied to take or pay natural gas projects with an average in service date in the first half of 2028, is expected by management to translate into about $1.7b of incremental EBITDA over time. This could lift Kinder Morgan's future cash generation as these assets move from construction to operation.
See why 76 investors see Kinder Morgan as 15% undervalued.
Result: Fair Value of $37 (UNDERVALUED)
Still, the Kinder Morgan story can break if big pipeline projects stall in permitting or if new acquisitions fail to earn the returns that management is modeling.
Find out about the key risks to this Kinder Morgan narrative.
Another View: Kinder Morgan On Earnings Multiples
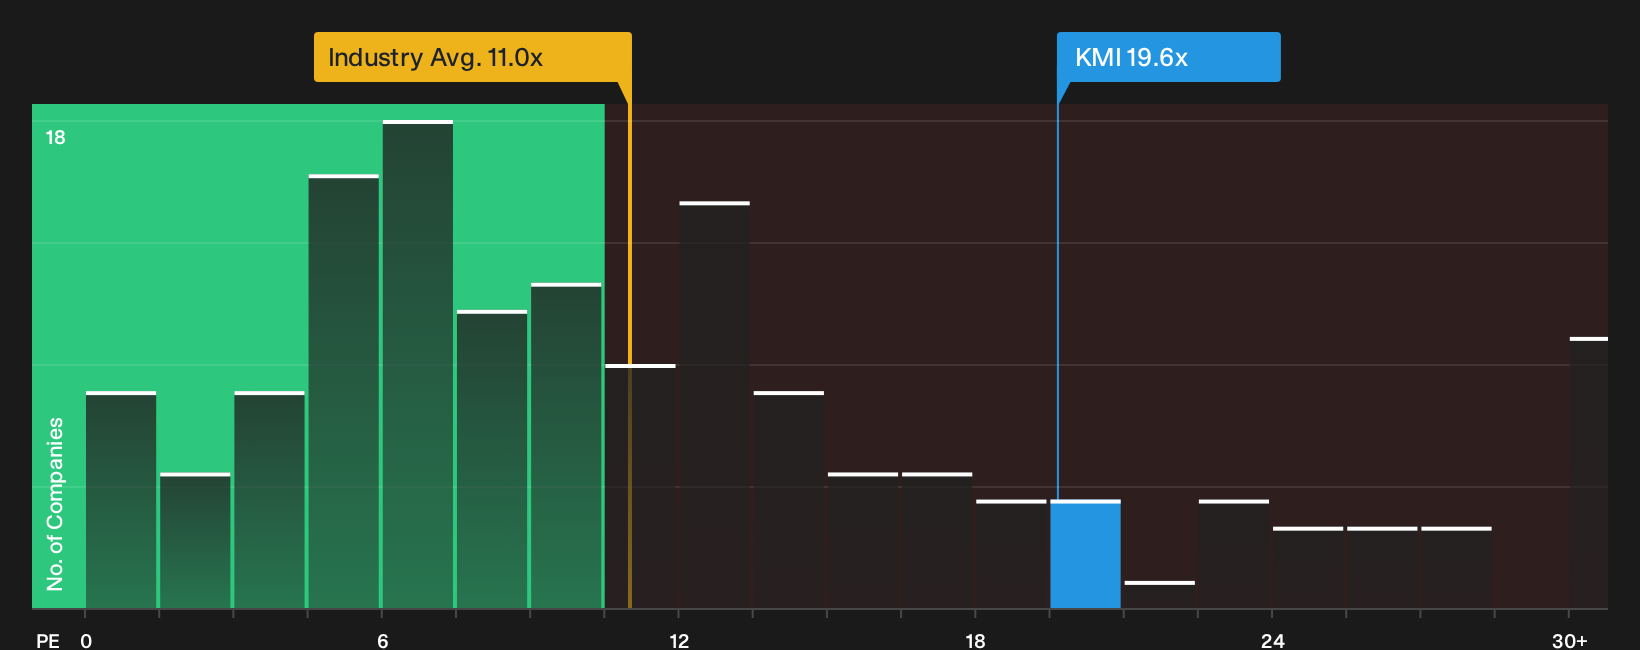
The first narrative frames Kinder Morgan as about 14.6% undervalued against a US$37 fair value. On simple pricing, the picture is less generous. KMI trades on a P/E of 19.6x, compared with 16x for peers and 11x for the wider US Oil and Gas industry, while the fair ratio sits at 20.2x. That gap suggests the stock already carries a premium that could unwind if growth or execution falls short. Does this look like mispricing, or a quality toll you are comfortable paying for the pipeline network you are buying into?
For a closer look at how this earnings multiple compares with the sector and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Kinder Morgan’s value case. That tension is exactly why it helps to inspect the numbers yourself, then weigh both risk and reward signals. To see the full picture in one place, including 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kinder Morgan?
If Kinder Morgan has your attention, use that momentum. The right tools can help you quickly spot other opportunities that fit your style and risk tolerance.
Do not just stop with one ticker. Put the Simply Wall St Screener to work and widen your watchlist with ideas filtered by quality, value and resilience.
- Target durable compounding potential by scanning for companies with strong fundamentals and staying power using the 30 resilient stocks with low risk scores.
- Hunt for mispriced quality by checking a curated pool of companies that screen as 32 high quality undervalued stocks.
- Explore potential income streams by zeroing in on stocks that feature 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com