


Progressive (PGR) has just finished rolling out Snapshot Pro, a unified telematics offering for commercial auto customers that links driving behavior with potential insurance savings and richer fleet data insights.
Recent trading suggests investors have been warming to Progressive, with the share price at US$233.53 and a 30-day share price return of 6.02% alongside an 11.81% gain over 90 days. The 1-year total shareholder return of 12.10% sits on top of a very strong 62.00% three-year and 187.53% five-year total shareholder return record, which points to momentum built over a longer horizon rather than a short-lived reaction to the Snapshot Pro rollout and other recent headlines.
Scan for insurers riding similar tech-driven tailwinds by checking the hand-picked 30 resilient stocks with low risk scores that pair resilient balance sheets with measured risk profiles.
After a 6% move in a month and a five year run that turned US$1,000 into more than US$2,400, the question around Progressive now is simple: Is meaningful upside still ahead or did most of it already happen?
Most Popular Narrative: 1% Overvalued
Progressive closed at $233.53, a touch above the analyst consensus Narrative fair value of $231.38, which the analyst consensus Narrative on Simply Wall St builds from detailed revenue, earnings, and discount-rate assumptions.
"The current valuation for a stock this narrative holds to be fairly valued and bearish implies that the market already prices in Progressive’s data and distribution advantages and its capital return record, while assigning meaningful risk to slower policy growth, higher combined ratios, and a more competitive auto market."
See why 75 investors see Progressive as 1% overvalued.
Result: Fair Value of $231.38 (ABOUT RIGHT)
Still, the narrative around Progressive can crack if competition forces more deflationary auto pricing, or if higher claims severity keeps squeezing the combined ratio and net income.
Find out about the key risks to this Progressive narrative.
Another View: Progressive Through A Cash Flow Lens
Analysts looking at Progressive through earnings multiples see a stock priced roughly in line with their $231.38 fair value, yet the SWS DCF model paints a very different picture. On that framework, PGR at $233.53 trades about 50% below an estimated future cash flow value of $468.77. Which story do you trust more: the near term earnings snapshot or the longer term cash stream?
For investors who lean on intrinsic value and want to see the full calculation behind that cash flow view, Look into how the SWS DCF model arrives at its fair value.
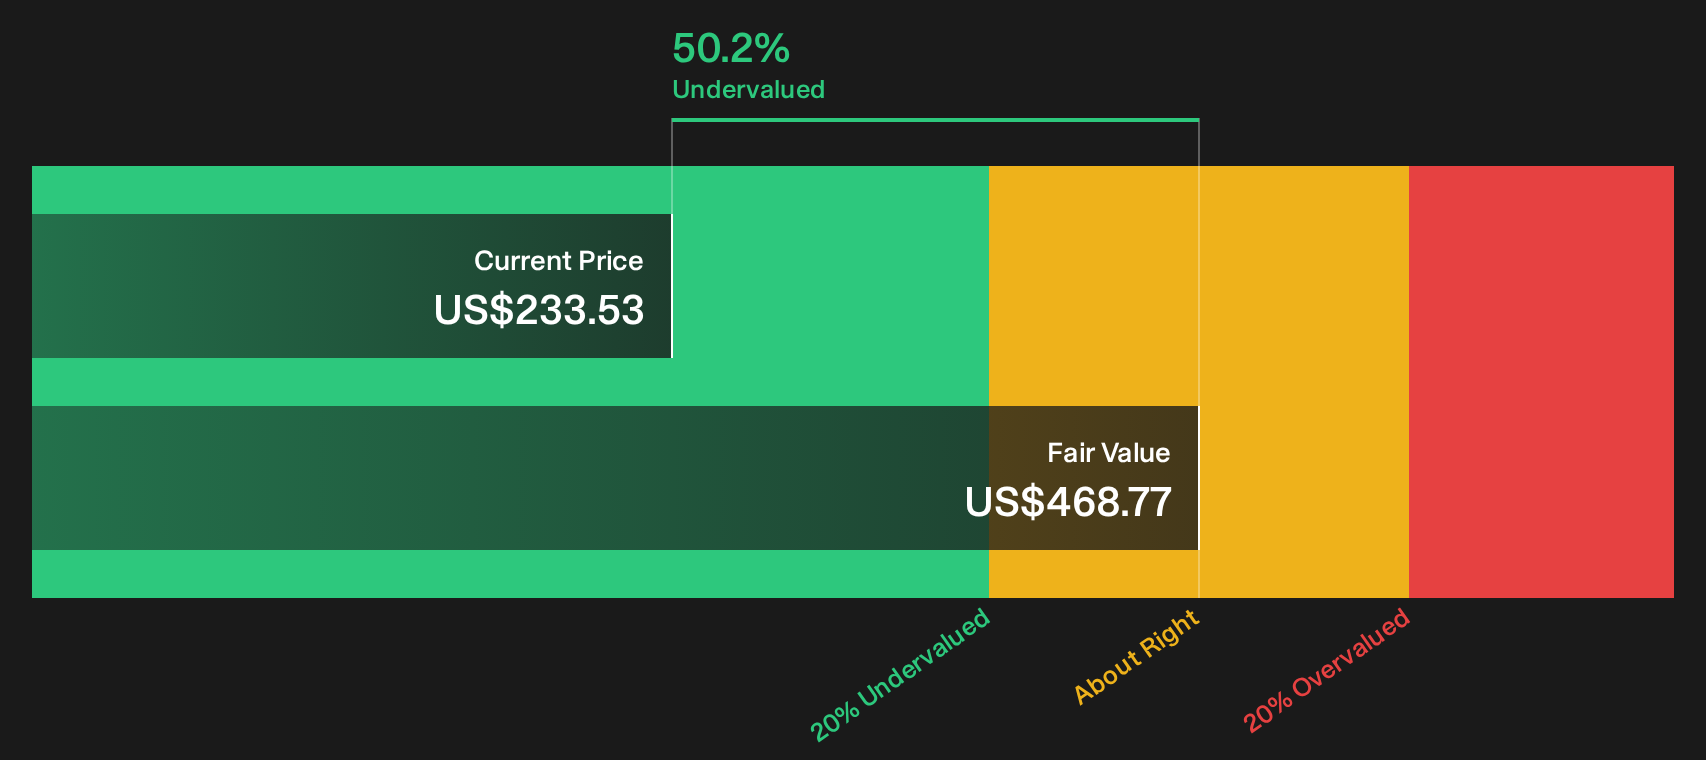
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Progressive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed tone on Progressive has you curious rather than convinced, take a close look at both sides of the ledger and stress test the story yourself. To weigh the upside potential against what could go wrong, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Progressive?
If Progressive has sharpened your focus on quality and price, do not stop here. Use Simply Wall St's screener tools to surface fresh opportunities before others move.
- Target value opportunities by reviewing companies in the 32 high quality undervalued stocks that combine lower prices with solid underlying financials.
- Strengthen portfolio resilience by scanning the list of solid balance sheet and fundamentals (24 results) and focus on businesses with sturdier financial foundations.
- Hunt for off-the-radar potential by checking the 19 high quality undiscovered gems that pair strong fundamentals with lower market visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com