


- Olin Corporation reported third quarter 2026 sales of US$1,747.7 million with net income of US$14.4 million, and a net loss of US$81.9 million for the first nine months, despite broadly similar sales to the prior year.
- The shift from profit to loss, alongside relatively steady revenue, points to pressure on costs, pricing or mix that directly affects Olin's core chemicals and ammunition operations.
- We will look at how Olin's weaker profitability and nine month loss reshape the existing cost savings driven investment narrative.
Compare Olin's pressured earnings story with other companies that pair resilient balance sheets with steadier fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (24 results).
Olin Investment Narrative Recap
To stay invested in Olin, you need to believe the chemicals and ammunition platform can convert cost programs and portfolio tweaks into more stable earnings. The analyst consensus narrative on Simply Wall St leans on Beyond250 savings, Winchester efficiency gains and epoxy restructuring to support that idea. The recent quarter did not break that story, but the nine month loss keeps execution under the microscope.
In the short term, the main swing factor is whether margins in chlor alkali, vinyls and epoxy can firm enough to lift profitability back above interest costs. The biggest risk right now is that weak pricing, higher input costs and integration spending coincide with existing leverage, making it harder to fund the Huntsman merger and future capex without further strain.
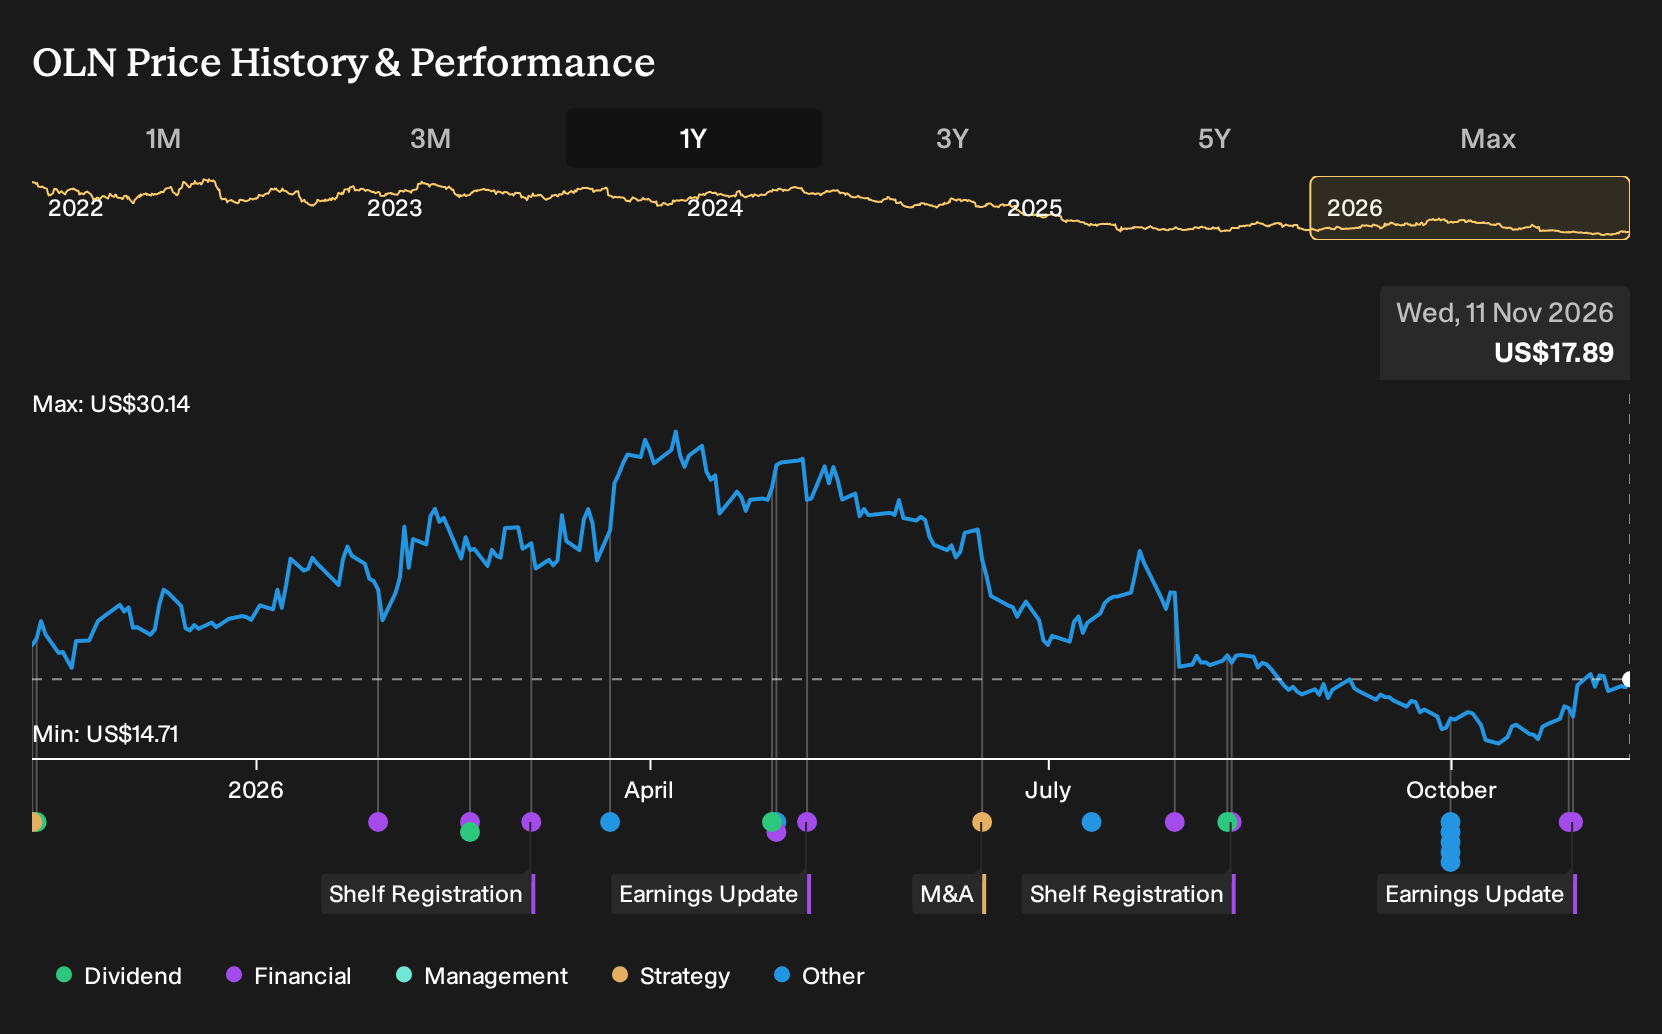
The Huntsman deal, which is expected to create OlinHuntsman with more than US$400 million of targeted cost and integration synergies, sits closest to this earnings release. With net income soft in the quarter and a loss for the first nine months, the market focus stays on whether a larger combined portfolio can support steadier cash generation once combined.
For you as a shareholder, that announcement links directly to both the main catalyst and the key risk. Successful integration would give Olin more scale across chlor alkali, vinyls and downstream products, which ties back to the cost savings narrative. Any delay in realizing those synergies, especially while interest payments are not well covered by current earnings, could extend the period of pressure highlighted by these latest results.
Olin's narrative projects US$7.7b revenue and US$226.3 million earnings by 2029. That profile lines up with analysts assuming 4.9% yearly revenue growth and an earnings increase of about US$423 million from current earnings of a US$196.9 million loss.
Uncover how Olin's fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment around Olin shifts.
Exploring Other Perspectives
One alternate view says the real swing factor for Olin is not Huntsman at all, but how much litigation and outage related costs keep eating into cash. The most cautious analysts were only modeling about US$7.3b revenue and US$185.8 million earnings by 2029, before this weak quarter, which shows how sharply opinions can differ. You are seeing that gap in expectations play out now, so it can help to explore both the consensus and these more pessimistic forecasts before deciding what this latest report means for you.
Explore 2 other Olin fair value estimates, including one that suggests as much as 45% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Olin research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Olin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Olin's overall financial health at a glance.
Looking For More Investment Ideas Beyond Olin?
Once you have a view on Olin, it can help to compare that thesis with other opportunities that line up with your risk profile, income needs and time horizon. The Simply Wall St Screener lets you scan the market using the same kind of fundamentals you have just seen, so you can spot companies that fit your own checklist instead of relying on headlines.
- If you want potential mispricing combined with stronger underlying metrics, focus on quality and value together by checking out 32 high quality undervalued stocks.
- For readers who care most about income stability, filter for payout strength and balance sheet support using the 6 dividend fortresses.
- If capital protection is your priority, concentrate on resilient financial profiles with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com