


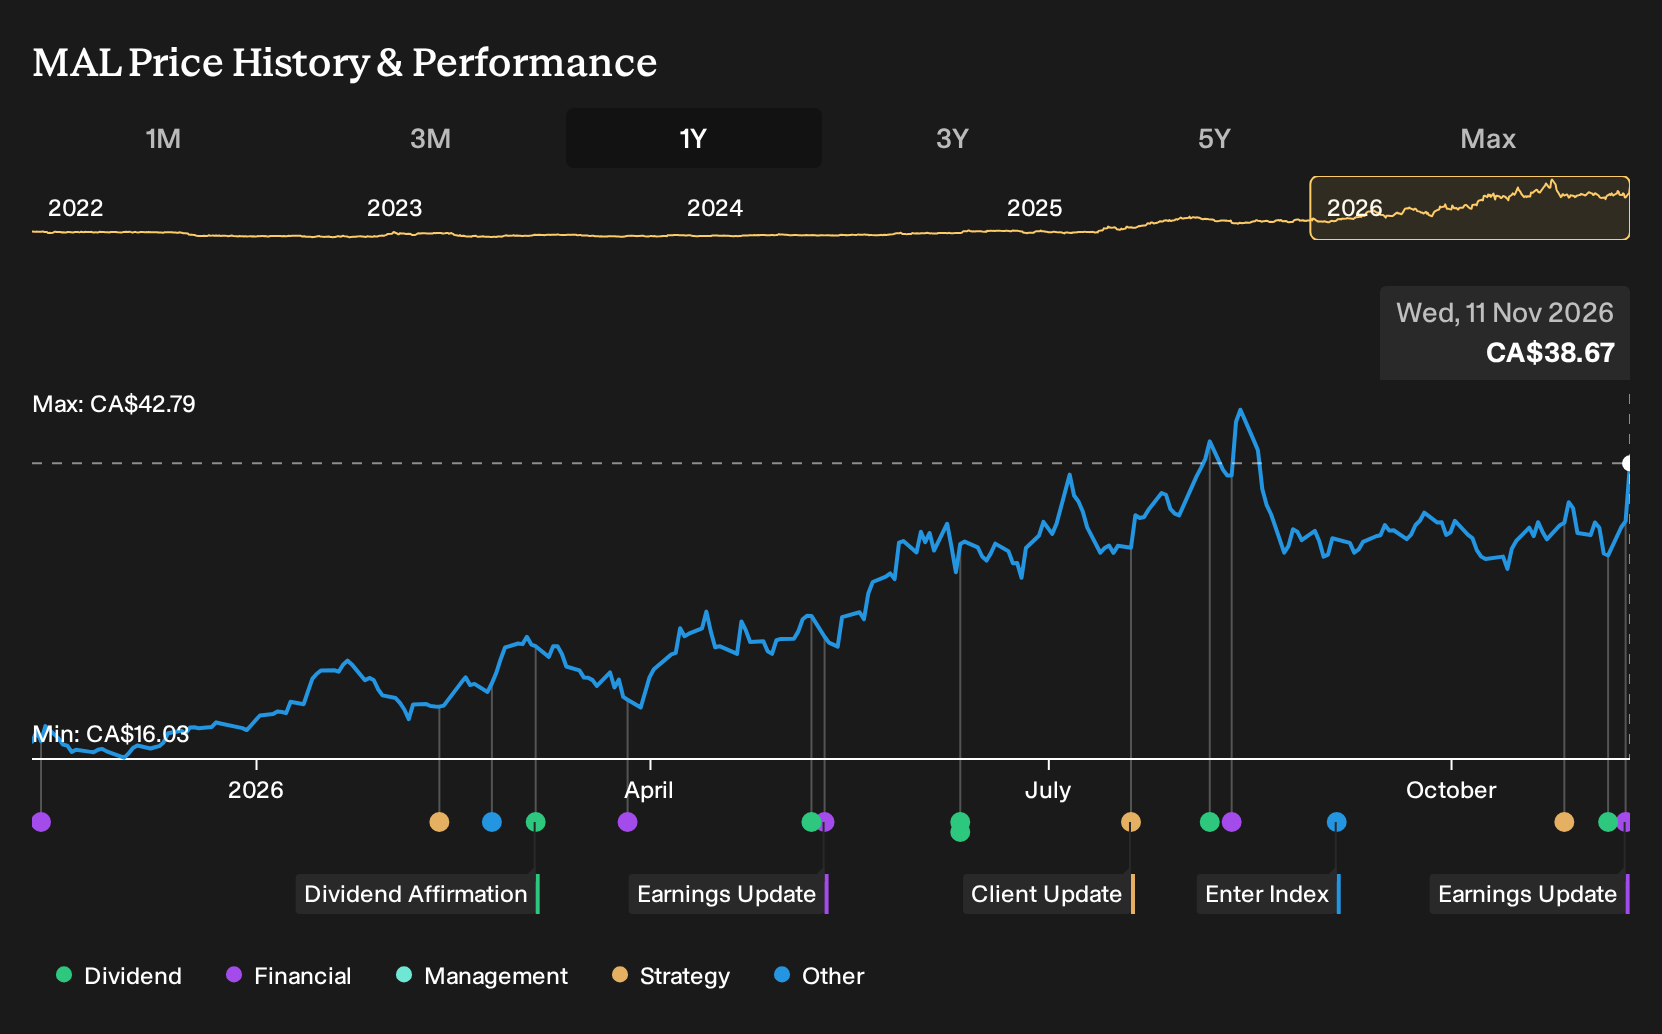
- Magellan Aerospace reported Q3 2026 sales of C$300.62 million and net income of C$19.98 million, with higher earnings per share from continuing operations compared with a year earlier. The company also affirmed a quarterly dividend of C$0.05 per share to be paid on December 31, 2026.
- The new Memorandum of Understanding with Saab on potential Canadian aerostructure manufacturing, together with stronger quarterly profit, highlights how Magellan Aerospace is seeking to deepen defence exposure while dealing with legacy issues at Middletown under Chapter 11 protection.
- We will now see how Magellan Aerospace's investment narrative could be influenced by the stronger Q3 earnings results and the Saab partnership announcement.
Magellan Aerospace Investment Narrative Recap
To own Magellan Aerospace, you need to be comfortable with an execution story. The analyst consensus narrative on Simply Wall St focuses on the idea that contract wins, facility expansions and automation projects can support profitability as volumes build. The Q3 2026 results, with higher sales and net income versus a year earlier, support that view directionally but do not remove the need for careful cost and working capital control.
In the short term, the key swing factor is how efficiently Magellan Aerospace converts its growing order visibility into margins without letting inventory, supplier issues or capital projects drag on earnings. The largest risk remains the combination of higher working capital needs and the restructuring uncertainty around Middletown, which can both absorb cash and complicate the profit story even when headline results appear stronger.
The Q3 2026 earnings release is the clearest recent marker for that thesis. Sales of C$300.62 million and net income of C$19.98 million for the quarter, alongside higher earnings per share from continuing operations, indicate that current production and pricing are supporting reported profitability. For the nine months, management reported C$891.31 million of revenue and C$56.28 million of net income, giving investors a broader year-to-date view.
Those numbers matter because they sit next to meaningful risks and catalysts. Middletown’s Chapter 11 process, elevated safety stock and a C$51 million 2025 capex plan all place pressure on Magellan Aerospace to keep earnings resilient. Stronger recent profit provides the company with more room to handle those pressures, but the core question for you is how far that operational momentum can go in offsetting restructuring costs and balance sheet strain over the coming reporting periods.
Magellan Aerospace's narrative projects CA$1.4b revenue and CA$126.8 million earnings by 2029. This implies 7.3% yearly revenue growth and an earnings increase of about CA$67 million from CA$59.6 million today.
Uncover how Magellan Aerospace's fair value indicates a potential upside of 18% to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly C$36.45 to C$46 per share, so private investors are already split on Magellan Aerospace before the latest Q3 results, the Saab MOU and the Middletown Chapter 11 process. Treat this as a starting point, and compare several alternative viewpoints before forming your own stance.
Explore 2 other Magellan Aerospace fair value estimates, including one that suggests as much as 6% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own assessment.
- A great starting point for your Magellan Aerospace research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Magellan Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magellan Aerospace's overall financial health at a glance.
Looking For More Investment Ideas Beyond Magellan Aerospace?
Once you have a view on Magellan Aerospace, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener is designed to surface stocks that match what you care about most, whether that is value, balance sheet strength or income potential.
- Prefer quality at a discount and want stronger fundamentals on your watchlist? Use the 7 high quality undiscovered gems to spot candidates that the wider market may not be fully focused on yet.
- Care most about resilient finances and capital discipline? Filter for businesses with cleaner leverage and liquidity profiles through the list of solid balance sheet and fundamentals (5 results) to see which ones meet your thresholds.
- Income is your priority and you want yield that still looks supported by the accounts? Screen for reliable payers with the 3 dividend fortresses and compare their payouts with what you see at Magellan Aerospace.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com