


ATCO has delivered a powerful run over the past few years, and with that kind of momentum investors are rightly asking whether the current share price still lines up with what its earnings can support. The issue now is whether the recent enthusiasm around the business is fully backed by the profits the company is generating.
- Over the last 5 years, ATCO has returned 159.8%, which puts a lot of focus on whether the earnings profile justifies that kind of long haul outcome.
- The expanded modular manufacturing facility in Grimsby, Ontario, may support future earnings capacity by increasing production scale and potentially improving cost efficiency as volumes build.
- There is a second opinion on ATCO worth weighing. See what analysts think ATCO's shares could be worth.
The stock's next move may depend on whether ATCO's current price can be explained by the level and quality of its earnings today.
If you want a wider benchmark for whether ATCO's earnings driven run still leaves value on the table, compare it with companies in the 5 high quality undervalued stocks
Where Does ATCO Sit on Earnings?
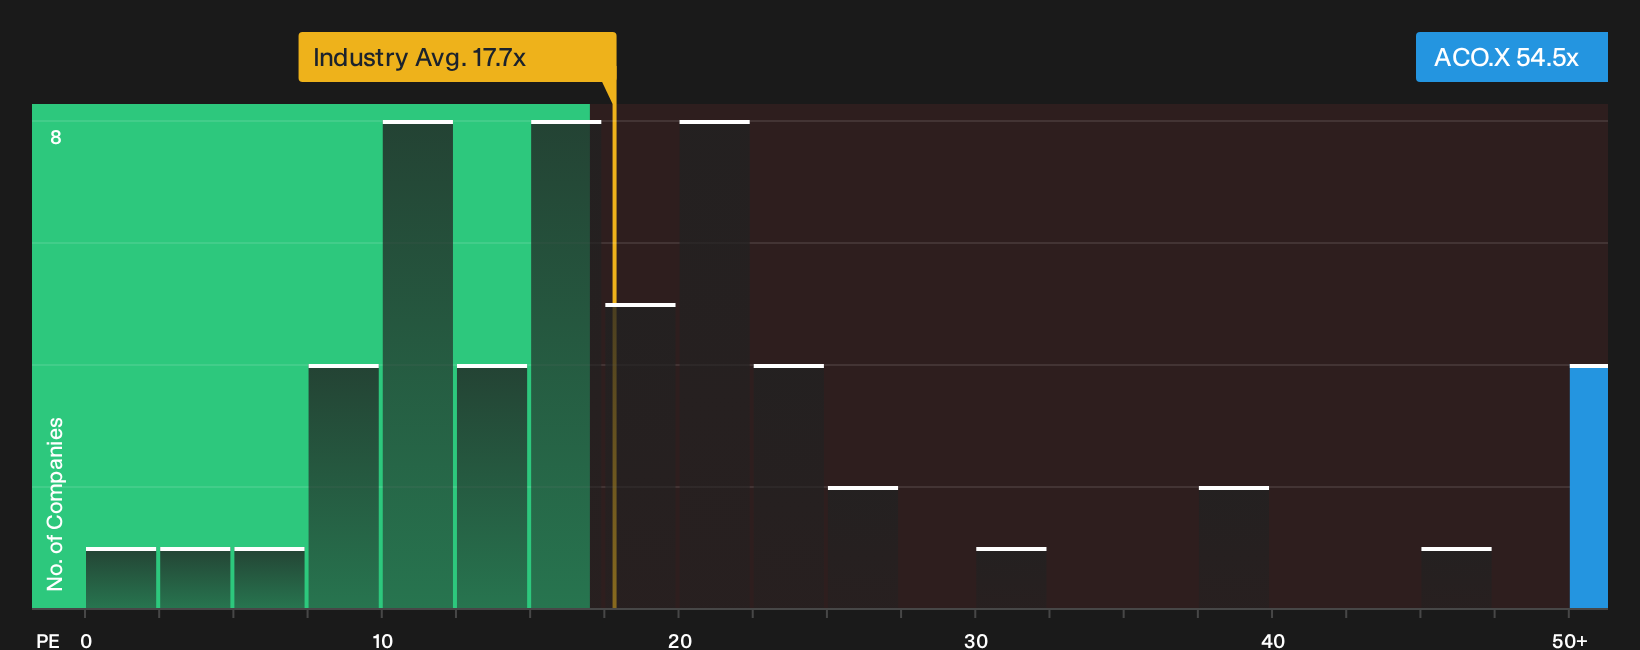
The P/E ratio suits ATCO because earnings are a primary anchor for how investors value integrated utilities. ATCO trades on a P/E of 54.5x, which is higher than the integrated utilities sector average of 17.7x and also above a peer group average of 50.0x. The tailored fair multiple for this business suggests that, given its earnings profile and risk mix, the current valuation is broadly in line with what the model would expect rather than pointing clearly to a discount or a stretch price.
Because the expanded modular manufacturing facility in Grimsby is a fresh growth plank for the group, the market may be paying up for that extra earnings potential and treating ATCO more as a platform with multiple income streams than a plain vanilla utility. For you as a shareholder, the key question is whether the quality and durability of those profits justify paying a P/E close to what the model flags as about right for this stock. Explore the numbers behind ATCO's P/E valuation.
The ATCO Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the valuation puzzle around ATCO by spelling out which future paths for growth, profitability and earnings would need to play out for the shares to trade materially higher or lower than today. They turn a single output from a ratio or model into a set of underlying assumptions, so you can watch over time whether ATCO's actual progress lines up with the scenario implied by that number.
One of the top narratives on ATCO: 7% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that ATCO successfully converts its large modular backlogs, Arctic defense opportunities and port expansions into sustained earnings and cash flow..."
Discover why this Narrative puts ATCO at 7% undervalued.
One more angle on ATCO that could shift your view
Price multiples and project backlogs only tell part of the story, because the people setting priorities at ATCO and the way their pay is structured can heavily shape future decisions and risk. See who runs ATCO and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com