


Anthropic’s planned mega IPO, with talk of a higher price range, a possible US$1.5b valuation and over US$100b in proceeds, has turned AI funding into a live stress test for equity appetite just after a US$3.2b tech sell off. Strong demand and big-ticket backing from Google, Nvidia and Microsoft create both excitement and risk. This piece walks through 3 stocks exposed to that story and why their exposure matters to you.
The three stocks below are just a sample pulled from a much wider opportunity set. The full screen surfaced 30 more large, liquid investment banks and brokers with equally compelling narratives that are not covered here. To identify and analyze those additional candidates directly, head straight into the Global Investment Banks and Equity Capital Markets Brokers screener.
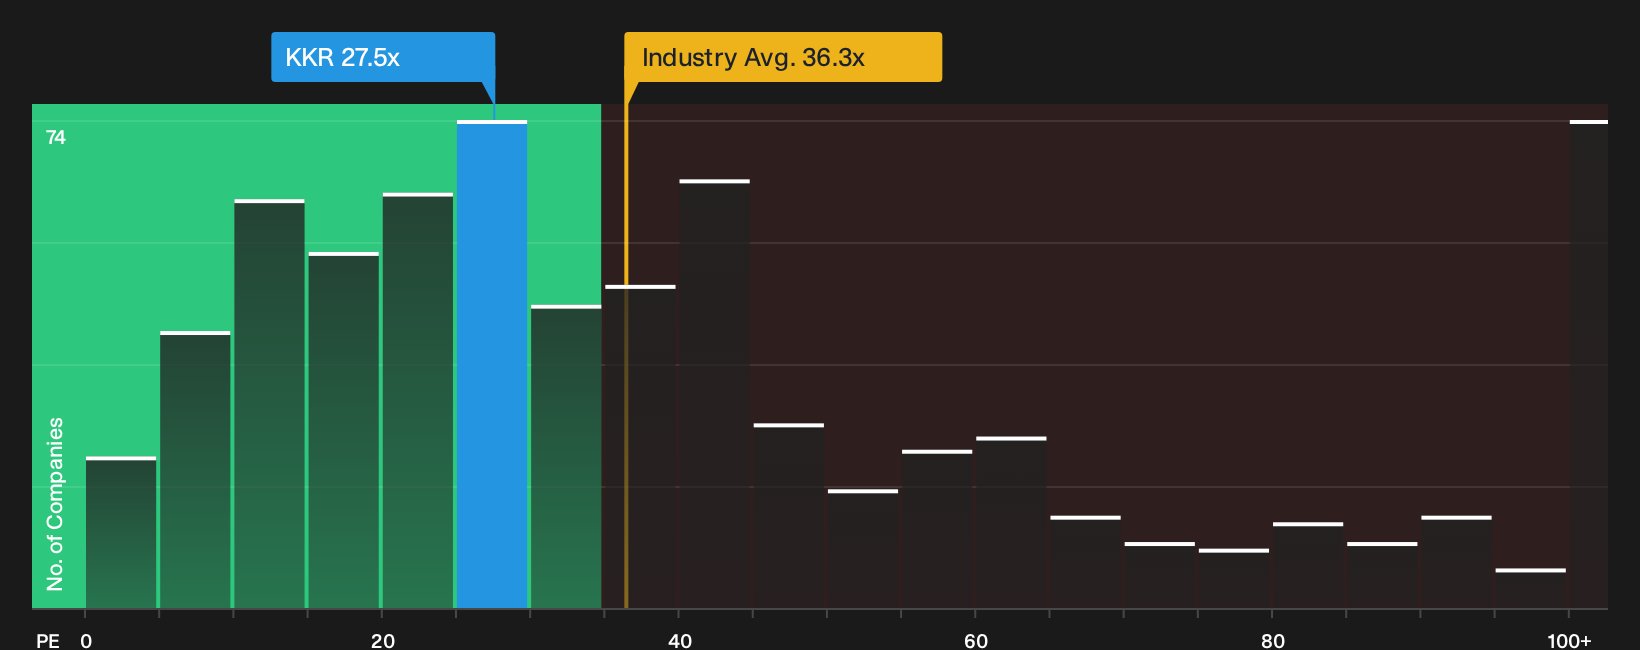
KKR (KKR)
KKR plugs into this Global Investment Banks and Equity Capital Markets Brokers theme as a large alternative asset manager that leans on public markets to exit deals, raise debt and recycle capital. The analyst consensus Narrative on Simply Wall St argues that its next leg of growth may come from a different engine to traditional private equity.
Expansion of credit and asset-based finance platforms, with KKR now a leader in a $6 trillion+ market poised for further growth, provides a broader and more durable base of fee-related earnings while also increasing the potential for performance fees as these businesses scale.
What happens to that earnings mix if one unseen pressure on funding costs and deal appetite shifts more sharply than current expectations assume?
If that shift is sharper than expected, the full narrative for KKR lays out how KKR’s credit engine could still accelerate or stall as funding conditions and exit windows change.
TPG (TPG)
TPG is another alternative asset manager tied into this Global Investment Banks and Equity Capital Markets Brokers theme, because its funds rely on healthy equity markets and deal windows when portfolio companies list or raise capital. The bullish analyst Narrative on Simply Wall St argues that this exposure could be a source of strength if conditions stay supportive.
TPG runs global alternative investment platforms that earn fees from managing private equity, credit, real estate and other assets, with its Brokerage segment generating about US$4.6b of revenue, and the stock valued at roughly US$18.8b by market cap.
TPG is positioned to capitalize on the rising global demand for alternative investments, as seen by its record fundraising momentum, inflows from both institutional and private wealth channels, and expanding suite of strategies across private equity, credit, real estate, and infrastructure. The buildout of permanent capital vehicles, such as T-POP for private wealth and evergreen structures at Peppertree, along with bespoke partnerships with institutional clients, is increasing TPG’s base of stable, recurring revenues.
What investors may need to watch carefully is how one pressure point in capital markets shapes the timing and profitability of those future exit events.
That pressure point is exactly where the full narrative for TPG shows whether TPG’s fundraising engine is accelerating, stalling, or quietly decoupling from equity market mood swings.

Lazard (LAZ)
Lazard matters in this Global Investment Banks and Equity Capital Markets Brokers theme because its advisory arm works directly with IPOs, equity deals and complex capital raisings, and its business is split between about US$1.8b from Financial Advisory and roughly US$1.5b from Asset Management on a US$4.0b market cap.
Although Lazard is embedding AI tools across banking and asset management with the aim of running smaller deal teams and lowering non MD compensation, current AI spending is modest and the 69.9% adjusted compensation ratio in Q1 and Q2 2026 shows that any productivity benefit has not yet offset elevated hiring costs.
What investors may be weighing is how one unresolved shift in deal volumes and fundraising cycles interacts with that cost base over the next phase.
If you want to see how that cost base could be masking Lazard’s next leg of operating leverage, read the full narrative for Lazard for a complete view of the risks and potential upside.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time everyone notices a breakout, the best entry points can be gone. Scan these curated shortlists while they are still under the radar for now and consider them early.
- Track cash rich compounders that blend resilience with upside by running the list of solid balance sheet and fundamentals (24 results) before the crowd prices in their strength.
- Follow structural trends in automation by scanning the 89 robotics and automation stocks while capital is still rotating toward early leaders instead of mature heavyweights.
- Review infrastructure-related opportunities by checking the 42 power grid technology and infrastructure stocks while valuations may not yet reflect the next upgrade cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com