


- SentinelOne announced new integrations with Anthropic’s Claude Cowork and Claude Mythos 5.1, extending its Singularity and Wayfinder AI security coverage into virtual machines on macOS and Windows and into human plus AI vulnerability assessment services.
- The move pulls SentinelOne’s Behavioral AI detection engine and agentic detection directly into one of the most widely used AI coworking tools. This tightens control over previously hard to monitor activity and aims to make remediation guidance more focused on exploitable risks.
- We will look at how SentinelOne’s tighter security integration inside Claude Cowork’s virtual machines feeds into the broader investment narrative.
Scan beyond SentinelOne and this Claude integration story by reviewing a hand picked group of AI security and infrastructure plays in our 53 AI infrastructure stocks.
SentinelOne Investment Narrative Recap
To own SentinelOne, you need to be comfortable with a cyber security business that is still loss making on a GAAP basis and investing heavily to extend its AI driven platform. The analyst consensus narrative on Simply Wall St leans on revenue that is forecast to rise about 14.4% a year and on efforts to improve operating leverage over time.
The key near term swing factor remains how effectively SentinelOne converts that AI led product buildout into higher value customer relationships without eroding margins or relying too much on dilution after the US$1.25b convertible notes. The Claude Cowork and Claude Mythos integrations sharpen the AI security story, but do not materially change that central risk reward trade off yet.
The announcement that Wayfinder Frontier AI Services will add Anthropic Claude Mythos 5.1 sits alongside this Claude Cowork integration. It keeps SentinelOne’s AI security portfolio anchored in frontier models while leaning on human experts to filter which vulnerabilities are truly exploitable and which can safely wait.
For you as an investor, the interest here is operational. If Wayfinder and Singularity Agentic Detection and Response help customers cut through noisy alerts and focus on validated risks, that supports the catalysts around cross sell, higher average contract value and stickier AI security ARR. Execution risk is clear though, with heavier competition from larger cyber vendors and a business that is still working toward profitability.
SentinelOne's narrative projects US$1.8b revenue and US$224.8 million earnings by 2029. This assumes 18.3% yearly revenue growth and an earnings increase of roughly US$565 million from current earnings, compared with a US$340.1 million loss today.
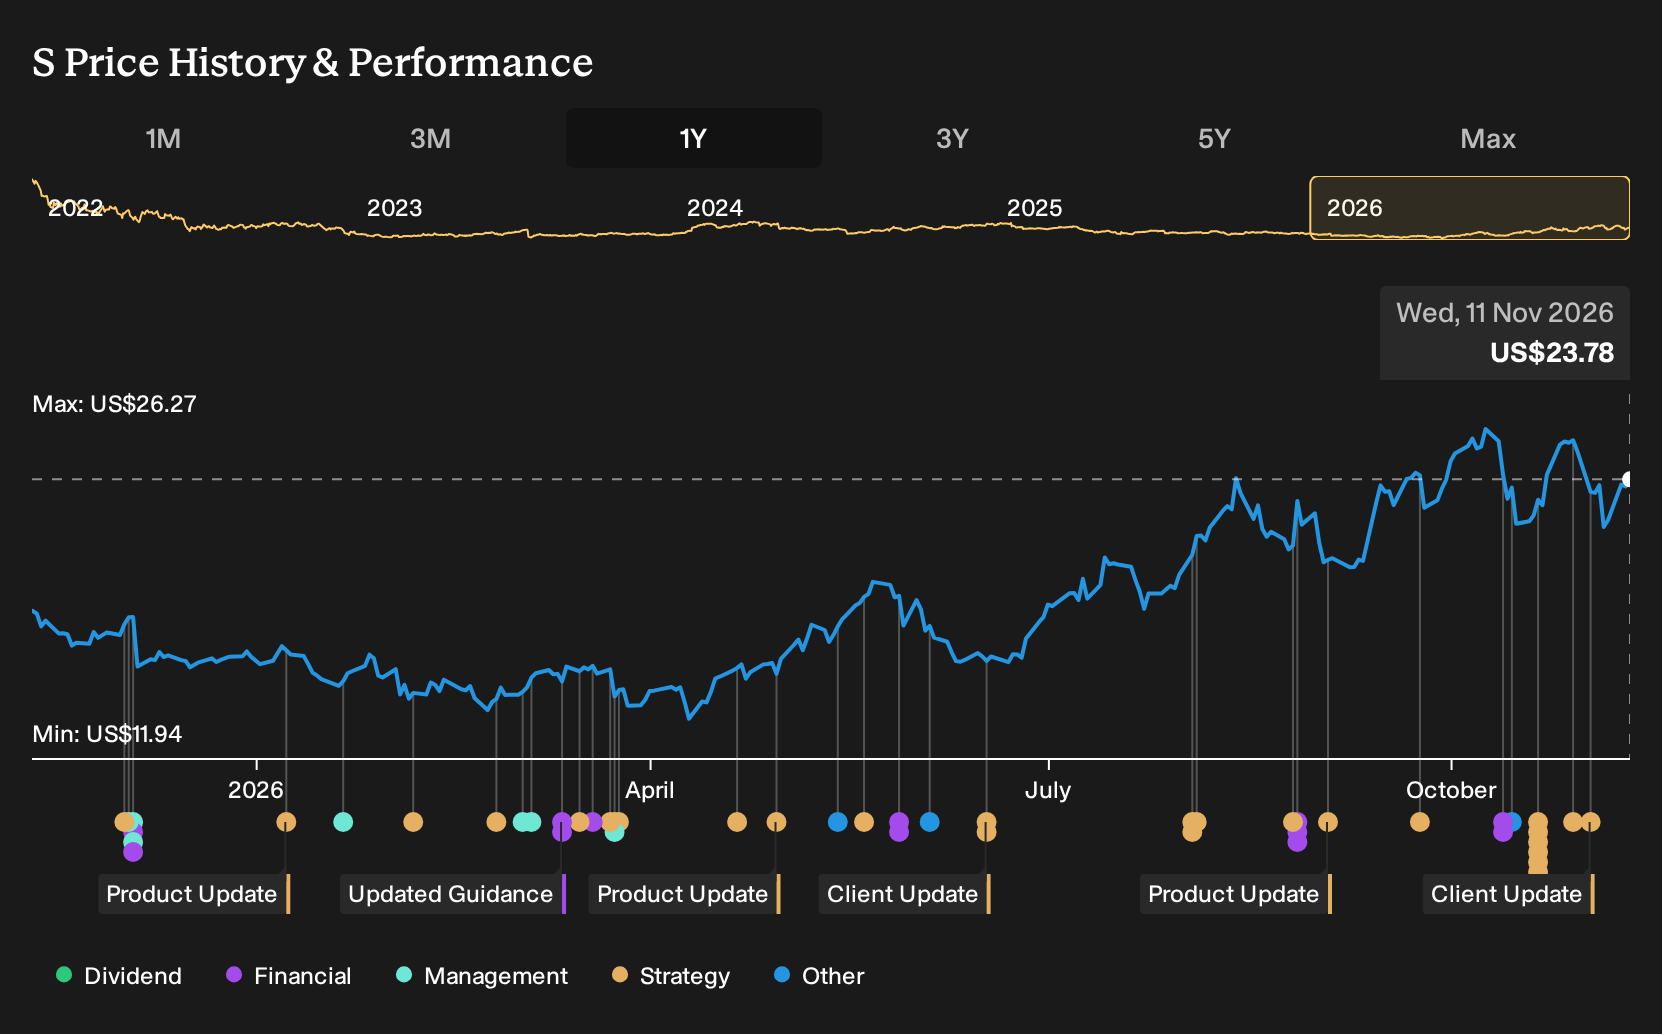
Uncover why SentinelOne's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor is regulatory and localization pressure on SentinelOne. The most bearish analysts were penciling in 17.3% yearly revenue growth and about US$208.3 million earnings by 2029 before this Claude Cowork integration. That is a more cautious story. Use this news as a prompt to compare those assumptions with your own and explore how opinions can shift as fresh information lands.
Explore 3 other SentinelOne fair value estimates, including one that suggests it could be worth just $24.92.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SentinelOne research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SentinelOne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SentinelOne's overall financial health at a glance.
Looking For More Ideas Beyond SentinelOne?
If this SentinelOne story has sharpened your thinking on AI security, you can use that same lens to size up other opportunities. The Simply Wall St Screener can help you quickly filter for companies that better match your risk appetite and income goals.
- If capital preservation sits high on your list, you might start with a basket of 30 resilient stocks with low risk scores that score well on resilience and downside protection.
- For investors interested in mispriced quality, you could scan through a curated 32 high quality undervalued stocks that combine stronger fundamentals with more modest expectations reflected in the price.
- If income is a priority, you may wish to anchor your research around a focused set of 6 dividend fortresses that aim to pair higher yields with sturdier payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com