


Stronger earnings and higher guidance put Ardent Health in focus
Ardent Health (ARDT) drew investor attention after third quarter results showed sales of US$1,624.86 million and a swing to US$44.52 million in net income, alongside raised full year revenue and earnings guidance.
The stronger third quarter and raised outlook quickly fed into the share price, with Ardent Health logging a 7 day share price return of 40.03% and a 30 day gain of 57.76%. The year to date share price return of 110.53% contrasts with a 1 year total shareholder return of 29.47%, suggesting that momentum has accelerated only recently as earnings and guidance updates reset expectations.
Scan how Ardent Health compares with other hospital and healthcare operators that show strong momentum and fundamentals using our hand picked list of solid balance sheet and fundamentals (24 results).
After a 110.53% year to date jump, the real tension around Ardent Health now sits in a simple question: Has the valuation already absorbed the better guidance, or is the market still discounting more of the upside?
Most Popular Narrative: 29% Overvalued
Ardent Health last closed at $18.19 compared with the analyst consensus Narrative on Simply Wall St fair value of $14.13. This frames the recent share price surge as richer than the implied long term outlook.
Ardent's strong presence in fast-growing, midsized U.S. markets with favorable demographic trends is described as positioning it to benefit from increasing healthcare demand associated with an aging population and rising chronic disease prevalence, which in turn is viewed as supportive of top-line revenue and patient volumes. Company investments in expanding the ambulatory and urgent care footprint, including ongoing projects and recent acquisitions, are characterized as enabling access to higher-margin outpatient services and a larger patient base, which is expected to support net margins and more diversified recurring revenues.
See why 1 investors see Ardent Health as 29% overvalued.
Result: Fair Value of $14.13 (OVERVALUED)
Still, the Ardent Health story hinges on keeping payer denials and Medicaid funding risks in check, since pressure on reimbursements could quickly challenge the idea that the company is currently overvalued.
Find out about the key risks to this Ardent Health narrative.
Another View on Ardent Health’s Valuation
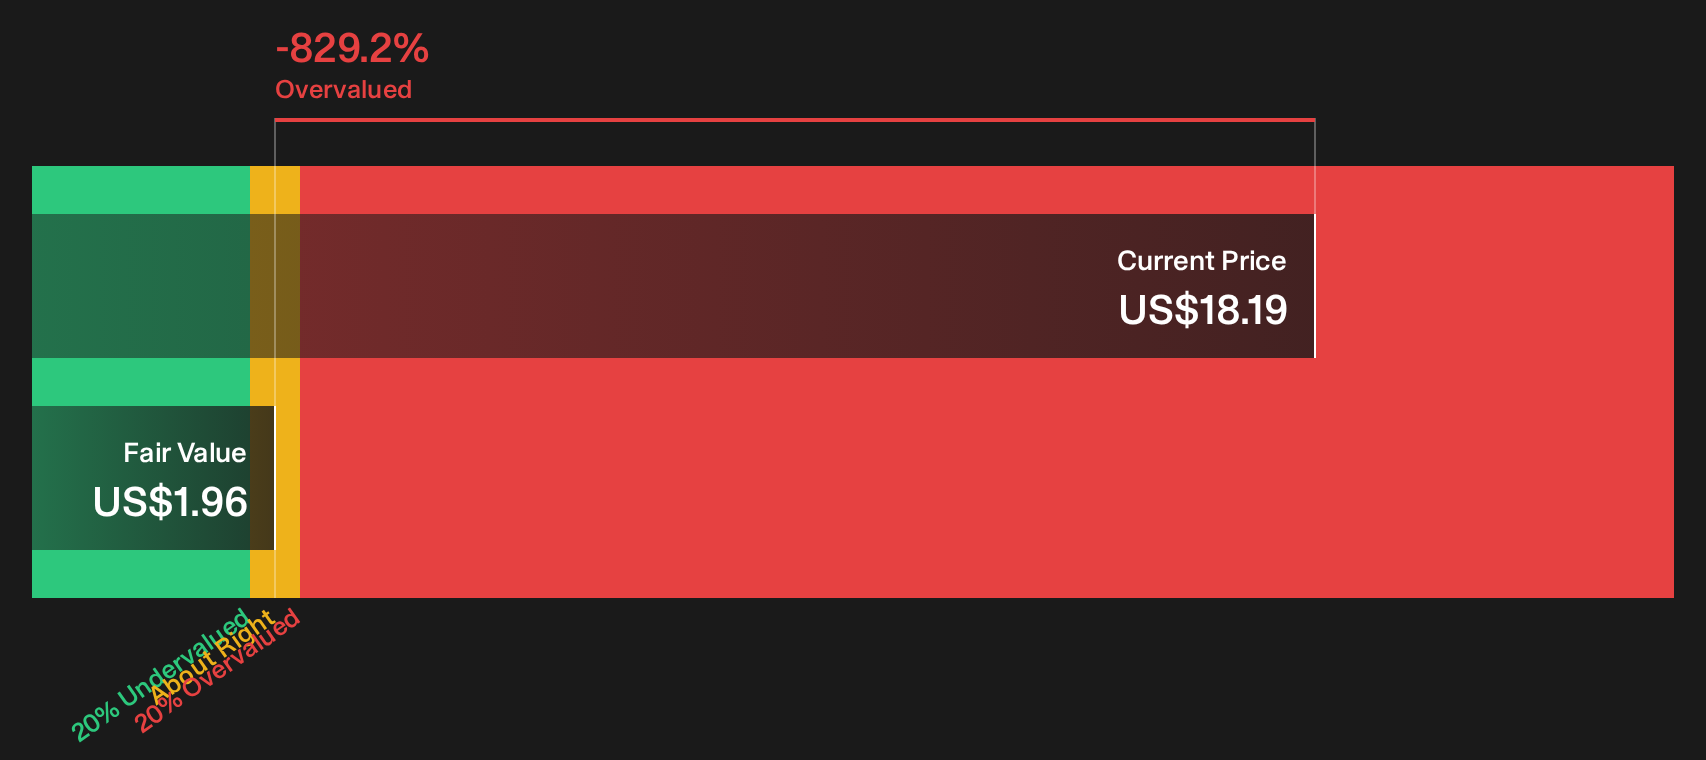
The Simply Wall St DCF model presents a much more conservative view of Ardent Health than the $14.13 fair value from analyst narratives. On that cash flow view, the shares at $18.19 are described as trading well above an estimated future cash flow value of $1.96. It raises a direct question for investors: which lens do you trust more, earnings multiples or long range cash flow calculations?
For a closer look at how this cash flow based view is constructed, including the key assumptions behind it, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Ardent Health's valuation can feel uncomfortable, especially after such a sharp move. Act while the data is fresh and form your own stance by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ardent Health?
If Ardent Health has sharpened your focus on opportunities, do not stop here. Broaden your watchlist with ideas filtered by quality, value, and resilience.
- Target value with discipline by scanning a curated set of 32 high quality undervalued stocks that combine quality fundamentals with attractive pricing.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and historically steadier risk profiles.
- Hunt for under-the-radar potential using a 19 high quality undiscovered gems that highlights financially solid businesses still off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com