


Global power grids are being expanded at record speed, with new transmission lines growing 50% last year, and that surge in electrification is drawing attention to fast growing British companies where insiders have meaningful skin in the game. When founders and executives hold sizable stakes, their interests are closely aligned with yours. This article looks at three such growth focused UK stocks that combine rapid expansion with high insider ownership.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management is heavily invested alongside you. However, if you want the strongest names, these 5 high growth high conviction stocks are at the top of the list.
International Workplace Group (LSE:IWG)
International Workplace Group runs one of the largest global flexible office networks, with coworking, memberships and virtual offices at the heart of its growth angle in this screener. Most revenue comes from company owned centres generating about US$3.3b, with managed and franchised operations adding US$151 million, and the group is valued at roughly £2.0b.
The analyst consensus Narrative on Simply Wall St frames International Workplace Group as a business leaning into capital light, recurring workspace fees to support a faster growth profile that still aligns management closely with shareholders.
"The rapid mix shift toward managed and franchised locations, with these formats now a much larger share of system revenue, locations and rooms and supported by a pipeline of hundreds of thousands of contracted rooms, points to potential future expansion in fee based revenue and scope for higher net margins as the network matures."
What happens to margins and cash generation if that quieter shift in how IWG earns its money accelerates faster or slower than expected?
If that shift in earnings mix is what you are watching, the full narrative for International Workplace Group shows how IWG’s capital light model could accelerate or stall that margin story.

Playtech (LSE:PTEC)
Playtech is a London based gambling software specialist whose growth story in this screener is tied to its online platforms for casino, live casino, sports betting and virtual sports. It generates about €736 million from B2B activities, with smaller B2C units like Sun Bingo adding around €65 million and the group valued at roughly £1.0b.
For investors focused on fast growing platforms backed by confident management, Playtech offers an example of how recurring online gaming fees and content royalties can turn software into a cash engine. The analyst consensus Narrative on Simply Wall St sets out how that plays through the numbers.
"The growing portfolio of structured agreements and equity stakes, which already carries a book value of around €1.0 to €1.2 billion and is contributing material investment income from assets such as Caliente and Hard Rock Digital, creates an additional stream of earnings and cash flow that is not purely tied to software fees."
The real swing factor is how one pressure point in Playtech’s regulated online gaming push ultimately shapes long term margins and cash generation.
That margin swing is exactly what the full narrative for Playtech unpacks, revealing how Playtech’s agreements and equity stakes could affect earnings power if execution keeps compounding.

Greencore Group (LSE:GNC)
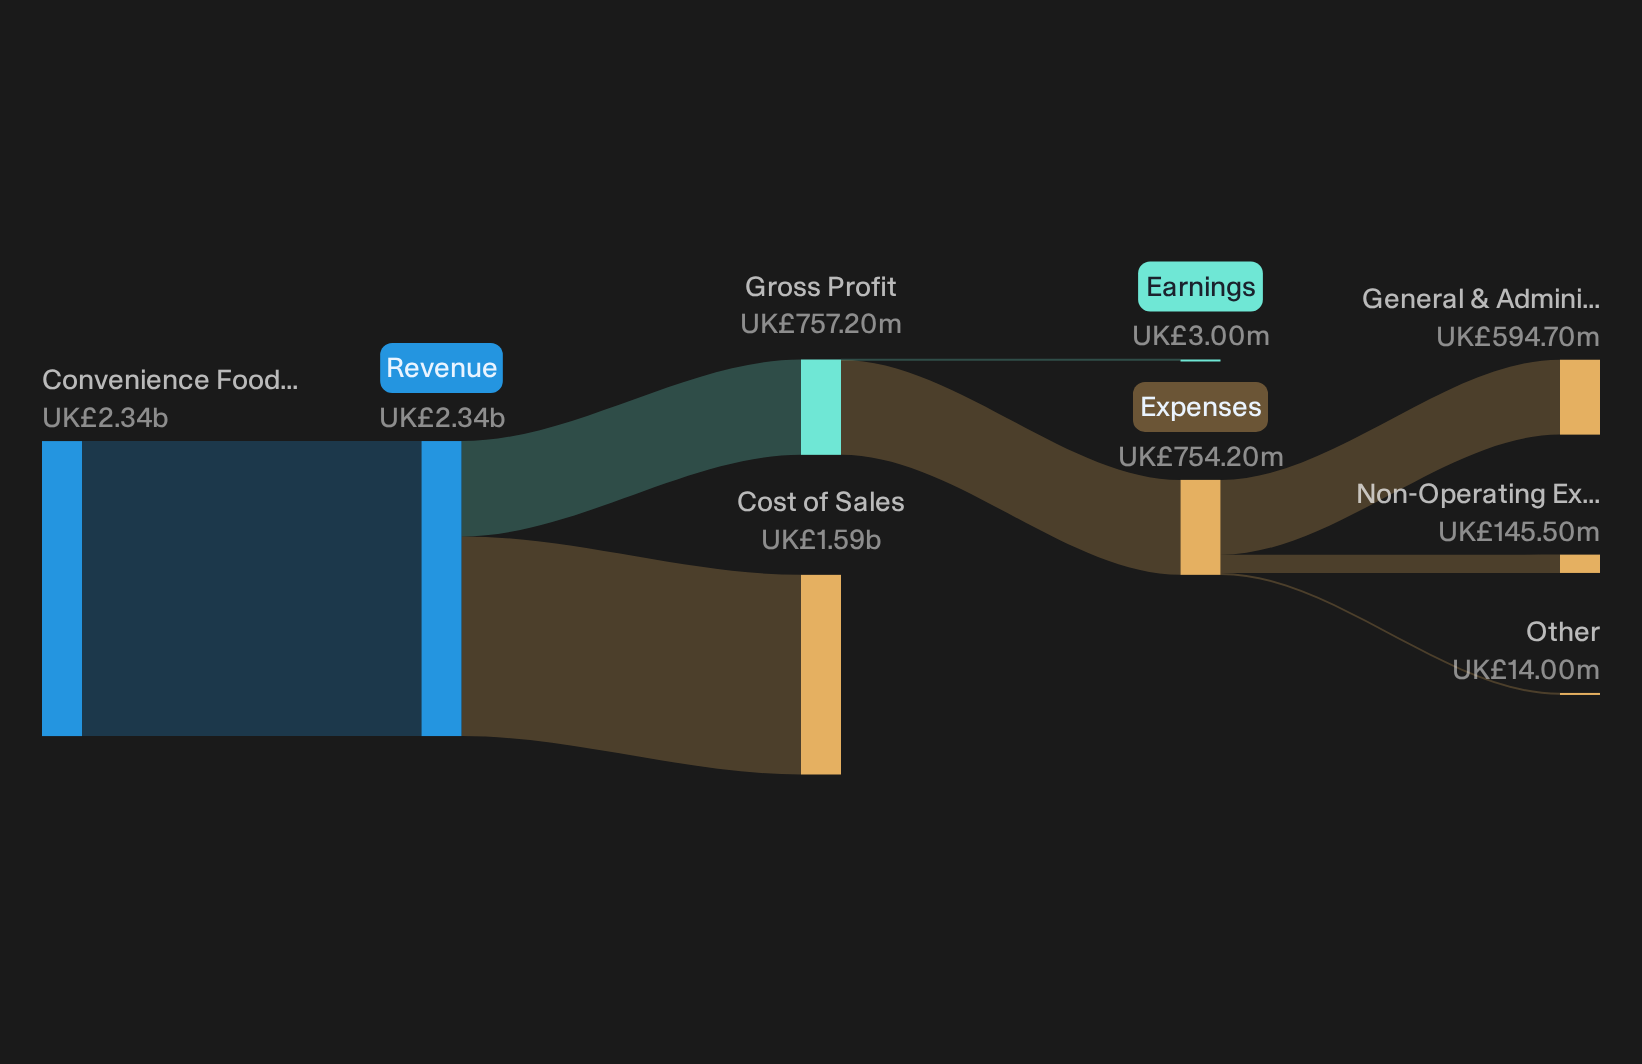
Greencore Group is a Dublin headquartered producer of chilled and ambient convenience food such as sandwiches, salads, sushi and ready meals, with the growth angle coming from higher demand in convenience led retail and foodservice channels. It generates about £2.3b from Convenience Foods UK & Ireland and is valued at roughly £2.4b.
The interest in Greencore Group for this fast growing, insider backed screen comes from how its chilled convenience foods arm feeds into higher growth channels, and the way the analyst consensus Narrative on Simply Wall St frames the operational playbook behind that push.
"Operational excellence programs and a five year automation roadmap, which have already lifted units per labour hour and target at least 10% direct labour savings over time, can continue to support higher operating margins and earnings as more projects are rolled out across Greencore Group sites."
What happens to Greencore Group’s earnings power if one quiet constraint on cash generation and balance sheet flexibility does not improve as quickly as planned?
If that constraint is what you are weighing, the full narrative for Greencore Group explains how Greencore Group’s cash generation story could accelerate as execution improves.
Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move first. Breakout stories can gather momentum while they are still under the radar, and information advantage can drop fast. Scan the next wave and try to position early.
- Look for steady growers with robust cash generation and flexible balance sheets by running the list of solid balance sheet and fundamentals (9 results) before the crowd fully catches on.
- Search for potential future cash generators in automation and manufacturing by scanning the curated list of 89 robotics and automation stocks while valuations still look reasonable.
- Focus on critical infrastructure suppliers related to electrification trends with a targeted review of the 42 power grid technology and infrastructure stocks before broader interest increases.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com