


Otter Tail (OTTR) just paired a weaker third quarter profit picture with a tighter full year earnings range and a maintained dividend, giving investors fresh information on both cash flows and management expectations for 2026.
Otter Tail’s latest guidance tweak and dividend decision landed against a softer price backdrop, with the share price down 11.92% over the past 30 days and 16.21% over 90 days, while the 5 year total shareholder return of 29.60% points to much steadier long run momentum.
Compare Otter Tail's recent pullback and dividend stance with other income-focused utilities by scanning our hand picked 6 dividend fortresses that aim to balance yield with financial resilience.
For Otter Tail, a weaker profit run and a firmer full year earnings range now sit next to a falling share price. Is this the moment to step in, or does patience around a cheaper entry make more sense as valuation gets unpacked next?
Most Popular Narrative: 14% Undervalued
Otter Tail closed at $77.82 against a fair value of $90.50 in the analyst consensus Narrative on Simply Wall St, which incorporates analysts’ revenue, earnings and discount rate assumptions to frame where the shares might trade if those forecasts play out.
Continued execution of Otter Tail’s US$1.9b electric capital program, with a reaffirmed 10% rate base CAGR and nearly 1:1 conversion of that rate base growth into utility earnings, is expected to support future EPS. The main thing that has to go right is that Otter Tail successfully integrates large-load growth, renewables, storage projects and plastics cash flows while managing regulatory, legal and financing risks so the utility earnings trajectory and customer affordability targets remain intact.
See why 3 investors see Otter Tail as 14% undervalued.
Result: Fair Value of $90.50 (UNDERVALUED)
Still, short interest near 15.64% and the PVC antitrust settlements draining US$103.5 million leave the Otter Tail narrative exposed if legal or pricing pressures deepen.
Find out about the key risks to this Otter Tail narrative.
Another View: Otter Tail Through The P/E Lens
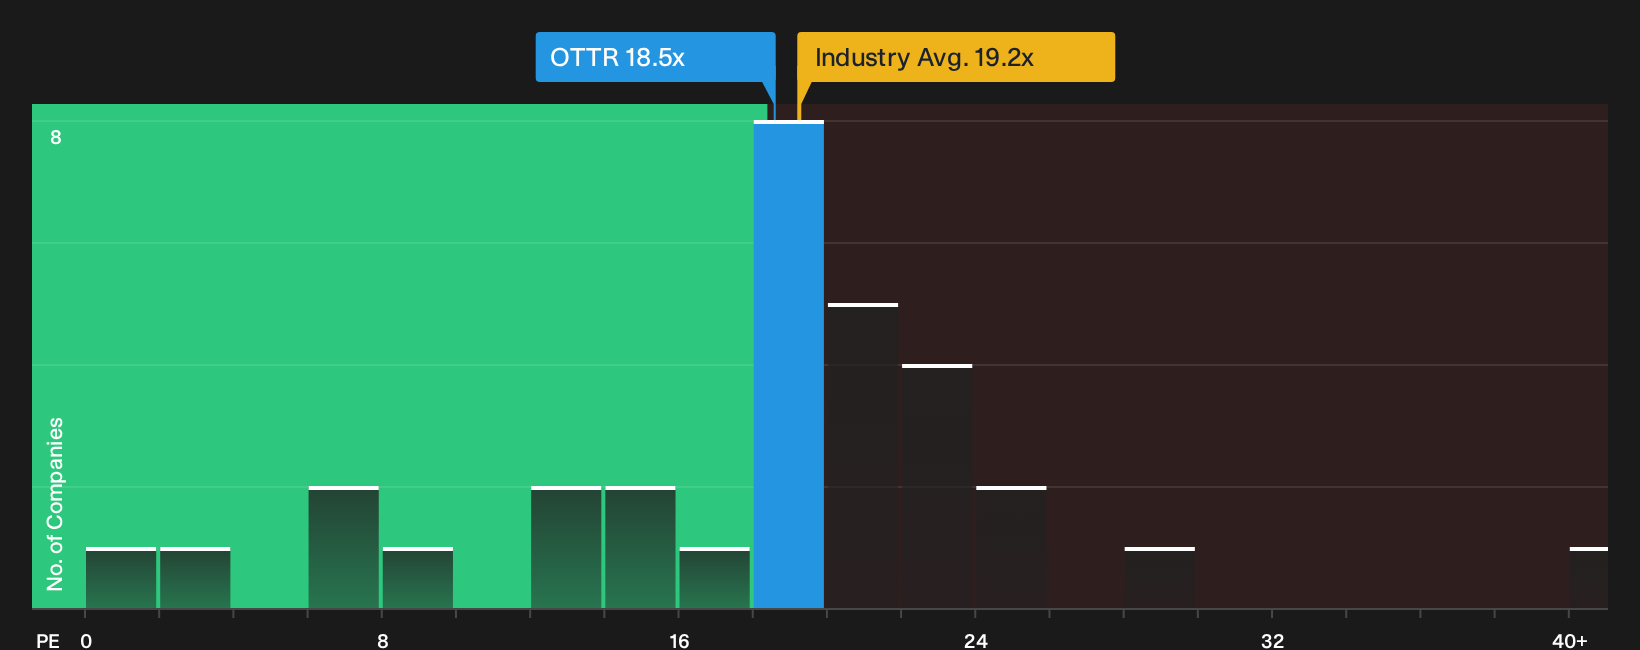
Analysts on Simply Wall St pitch Otter Tail as about 14% undervalued against a $90.50 fair value, yet the P/E picture is more cautious. The stock trades on 18.5x earnings compared with a fair ratio of 15.9x and an Electric Utilities average of 19.2x, which points to limited margin for error if earnings underwhelm.
That mix of a discount to one fair value and a premium to another leaves a simple question for investors. Which signal carries more weight for you when sentiment turns: the narrative target, or the ratio that the market could move toward as expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Otter Tail’s valuation and legal overhangs can feel messy, so consider reviewing the 1 key reward and 4 important warning signs to quickly weigh the trade off for yourself.
Looking for more investment ideas beyond Otter Tail?
If Otter Tail has sharpened your focus on valuation and risk, you can use that momentum to line up a few more candidates before the next move passes you by.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results), which highlights companies with financial structures designed to absorb shocks.
- Hunt for potential mispricings with the 32 high quality undervalued stocks, which surfaces businesses where fundamentals and market prices appear out of sync.
- Prioritise income potential with the 6 dividend fortresses, which focuses on companies aiming to combine higher yields with durable cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com