


- Calix reported third quarter 2026 revenue of US$301.71 million compared with US$265.44 million a year earlier, while net income declined to US$10.22 million and diluted EPS from continuing operations moved to US$0.16 from US$0.22.
- Across the first nine months of 2026, Calix recorded US$875.03 million of revenue and US$38.54 million of net income, highlighting higher year to date profitability despite the weaker quarterly EPS print.
- Next, the focus turns to how Calix's higher sales but softer quarterly earnings per share might influence the existing investment narrative.
Compare Calix's mixed earnings picture with peers by scanning a hand picked set of 42 power grid technology and infrastructure stocks that are shaping the future of broadband and grid connectivity.
Calix Investment Narrative Recap
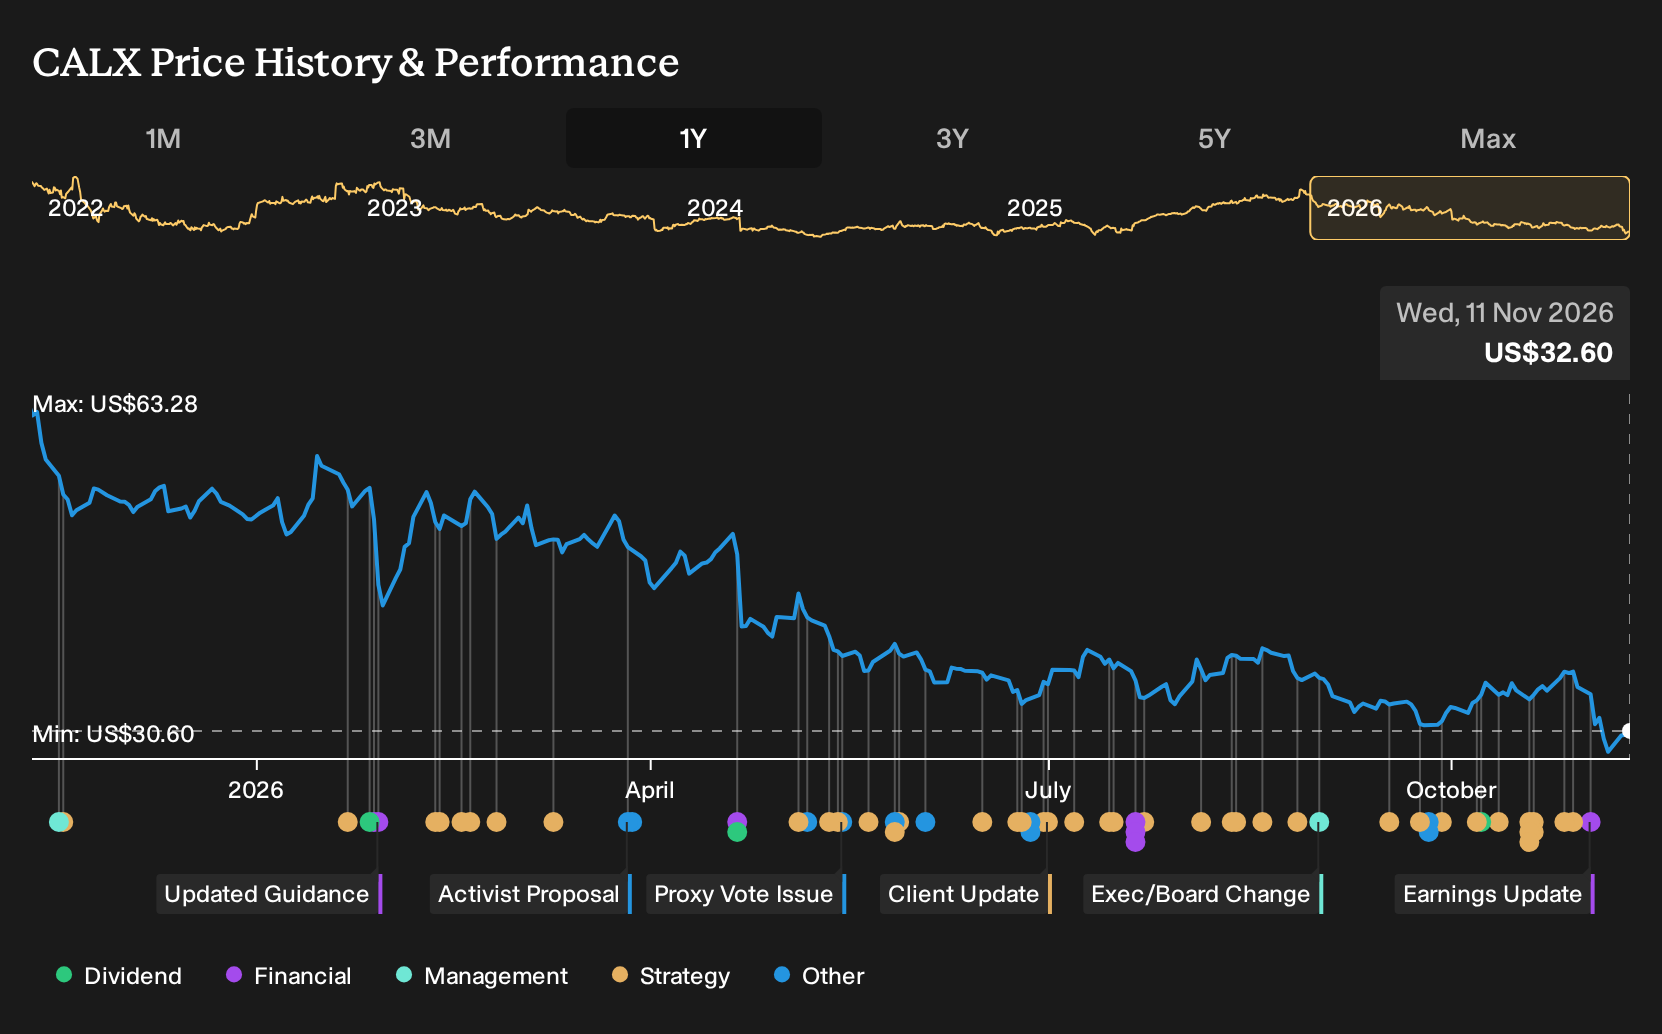
To own Calix, you need to be comfortable with a story where software and cloud services gradually matter more than hardware. The analyst consensus Narrative on Simply Wall St leans on that idea and on converting a larger addressable market into contracts. The latest quarter fits that arc only partially. Revenue moved higher, yet quarterly EPS softened, so near term execution on margin remains the key swing factor.
The biggest near term catalyst is whether Calix can keep lifting software and services contribution, which analysts link to better recurring economics. The main risk remains margin pressure from memory costs and any fallout from ongoing shareholder investigations. This earnings update does not remove those concerns. It shows instead that they are being managed alongside growth.
The BOYCOM Cablevision update lines up neatly with those catalysts. BOYCOM used the Calix One platform, GigaSpire hardware and the CommandIQ app to lift ARPU by more than 20% in rural Missouri. At the same time, they cut repair driven work by about 28% and reduced their active fleet by 20%. This speaks directly to the operational value proposition Calix is selling to broadband providers.
For you as a shareholder, that case study links the income statement story to real world usage. It suggests how Calix SmartLife and cloud tools can influence customer economics, retention and pricing power. That, in turn, ties back to software heavy growth and margin quality. Execution risk remains significant, particularly around component costs and governance questions. Even so, accounts like BOYCOM show how the current product set can feed the catalysts analysts are focused on.
Calix's narrative projects US$1.7b revenue and US$216.1 million earnings by 2029. This assumes 14.4% yearly revenue growth and an earnings increase of about 4.7 times from US$45.8 million today.
Uncover how Calix's fair value indicates a 77% potential upside to its current price before sentiment around that gap shifts.
Exploring Other Perspectives
One alternate view on Calix leans heavily on governance risk. The most cautious analysts worry shareholder investigations could add costs and distraction, even while they were still forecasting about US$1.7b of revenue and roughly US$212.8 million of earnings by 2029. That is a much more restrained story, and it shows how sharply opinions can differ. Use this mixed Q3 report as a fresh data point, and compare several narratives before you decide what feels reasonable for you.
Explore 4 other Calix fair value estimates, including one that suggests it could be worth just $57.67!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Calix research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Calix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Calix's overall financial health at a glance.
Looking for more investment ideas beyond Calix?
If the Calix story has sharpened your thinking about earnings quality, balance sheets and long term potential, use that same lens across a wider watchlist with the Simply Wall St Screener.
- If you care most about financial resilience and low volatility, start with a 30 resilient stocks with low risk scores that can help you focus on durability over drama.
- If dependable income is higher on your list, scan a curated set of 6 dividend fortresses that put cash returns to shareholders front and center.
- If you want to cast a wider net for future opportunities, broaden your hunt with a 19 high quality undiscovered gems that filters for quality metrics the market may be underestimating.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com