


- Neurocrine Biosciences reported new survey and Phase 4 KINECT PRO data indicating that adults with tardive dyskinesia taking INGREZZA experienced fewer work and school disruptions and broad quality of life gains across multiple Tardive Dyskinesia Impact Scale domains.
- The findings highlight that INGREZZA’s patient reported benefits span both physical and socio emotional areas, using a validated scale that directly captures treatment impact on daily function and independence.
- We will look at how Neurocrine Biosciences' investment narrative is affected by these INGREZZA quality of life outcomes and patient reported gains.
Neurocrine Biosciences Investment Narrative Recap
To own Neurocrine Biosciences, you need to believe INGREZZA can keep pulling its weight while newer franchises and late stage CNS assets mature, in line with the analyst consensus Narrative on Simply Wall St. The new quality of life data supports INGREZZA’s clinical story, but does not change near term pressure from Medicare pricing, VYKAT XR safety scrutiny or the importance of 2027 psychiatry readouts.
Right now, the most important near term swing factor is how well Neurocrine Biosciences manages INGREZZA volume against a 4% 2026 price headwind and future rebate rules. The largest risk remains that late stage psychiatry and muscarinic trials underdeliver, which could leave earnings below what analysts currently model into 2029.
The INGREZZA survey and KINECT PRO updates line up closely with Neurocrine Biosciences’ third quarter 2026 results. Revenue for the quarter was US$1,122.7m, with net income of US$206.5m and diluted EPS of US$1.96 from continuing operations. Over nine months, revenue reached US$2,896.2m and net income US$548.8m, giving investors fresh evidence of how central INGREZZA is to the income statement today.
Those earnings underline why quality of life data matters. If physicians and patients see INGREZZA as improving daily functioning, that can support persistence and new starts, which helps when statutory pricing pressure and IRA related rebate changes begin to bite. Against that, investors still have to watch VYKAT XR’s regulatory overhang and execution risk on CRENESSITY and the psychiatry pipeline as key moving pieces.
Neurocrine Biosciences’ current earnings sit at US$705.5m, and analysts collectively point to US$1.3b in earnings on about US$5.1b of revenue by 2029, which reflects roughly 14.6% yearly revenue growth and an earnings increase of about US$594.5m from today’s level.
Uncover why Neurocrine Biosciences' fair value indicates a 19% potential upside to its current price that could narrow quickly.
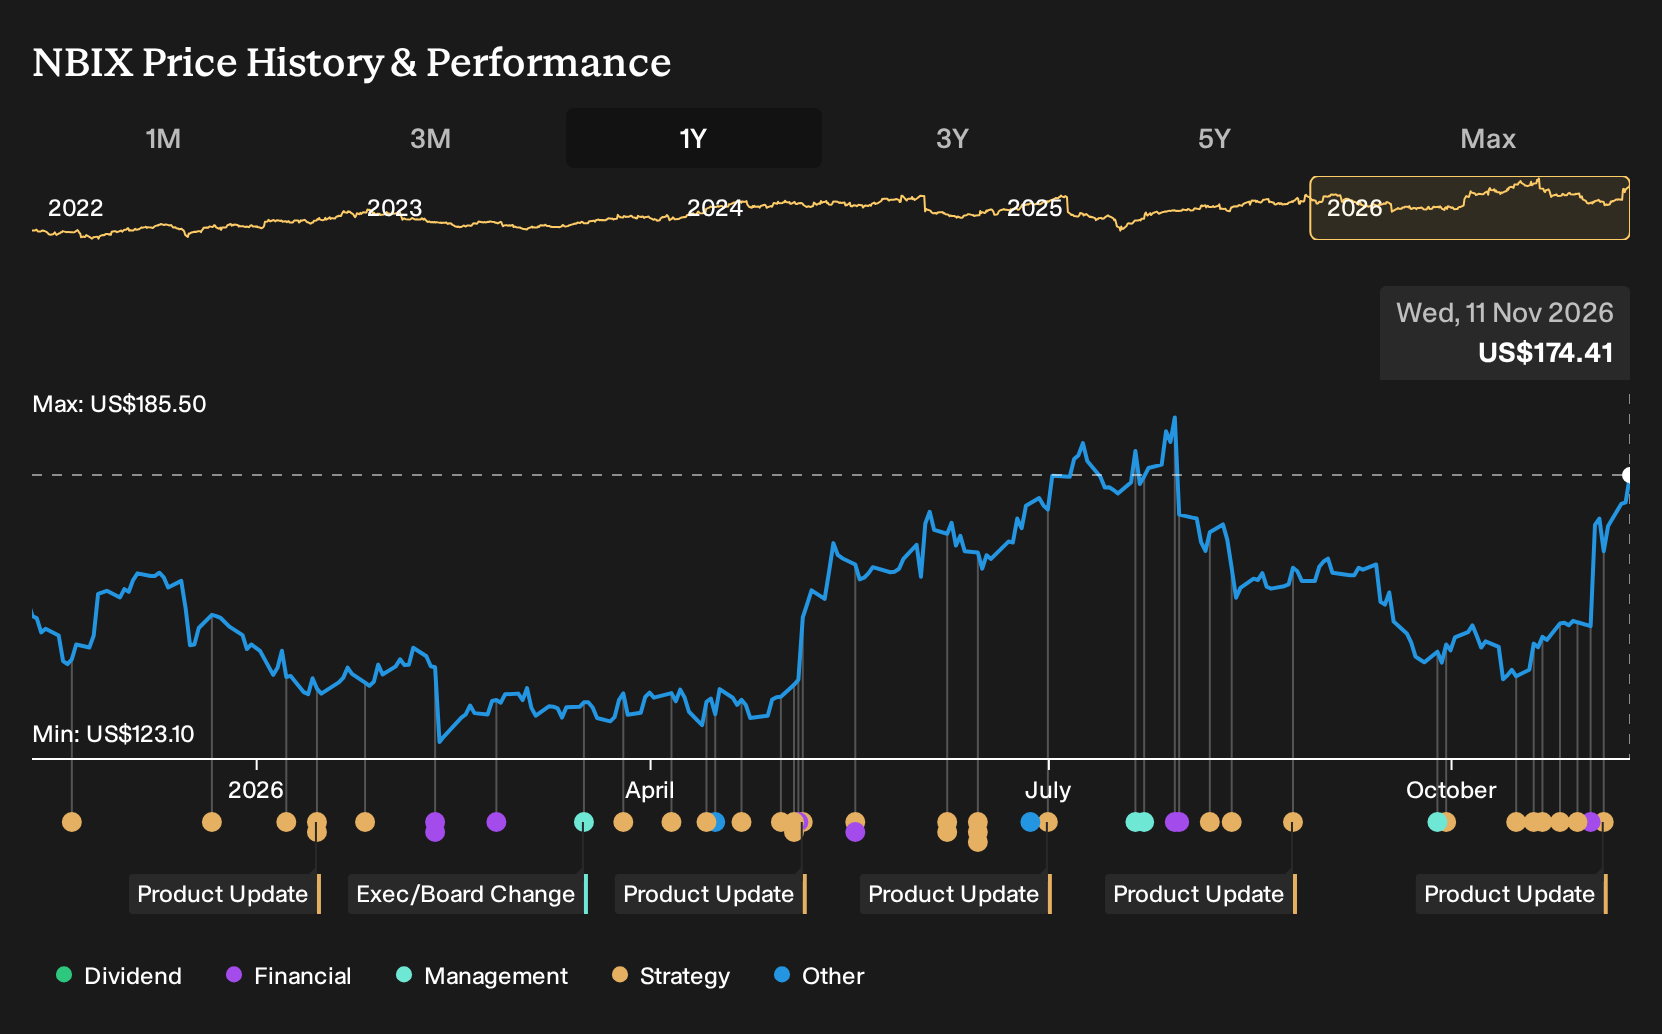
Exploring Other Perspectives
The most optimistic analysts frame INGREZZA’s quality of life story as fuel for much faster scaling of Neurocrine Biosciences. Before this news, the bullish group already pencilled in US$6.4b of revenue and US$2.4b of earnings by 2029. You can compare that to the US$5.1b and US$1.3b consensus view and decide which story feels closer to your own expectations, knowing both figures were set before these new patient reported outcomes landed.
Explore 3 other Neurocrine Biosciences fair value estimates, including one that suggests potential upside of up to 212% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Neurocrine Biosciences research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Neurocrine Biosciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review Neurocrine Biosciences' overall financial health at a glance.
Looking for more Neurocrine Biosciences sized ideas?
If the Neurocrine Biosciences story has sharpened your thinking about risk, balance sheets and future earnings power, it can help to line it up against other potential opportunities using a consistent framework.
- If capital preservation sits high on your list, scan a curated set of companies with steadier profiles through the 30 resilient stocks with low risk scores to see which ones match your comfort level.
- For investors who care most about financial resilience and clean fundamentals, compare Neurocrine Biosciences with a broader list of solid balance sheet and fundamentals (24 results) and see which businesses hold up best under deeper scrutiny.
- If you prefer situations that the wider market may not be paying close attention to yet, broaden your watchlist through a focused 19 high quality undiscovered gems that surfaces underfollowed stocks with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com