


Zymeworks (ZYME) reported a sharp swing into profitability following a large milestone payment from Jazz Pharmaceuticals tied to FDA approval of Ziihera, and management raised full year 2026 revenue guidance.
Despite the sharp move into profit, Zymeworks’ share price has been choppy, with a 1-day share price return down 7.6% and a 7-day share price return down 6.0%, even as the 30-day and 90-day share price returns of 14.8% and 12.9% suggest momentum has been building in recent weeks. At the same time, the 1-year total shareholder return of 50.1% and 3-year total shareholder return of about 2.8x point to a much stronger longer term payoff for investors who stayed through earlier volatility, while the latest earnings and guidance shift the discussion toward how repeatable these milestone driven gains might be.
Scan how Zymeworks compares to other biotech names pricing in big milestone swings by reviewing our curated list of 19 high quality undiscovered gems.The latest swing around Zymeworks now raises a sharper question. Are investors reassessing the underlying earnings power, or are they just reacting to a milestone headline that may not recur on the same scale?
Most Popular Narrative: 30% Undervalued
On the analyst consensus Narrative on Simply Wall St, Zymeworks screens as undervalued, with a fair value of $41.50 against a last close of $29.07. This puts the recent milestone driven jump into a broader royalty and cash flow story.
The key requirement is that Zymeworks successfully converts its partnered pipeline and platforms into durable, high-margin royalty streams and cash flows that can cover lower internal R&D spend and support ongoing non-dilutive financing and buybacks.
See why 9 investors see Zymeworks as 30% undervalued.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the Zymeworks narrative depends heavily on partner execution for Ziihera and ZW209, and on royalty backed debt not constraining future cash returns to shareholders.
Find out about the key risks to this Zymeworks narrative.
Another View: Zymeworks Looks Expensive On Earnings
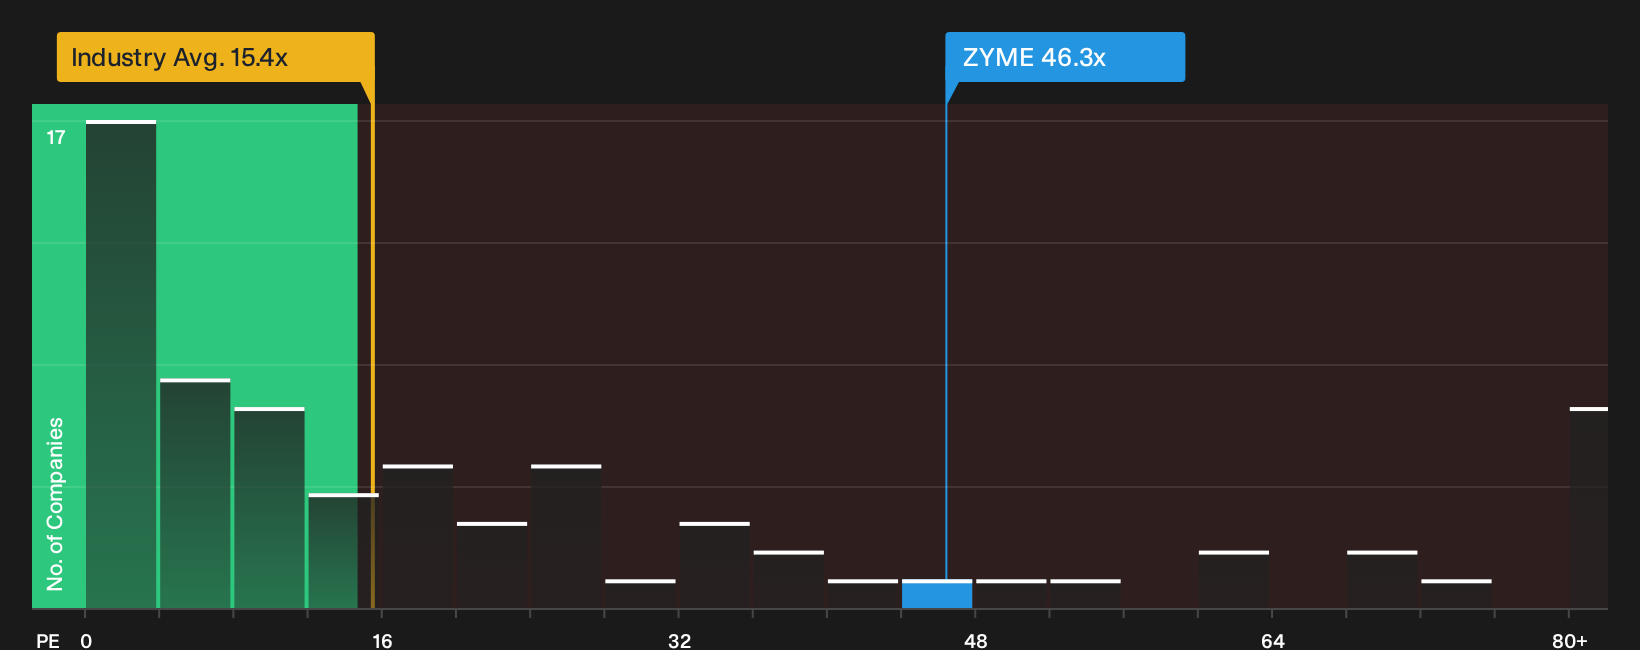
The DCF output points to Zymeworks trading well below an estimate of future cash flow value, yet the P/E ratio of 46.3x paints a very different picture. That multiple is roughly 3x the US Biotechs industry at 15.4x and sharply above the 6.7x peer average, while also more than double the 19.9x fair ratio. For anyone weighing position size, consider how comfortable you are if the market moves closer to that fair ratio instead.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the crosscurrents in this Zymeworks story feel mixed, that is exactly why the data matters. Act quickly, review both sides, and ground your stance in our breakdown of 3 key rewards and 1 important warning sign.
Looking for more Zymeworks sized opportunities?
Do not stop at Zymeworks. Broaden your watchlist with ideas that match your style, whether you focus on value, resilience, income or early stage growth potential.
- Pinpoint potential bargains with solid fundamentals before they get crowded by scanning our 32 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by filtering for companies in the 30 resilient stocks with low risk scores.
- Stack potential income on top of price returns by zeroing in on our 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com