


- Kokuyo reported earnings for the nine months ended 30 September 2026, with sales of ¥290,174 million, net income of ¥18,068 million, and basic earnings per share from continuing operations of ¥42.62.
- The margin between Kokuyo's sales and net income for the period suggests that cost control and pricing power remain central to the business story.
- The next point of interest is how Kokuyo's higher nine month sales figure interacts with the broader investment narrative around the stock.
Compare Kokuyo's latest nine month performance with other companies that pair solid earnings with balance sheet strength by scanning our curated list of solid balance sheet and fundamentals (23 results) today.
What Is Kokuyo's Investment Narrative?
Owning Kokuyo stock means buying into a fairly grounded story. This is a mature office furniture and stationery group that lives or dies on execution, cost discipline and steady demand for everyday work tools. The latest nine month results, with ¥290,174 million in sales and ¥18,068 million in net income, support a picture of a business that can still convert revenue into profit, even as net profit margins sit just under 6% and a touch lower than last year.
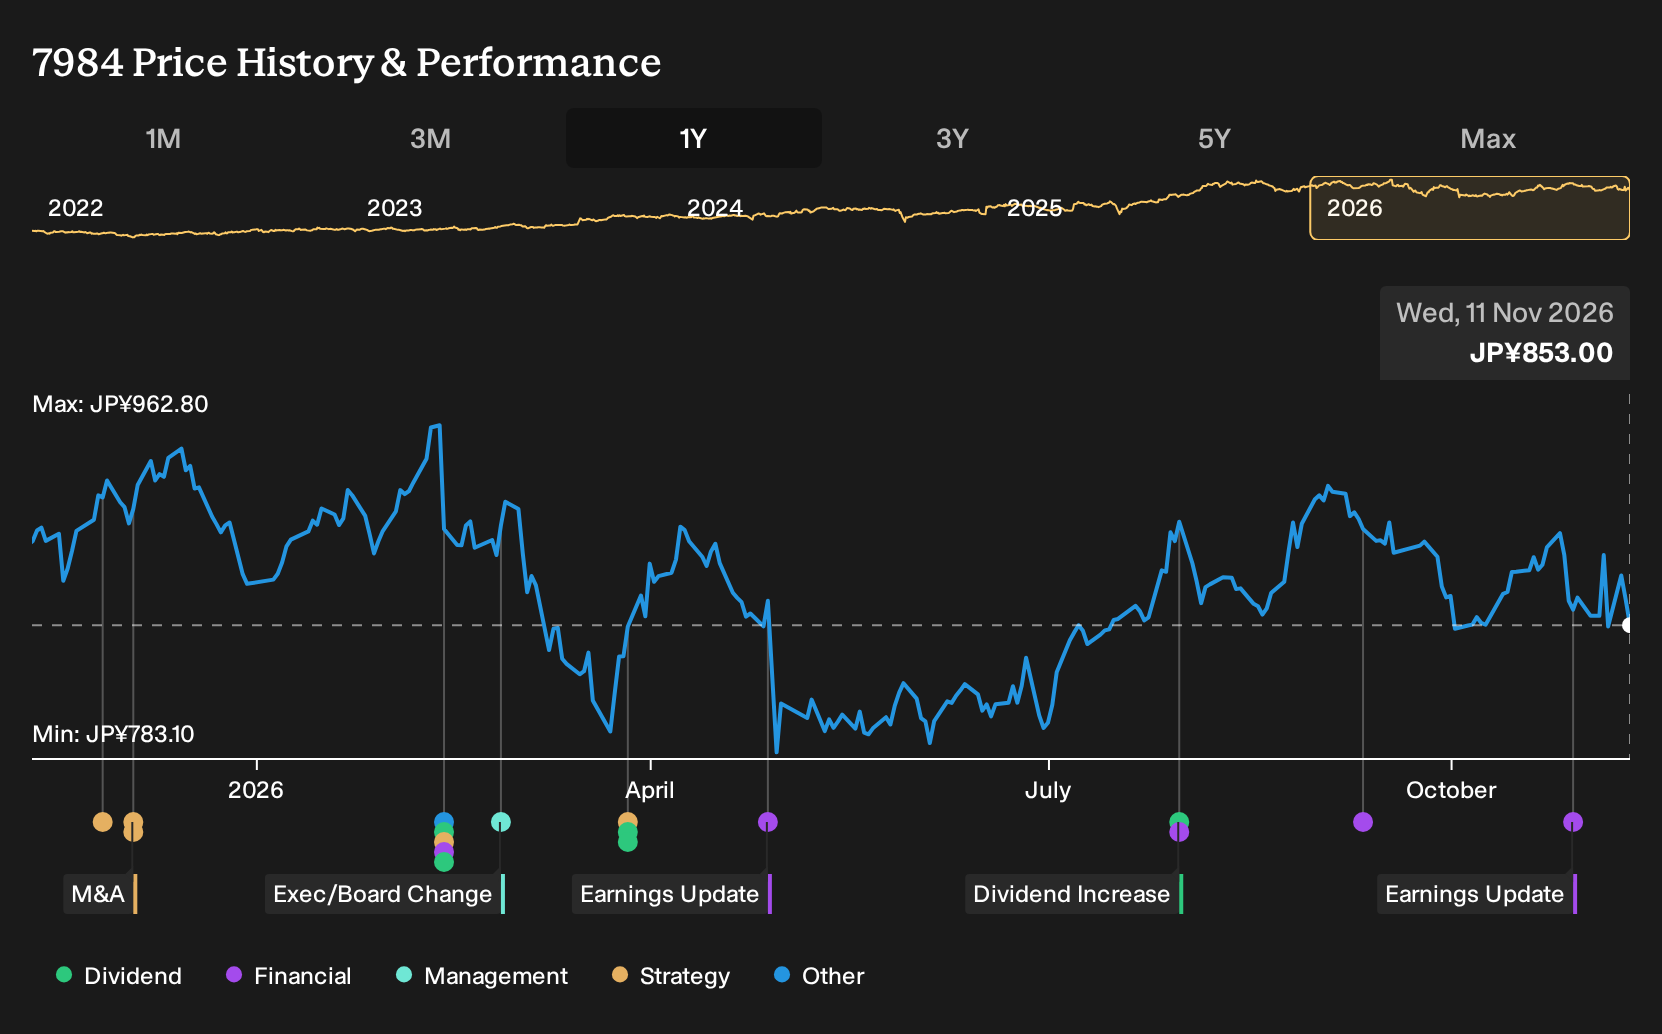
In the short term, the key questions are whether Kokuyo can keep pricing firm in office and Campus branded stationery, and whether any mix shift or input cost pressure squeezes those margins further. Forecasts that point to mid single digit annual earnings and revenue growth, along with cash flow based valuation signals that appear reasonable, indicate that this update is directionally consistent with the existing thesis rather than thesis changing. The softer share price over the past year indicates that the market wants clearer proof on execution.
Yet there is one area of Kokuyo's financial profile that could quietly reshape the risk reward balance if...
There's only one way to know the right time to buy, sell or hold Kokuyo. Head to Simply Wall St's company report for the latest analysis of Kokuyo's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kokuyo research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kokuyo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kokuyo's overall financial health at a glance.
Looking For More Ideas Beyond Kokuyo?
If Kokuyo's latest update has sharpened your focus on quality and risk, it can be useful to widen the lens and compare it with other listed businesses that share similar strengths. The Simply Wall St Screener lets you filter for the traits you care about most, whether that is value, balance sheet resilience or income potential, so you can build a watchlist that actually matches your approach.
- For investors who want a mix of quality and value, start with companies that pair strong fundamentals with pricing that still looks reasonable through the 24 high quality undervalued stocks.
- If capital preservation matters most to you, focus on businesses with sturdier finances and lower risk profiles by running a search using the 19 resilient stocks with low risk scores.
- Those hunting for income ideas can zero in on higher yielding opportunities with healthier payout support by reviewing the 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com