


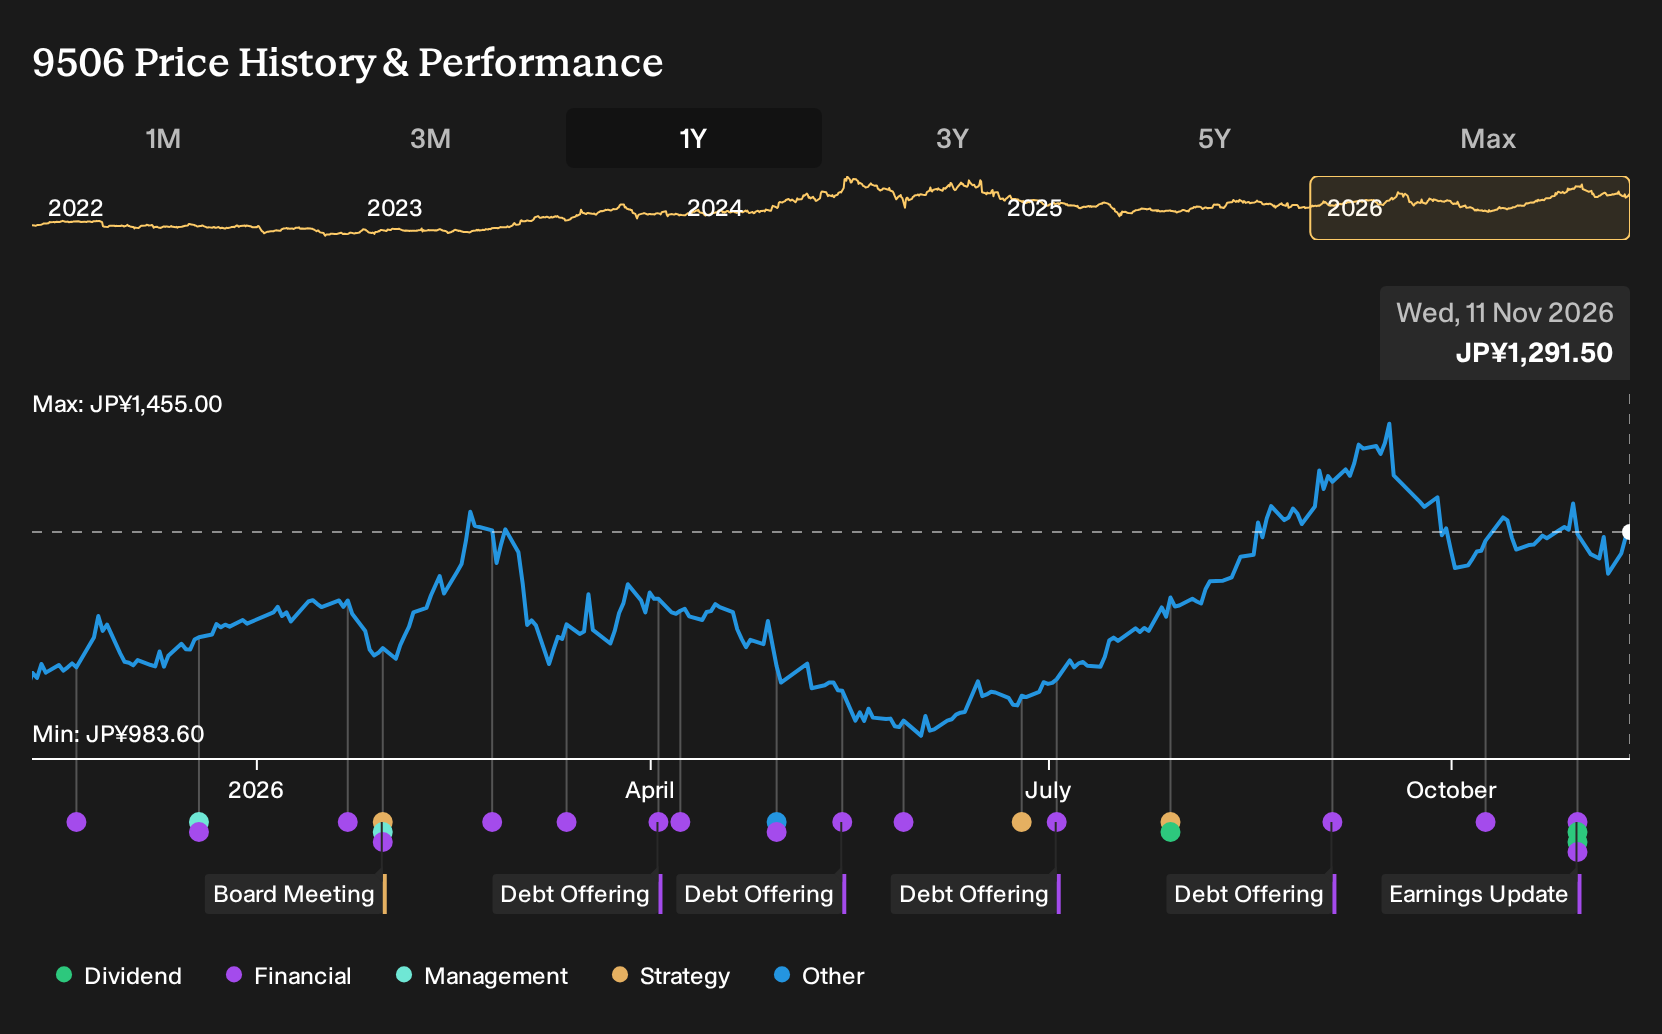
- Tohoku Electric Power Company reported half year results to 30 September 2026, issued its first full year earnings forecast under the new revenue cap framework, and outlined updated dividend plans including a higher full year payout target.
- The combination of clearer earnings guidance tied to approved wheeling revenue forecasts and a dividend uplift indicates that management is prioritising both income stability for shareholders and rebuilding the balance sheet under the DOE policy.
- The focus now is on how Tohoku Electric Power Company's clearer full year guidance reshapes the broader investment narrative for the business.
Scan how Tohoku Electric Power Company’s clearer guidance and dividend plans compare with other regulated utilities by running the hand picked 42 power grid technology and infrastructure stocks
What Is Tohoku Electric Power Company's Investment Narrative?
To stay invested in Tohoku Electric Power Company, you need to believe that a regulated, capital intensive grid and generation business can turn clearer pricing rules into steadier returns while managing heavy funding needs. The new full year forecast under the revenue cap system, together with the higher annual dividend target of ¥42 per share, points to management leaning into that story of more predictable income and gradual balance sheet repair rather than aggressive expansion.
The half year numbers underline the tension. Revenue for the period to 30 September 2026 reached ¥1,727,546 million, yet net income fell to ¥29,770 million and margins remain thin, with interest costs flagged as a pressure point. The updated guidance that assumes revised electricity rates and fuel cost pass through now becomes the key short term catalyst, because it gives you a yardstick to judge execution on pricing, cash generation and dividend coverage against already tight interest and free cash flow metrics.
Even so, there is a less comfortable angle to this earnings and dividend story that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold Tohoku Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Tohoku Electric Power Company's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tohoku Electric Power Company research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tohoku Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tohoku Electric Power Company's overall financial health at a glance.
Looking For More Ideas Beyond Tohoku Electric Power Company?
If you want to cross check Tohoku Electric Power Company against other opportunities, use the Simply Wall St Screener to build a short list of stocks that better match your income needs, risk comfort, and valuation preferences.
- If income resilience is your priority, scan a curated set of higher yielding companies described as 29 dividend fortresses that may fit a dividend focused approach.
- If capital protection matters more than upside stories, filter for companies in the 19 resilient stocks with low risk scores that score well on Simply Wall St's risk checks.
- If you want to cast a wider net for potential mispriced opportunities, the 72 high quality undiscovered gems can help surface ideas that combine stronger fundamentals with relatively low attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com