


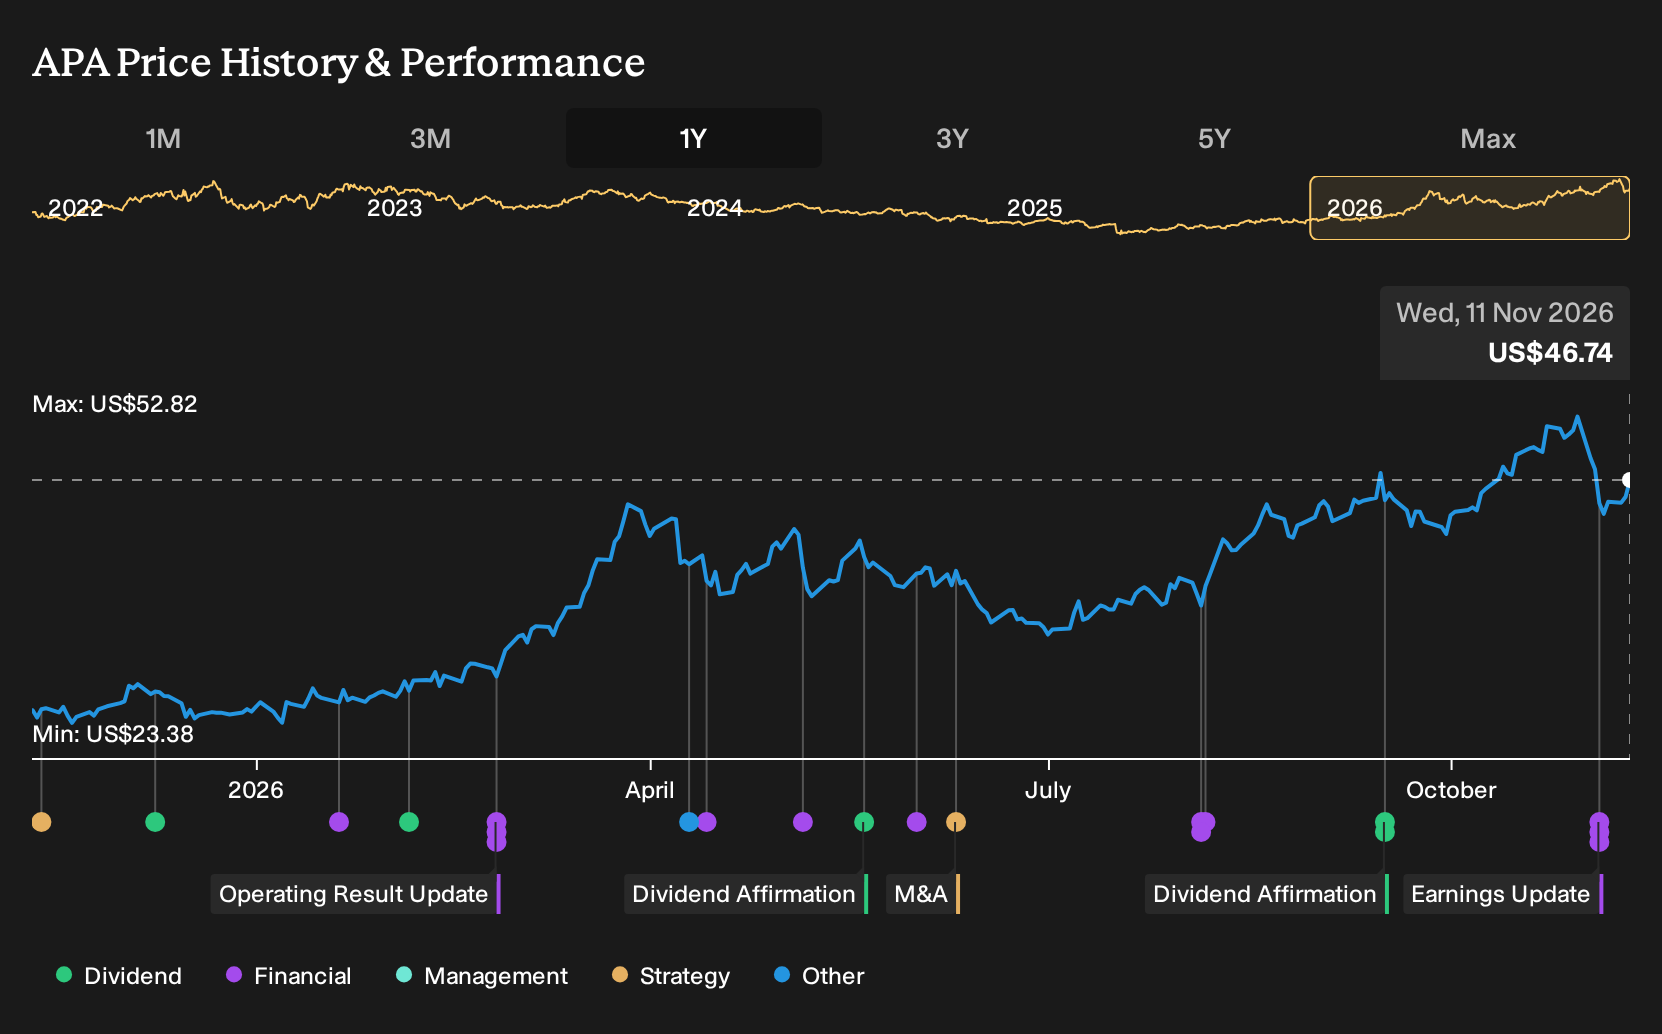
- APA Corporation reported third quarter 2026 revenue of US$2,812 million and net income of US$698 million, with U.S. oil and total production metrics exceeding prior guidance.
- The company increased its 2026 U.S. oil production guidance to 124,000 barrels per day, as drilling and completion efficiency gains in the Permian improved capital productivity.
- We will now look at how APA's investment narrative could be affected by stronger quarterly earnings and raised U.S. oil guidance.
Scan how APA's third quarter beat and higher U.S. oil guidance compare with other potential breakouts by checking our hand picked 32 high quality undervalued stocks in similar sectors.
APA Investment Narrative Recap
To own APA, you need to believe the business can keep turning its low cost, multi basin portfolio into steady cash flows while managing a world that is gradually tightening around hydrocarbons. The third quarter beat helps that story in the short run by showing higher revenue, stronger net income and U.S. oil production running ahead of guidance.
The key near term catalyst is execution on capital efficiency, especially in the Permian, so the raised U.S. oil guidance to 124,000 barrels per day directly supports it. The biggest risk still sits outside the quarterly print, with policy driven decarbonization and weaker gas pricing both capable of pressuring future volumes and earnings.
The operating guidance update around U.S. oil volumes looks most relevant here. Management now expects full year U.S. oil production of 124,000 barrels per day, above the initial 120,000 to 122,000 range, supported by faster drilling and completion efficiency in the Permian and a modest US$30 million capital increase this year.
For you, that guidance touches several catalysts in the analyst consensus Narrative on Simply Wall St, particularly the focus on cost savings and capital discipline while sustaining oil output. It also interacts with the risk side. Higher oil volumes do not offset exposure to gas price weakness or long term decarbonization policies, so execution on both cost and portfolio mix remains central.
APA's narrative projects US$8.0 billion revenue and US$1.7 billion earnings by 2029. This reflects analysts assuming revenue will decrease by 2.1% per year and earnings will remain around US$1.7 billion, in line with earnings today of US$1.7 billion.
Uncover how APA's fair value indicates a 5% potential upside to its current price before the gap to APA closes.
Exploring Other Perspectives
One alternate angle on APA zooms in on the gas trading and transport portfolio. Bullish analysts had been banking on about US$950 million pretax cash flow in 2026 and US$400 million in 2027, helping support revenue of roughly US$9.2b and earnings near US$1.8b by 2029. Those views were set before this earnings beat, so you may see some narratives shift as analysts reassess the role of U.S. oil performance versus that gas exposure.
Explore 4 other APA fair value estimates, including one that suggests up to 92% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your APA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for APA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate APA's overall financial health at a glance.
Looking for more APA investment ideas?
If APA has sharpened your focus on energy exposure and cash flow quality, the next step is to widen your watchlist with stocks that fit different risk and balance sheet profiles using the Simply Wall St Screener.
- For steadier profiles and less volatile journeys, filter companies with resilient finances through the 30 resilient stocks with low risk scores.
- If capital preservation and debt discipline matter most to you, narrow the field to businesses on our list of solid balance sheet and fundamentals (24 results).
- When you want to hunt for under followed opportunities with strong underlying metrics, scan the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com