


Netlist (NLST) has just put up a quarter that changes the conversation, with Q3 revenue at US$105.1 million, net income of US$85.45 million, and fresh licensing deals with Samsung and Micron.
Netlist’s share price has cooled in the very short term, with a 1-day share price return that declined 6.84%, even though the 90-day share price return is up 20.77% and the year-to-date share price gain is a sharp 504.14%. This hints that recent momentum remains strong despite some profit taking around the earnings release and licensing headlines. Over a longer window the picture is even more dramatic, with a 1-year total shareholder return of about 9x and a 3-year total shareholder return of just over 3x, while the 5-year total shareholder return is slightly negative. This indicates that the story has only really changed gear in the recent past.
Track how Netlist fits into the wider AI hardware story by scanning a curated set of 53 AI infrastructure stocks that could be riding similar demand for data center build outs.
The business story around Netlist looks much stronger after this quarter, yet the stock already reflects a huge reset in expectations. So does today’s US$5.99 share price still leave enough value on the table?
Preferred P/E of 24.3x for Netlist: Is it justified?
On the numbers given, Netlist looks inexpensive on earnings next to peers, even after a share price that has already re-rated very hard in 2026. The stock last closed at $5.99 and sits on a P/E of 24.3x, while the peer group trades on 42.7x and the wider US Electronic industry sits at 26x.
The P/E ratio compares a company’s share price to its per share earnings. For a hardware and components player like Netlist, this lens helps you see what investors are paying today for each dollar of profit that the business currently produces.
With Netlist at 24.3x, the market is assigning a lower earnings tag than both the industry average and its direct comparison set, even though the firm has just moved into profitability and reports a 59% return on equity. That combination suggests that expectations for future profitability might be more cautious than the recent income statement or the fresh licensing agreements with Samsung and Micron might indicate.
In contrast, the SWS DCF model presents a much more aggressive picture of value. On this view, Netlist’s estimate of future cash flow value is $119.26 per share, which is well above the current $5.99 price and indicates a very wide gap between what the cash flow model suggests and where the market is actually trading.
See what the numbers say about this price in the full valuation breakdown by checking the See what the numbers say about this price — find out in our valuation breakdown..
Result: Price-to-earnings of 24.3x (UNDERVALUED)
Still, Netlist’s recent shift into profitability leans heavily on licensing, and any cooling in data center demand or partner activity could quickly challenge this new earnings profile.
Find out about the key risks to this Netlist narrative.
Another view on Netlist’s value
The P/E comparison paints Netlist as relatively cheap, yet the SWS DCF model goes much further and assigns a future cash flow value of $119.26 per share versus the current $5.99. That gap signals a very different risk reward profile. Which lens do you trust more when real cash is on the line?
To see how that cash flow view is built and stress test the inputs for yourself, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
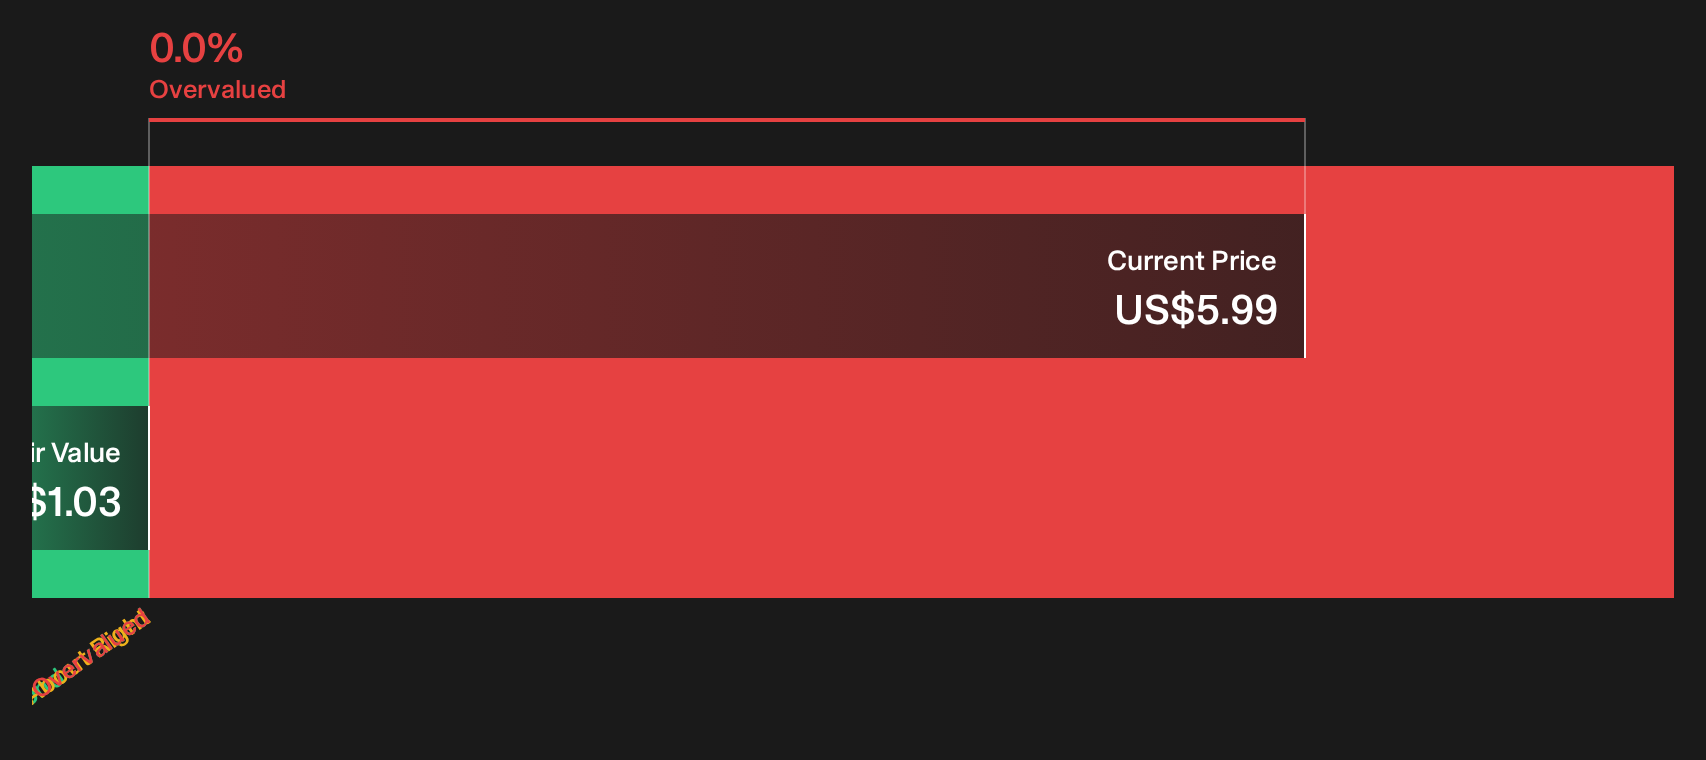
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Netlist for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The numbers and mixed sentiment around Netlist set the stage, but your own judgment matters most, especially with both risks and upsides flagged. Act while the story is still fresh by weighing the 3 key rewards and 3 important warning signs.
Looking for more Netlist-sized ideas?
If Netlist has you rethinking what is possible in this corner of the market, do not stop here. Use the tools available and keep building a stronger watchlist.
- Hunt for underappreciated quality by checking companies in the 32 high quality undervalued stocks that pair healthier fundamentals with more modest expectations.
- Prioritise resilience first and return potential second by reviewing the 30 resilient stocks with low risk scores that score well on financial stability and volatility metrics.
- Target sturdier balance sheets by scanning the list of solid balance sheet and fundamentals (23 results) so you are not relying solely on story driven stocks when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com