


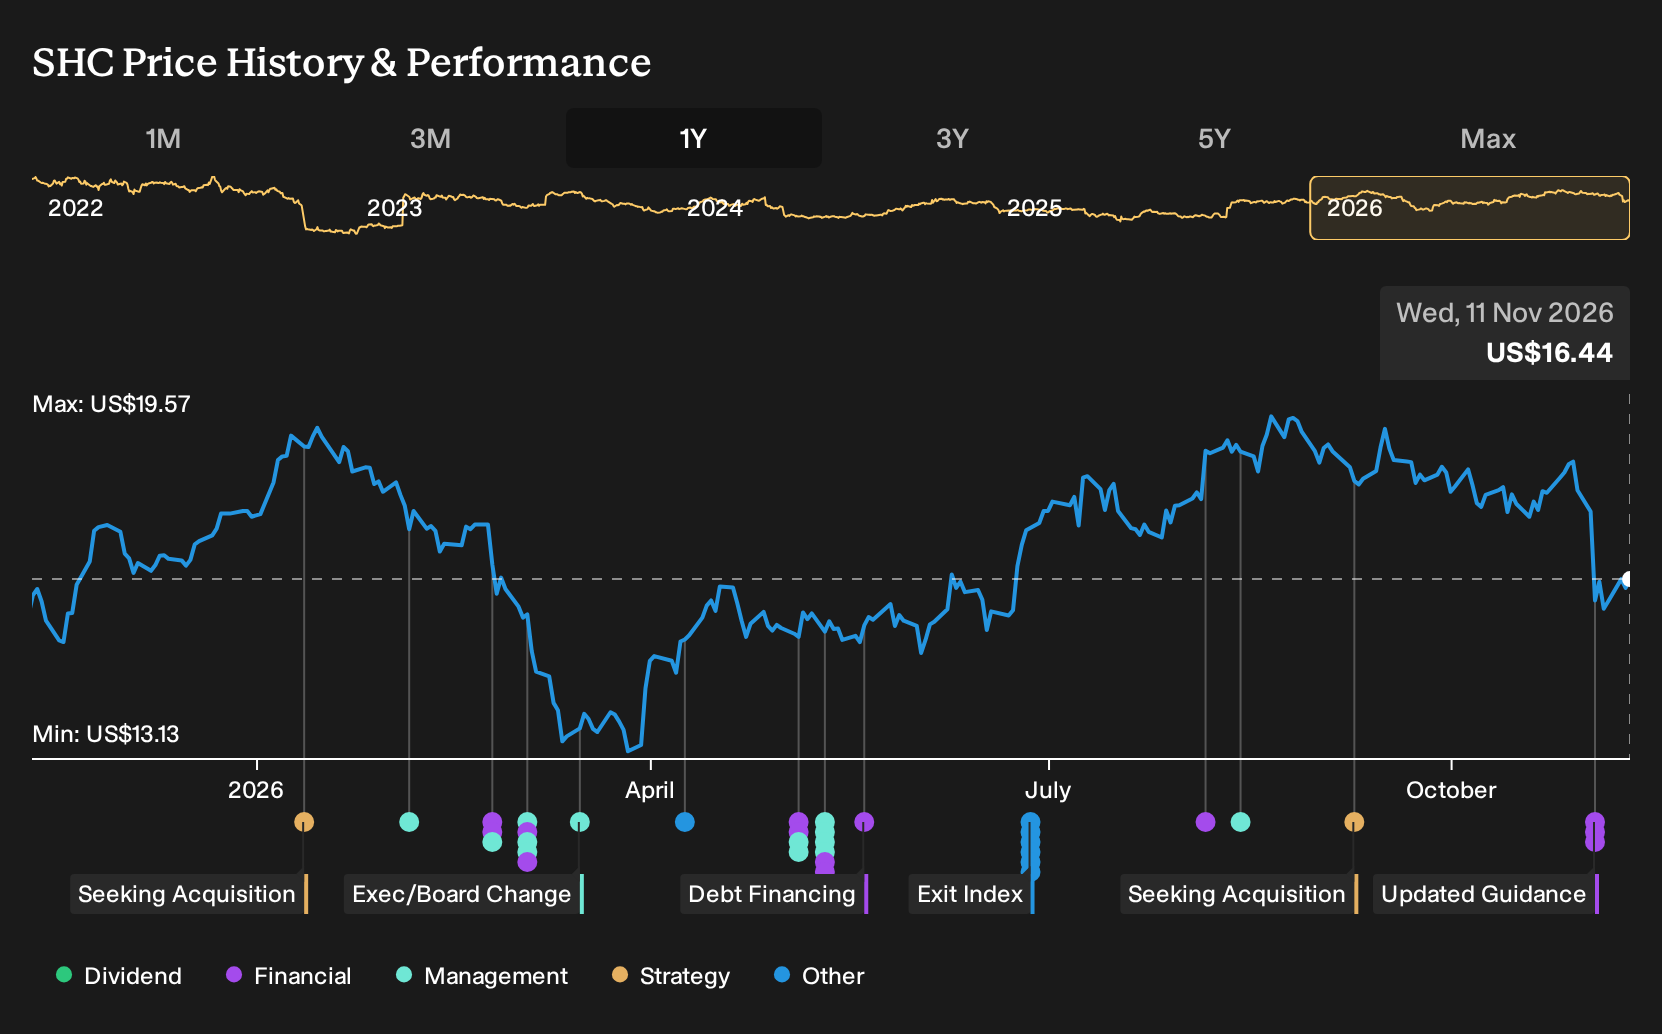
- Sotera Health reported third quarter 2026 revenue of US$324.89 million and net income of US$58.39 million, and reaffirmed full year guidance for net revenues of US$1.233b to US$1.250b along with an outlook for approximately 6% constant currency revenue growth in the fourth quarter.
- The latest results show higher basic and diluted earnings per share from continuing operations for both the quarter and year to date compared with the prior year period. This provides investors with more detail on how Sotera Health is translating its sterilization, testing and advisory operations into profitability.
- Attention now turns to how Sotera Health's reaffirmed 2026 revenue range might reshape the existing investment narrative built around capacity expansion.
Scan how Sotera Health's reaffirmed outlook compares with other potential compounders by reviewing our hand picked list of 32 high quality undervalued stocks that combine earnings power with balance sheet support.
Sotera Health Investment Narrative Recap
To hold Sotera Health, you need to be comfortable with a business that leans heavily on outsourced sterilization and lab services and is investing significantly in emissions controls and new capacity. The reaffirmed 2026 revenue range and 6% constant currency growth outlook for the fourth quarter support the idea that current projects remain on track. The short term swing factor still appears to be how quickly those new facilities and EtO upgrades translate into usable throughput.
The biggest risk remains outside the income statement. Ethylene oxide litigation and regulatory scrutiny can still alter permitted volumes or increase operating and compliance costs. Capital expenditure running at a high watermark of US$200 million to US$225 million in 2026 also keeps pressure on free cash flow. The latest guidance does not remove those issues, but it does indicate no immediate deterioration in the operating trajectory.
The most relevant update is Sotera Health reaffirming full year 2026 net revenue guidance of US$1.233b to US$1.250b, with constant currency growth of 5.25% to 6.75%. That range aligns with what the analyst consensus narrative on Simply Wall St already describes as a capacity and margin story built on heavy 2026 spending that is expected to support earnings power over time.
Regarding potential catalysts, the confirmed outlook keeps attention on execution rather than a reset. Investors can focus on whether Sterigenics, Nordion and Nelson Labs sustain pricing and mix, and whether EtO investments and cobalt development remain within the guided budget. If those elements stay aligned with guidance, it becomes easier to assess how leverage, free cash flow and potential margin expansion might evolve from here.
Sotera Health's narrative projects US$1.4b revenue and US$328.8 million earnings by 2029. This assumes 5.6% yearly revenue growth and an earnings increase of about US$155 million from current earnings of US$173.5 million.
Uncover why Sotera Health's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Sotera Health’s cash generation after EO upgrades taper, rather than on current capital intensity. Before this guidance, the bullish group was pencilling in revenue of about US$1.5b and earnings of roughly US$370.2 million by 2029. Those expectations may shift, so treat today’s update as one input and compare several viewpoints.
Explore another Sotera Health fair value estimate, including one that suggests as much as 140% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Sotera Health research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sotera Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sotera Health's overall financial health at a glance.
Looking For More Ideas Beyond Sotera Health?
If Sotera Health fits your checklist but you want a wider watchlist, use this update as a springboard to scan other businesses with different risk and return profiles. The Simply Wall St Screener can help you line up candidates that match your priorities, whether you care more about valuation, resilience or balance sheet strength.
- If you want a wider pool of potential bargains with strong fundamentals, review our hand picked 19 high quality undiscovered gems that might not yet be crowded with attention.
- If capital preservation comes first for you, narrow the field to companies that score well on stability by checking out our 30 resilient stocks with low risk scores.
- If you care most about financial resilience, start with businesses supported by robust balance sheets using our focused list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com