


NKT (CPSE:NKT) has secured three framework agreements with Danish grid operator N1 for low and medium voltage power cables, introducing multi year contract visibility and fresh attention on the stock.
The fresh N1 contracts land at a time when NKT’s share price has shown mixed momentum, with a 7 day share price return of 6.12% and a year to date share price gain of 7.40%. However, the 90 day share price return is down 7.81%, suggesting enthusiasm has cooled recently, even as the 1 year total shareholder return of 25.00% points to stronger gains for longer term holders.
Scan cable and power grid peers showing similar contract momentum with our hand picked 42 power grid technology and infrastructure stocks for comparison against NKT.
NKT now sits on fresh grid contracts and a share price that has already moved this year. Should you lean into the momentum or wait for a cheaper entry before the valuation work starts?
Most Popular Narrative: 10% Undervalued
NKT closed at DKK885, while the analyst consensus Narrative on Simply Wall St points to a fair value of DKK988.58 based on its long term cash flow potential and project pipeline. That gap puts fresh focus on how well the grid cable story can translate into future earnings and cash generation.
The main priority is that NKT executes its €2b capex program and brings new HV and MV capacity, vessels and accessories fully onstream without eroding the healthy margins seen in recent projects.
The current valuation implies the market is cautious on whether NKT’s multidecade grid investment tailwind and guided step up in EBITDA and ROCE are sustainable. This leaves room for upside if the company continues to deliver on its plans.
See why 30 investors see NKT as 10% undervalued.
Result: Fair Value of DKK988.58 (UNDERVALUED)
Still, the narrative can break if NKT’s heavy €2b capex drags on free cash flow for longer than planned, or if new capacity fails to support margins.
Find out about the key risks to this NKT narrative.
Another View: What NKT’s P/E Is Telling You
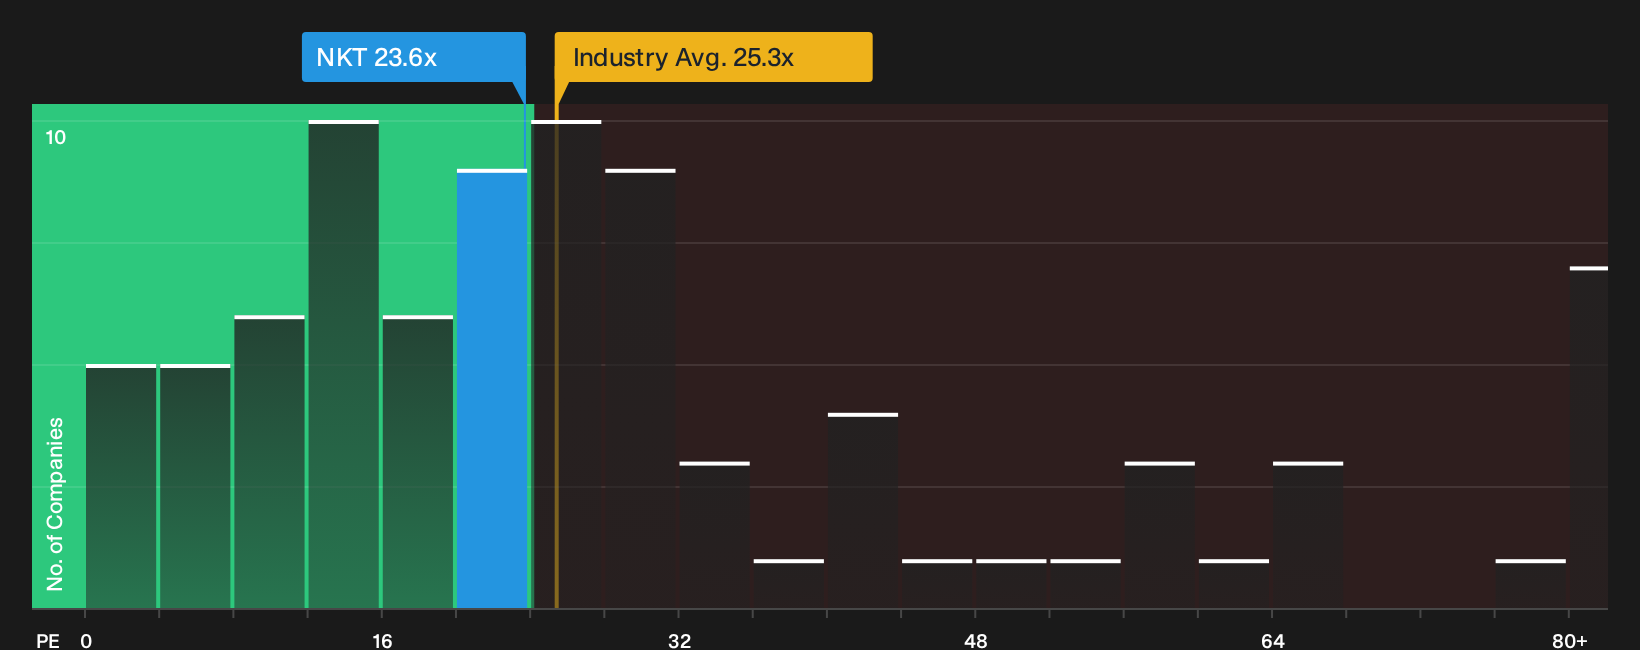
NKT looks cheap on a cash flow lens, with the SWS model indicating the DKK885 share price sits 46.2% below an estimate of future cash flow value at DKK1,645.63. Yet the stock trades on a P/E of 23.6x, above its own fair ratio of 21.4x and above peers at 16.8x. Is this a margin of safety or a sign expectations already run hot?
To see how this earnings multiple could evolve as sentiment shifts around NKT, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on NKT’s valuation and sentiment can cut both ways, so move quickly, access the full data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more NKT sized opportunities?
Do not stop at NKT. Use fresh ideas from the Simply Wall St screener to pressure test your portfolio and uncover companies that better match your risk and return goals.
- Target sturdier portfolios by filtering for companies with strong finances using the list of solid balance sheet and fundamentals (193 results).
- Hunt for mispriced quality by scanning the 196 high quality undervalued stocks before others catch on.
- Lock in steadier portfolio income by focusing on payouts through the 216 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com