


- SiTime reported third quarter 2026 sales of US$298.67 million and net income of US$4.35 million, with basic and diluted earnings per share from continuing operations of US$0.14, and nine month 2026 sales of US$569.67 million and net income of US$17.29 million.
- The shift from prior period losses to earnings over both the quarter and nine month period highlights a meaningful change in SiTime’s recent profitability profile and cost or mix management.
- We will now examine how SiTime’s move from prior losses to third quarter profitability could influence the broader investment narrative.
Scan other chip designers that have recently moved from losses to positive earnings and see how SiTime compares with a hand picked set of 19 high quality undiscovered gems
SiTime Investment Narrative Recap
For SiTime, the big picture belief is that demand for high precision timing in AI data centers, communications, and diversified end markets will keep supporting a larger business over time. The analyst consensus Narrative on Simply Wall St leans heavily on that trend and on SiTime’s ability to keep its gross and operating margins healthy. The recent move from losses to quarterly and year to date profitability reinforces that profit story, but it does not remove the execution risk around that thesis.
The key near term swing factor is still how well SiTime integrates the acquired Renesas timing assets while keeping margins and customer momentum intact. The largest current risk remains its exposure to Communications, Enterprise and Data Center demand. Any slowdown in AI projects, architectural change at hyperscalers, or insourcing of timing could matter more than one strong quarter of earnings.
The earnings report for the third quarter and nine months to 30 September 2026 is the clearest recent operational update to weigh against those catalysts. Revenue reached US$298.67 million for the quarter and US$569.67 million for the nine months, with both periods now profitable after prior losses. That shift to earnings gives SiTime more flexibility to keep funding R&D and integration work without relying only on balance sheet firepower.
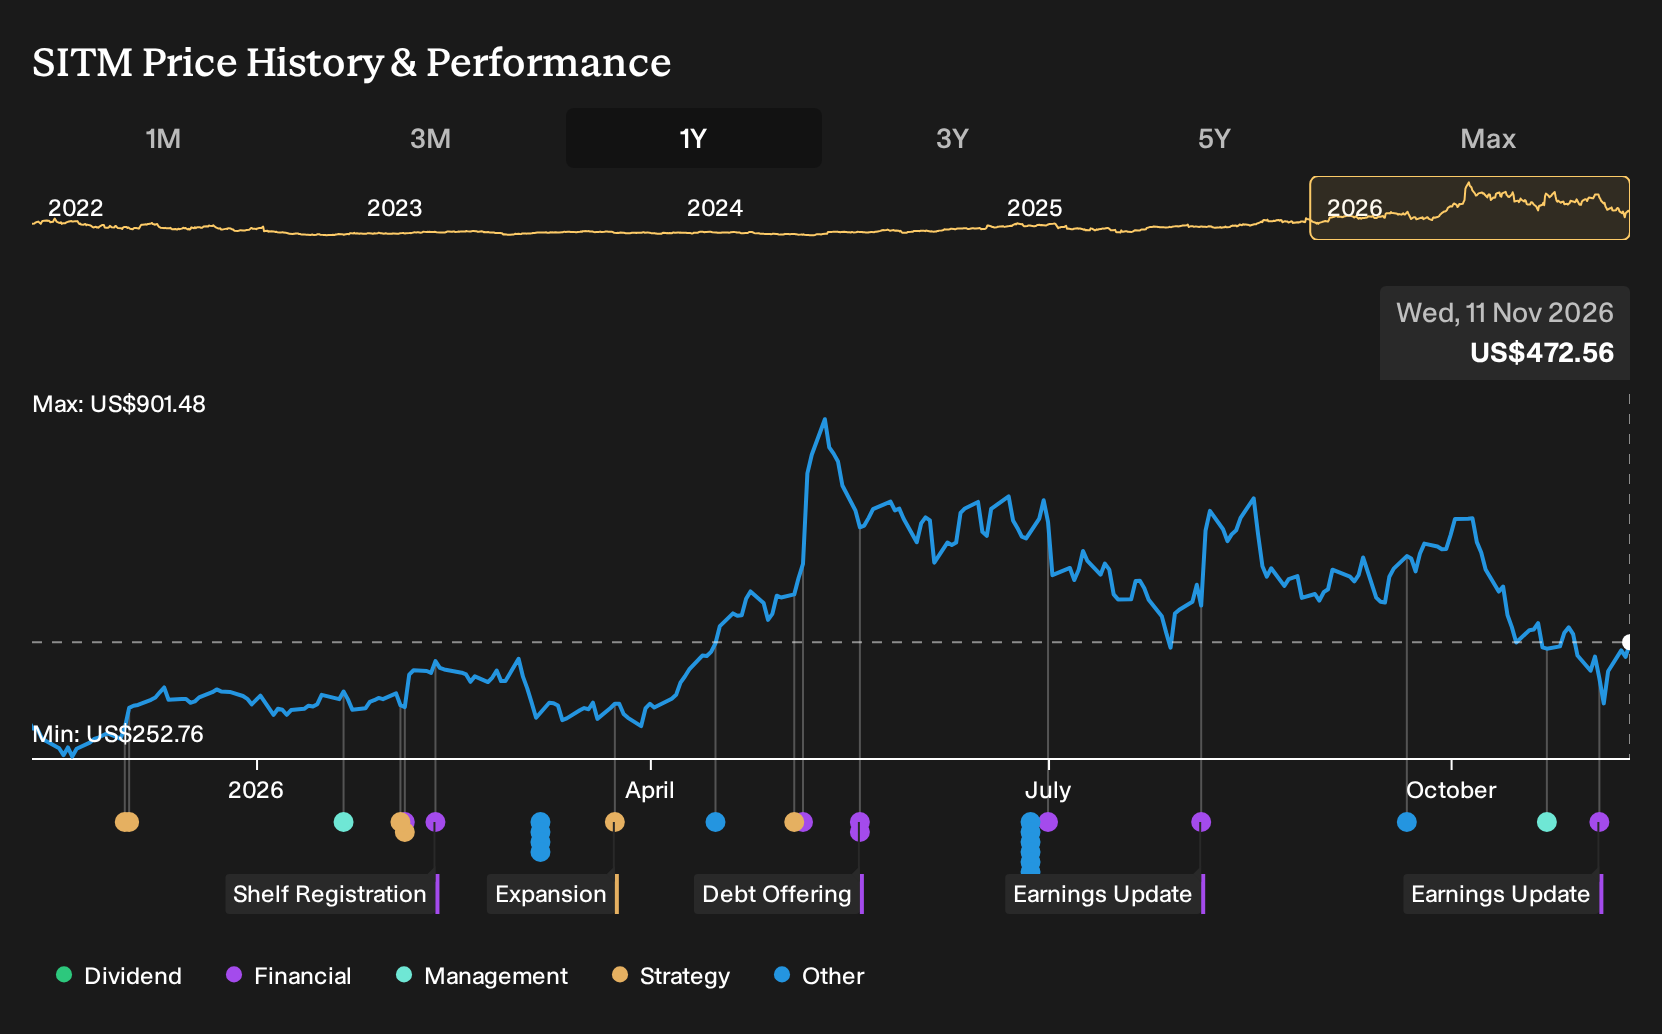
At the same time, leverage from the US$1.35b of 0% convertible notes used to fund the Renesas deal and concerns about dilution are still in focus. Heavy insider selling and a volatile share price add another layer of risk around execution missteps or weaker AI infrastructure demand. For a shareholder, the question is whether this profitability run rate and the wider timing portfolio offset those financing and concentration risks over the coming quarters.
What The Current SiTime Forecasts Assume
SiTime's narrative projects US$2.3b revenue and US$642.4 million earnings by 2029. This implies analysts are baking in 69.0% yearly revenue growth and an earnings increase of about US$628.3 million from US$14.1 million today.
Uncover why SiTime's fair value indicates a 76% potential upside to its current price, before the gap starts to close.
Exploring Other Perspectives
One alternate SiTime narrative leans hard on dilution risk from the US$1.35b convertible notes. Some more cautious analysts were modeling around US$2.1b of revenue and US$679.0 million of earnings by 2029 before this earnings release, yet they still saw enough pressure on future P/E and per share outcomes to stay wary. Their view shows how far opinions can differ, so it can help to compare several forecasts before deciding which story you find more convincing.
Explore 4 other SiTime fair value estimates, including one that suggests as much as 33% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SiTime research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for SiTime. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SiTime's overall financial health at a glance.
Looking for more SiTime style investment ideas?
Once you have formed a view on SiTime, it can help to line it up against other opportunities that share similar traits, whether you care most about value, resilience, or balance sheet strength. The Simply Wall St Screener is built for that kind of side by side work and can surface a focused set of stocks that match what you are actually looking for rather than just what is trending.
- If you want potential mispricing combined with solid fundamentals, start with a curated 32 high quality undervalued stocks that may warrant a closer look on your watchlist.
- For readers who prefer financial sturdiness and less fragile capital structures, filter for companies with strong finances using the list of solid balance sheet and fundamentals (23 results) to see which ones fit your risk tolerance.
- If capital preservation matters most and you want ideas with lower overall risk profiles, narrow the field by checking a focused 30 resilient stocks with low risk scores that can help you build a more defensive list of candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com