


FirstCash Holdings has delivered a powerful run over the past few years, yet the recent pullback and fresh legal questions now put its earnings under a sharper spotlight. With the stock changing hands around US$184, the key issue is whether that price can be grounded in the profit engine the business is currently generating.
- Over the past 5 years, FirstCash Holdings has returned about 186.3%. This raises the question of how much of that gain is supported by underlying earnings power rather than sentiment alone.
- Law firm Bronstein, Gewirtz & Grossman announced an investigation after a reported hit to operating income and gross transaction volume in the American First Finance segment. This can influence how investors think about the durability and risk profile of future profits.
- The analysts covering FirstCash Holdings have run their own numbers. See what analysts think FirstCash Holdings's shares could be worth.
The issue now is whether FirstCash Holdings' current share price is justified by the level and quality of earnings the company is producing today.
If you are weighing whether FirstCash Holdings' current earnings justify its price, it can help to compare that question across 32 high quality undervalued stocks.
Is FirstCash Holdings Getting Expensive on Earnings?
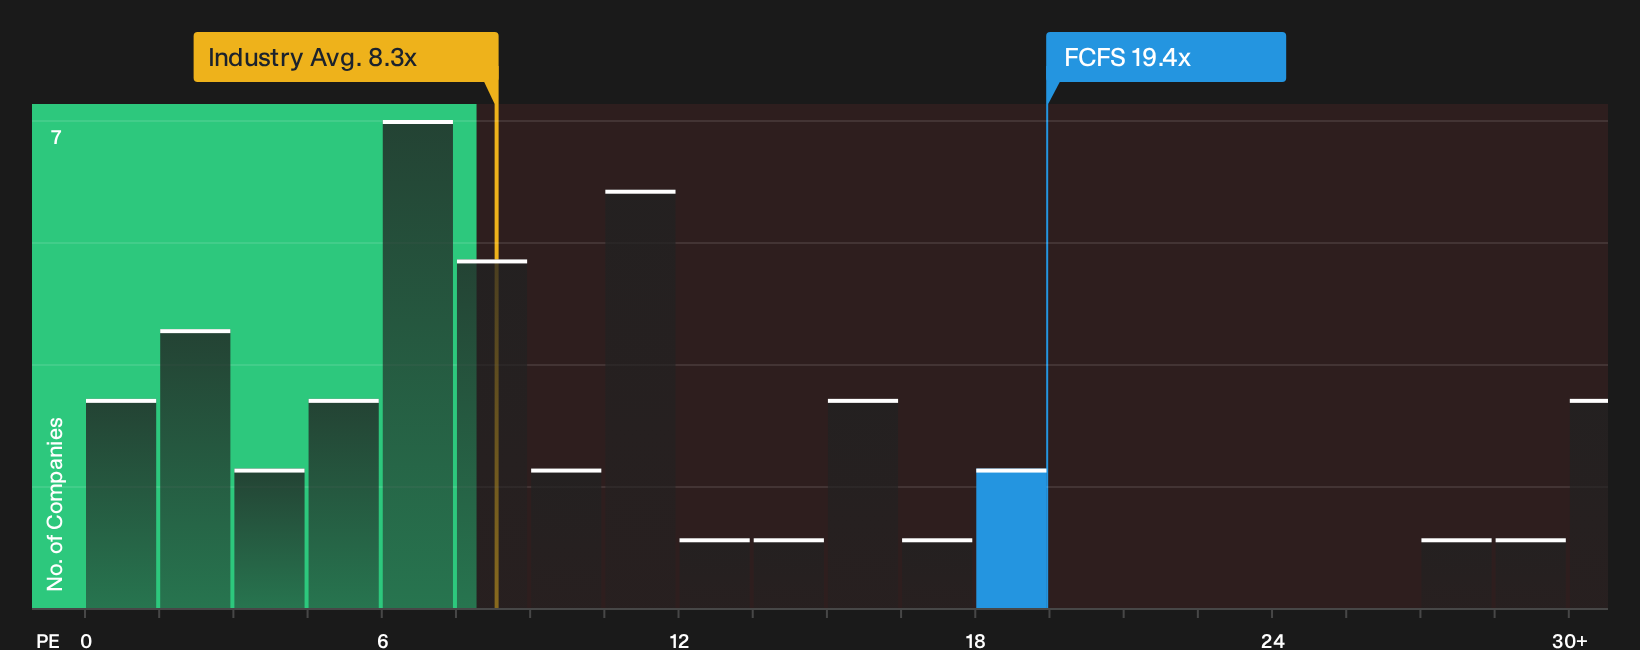
The P/E ratio fits FirstCash Holdings because earnings are a central yardstick for consumer finance businesses. At about 19.4x earnings, the stock trades well above the Consumer Finance sector average of roughly 8.3x and ahead of the peer group near 12.1x. The market is attaching a richer price tag to each dollar of profit than is typical in the sector.
The fair multiple implied by the valuation framework sits below the current P/E, so on this lens the shares screen as overvalued rather than cheap. Because the recent legal investigation follows a reported hit to operating income in the American First Finance unit, this premium P/E means you are paying up despite fresh questions around that profit stream. That gap between price and the modelled fair level is what the detailed comparison in. Explore the numbers behind FirstCash Holdings's P/E valuation.
The FirstCash Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for FirstCash Holdings leaves off and spell out which expectations on growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today. Each narrative ties its number to a specific view on how FirstCash Holdings' growth, margins and risk profile could evolve. You can revisit these views as new information on the business becomes available.
A clear, number driven narrative on FirstCash Holdings helps pin down what has to go right from here, especially around how the American First Finance segment responds after the reported hit to operating income and gross transaction volume linked to merchant partner bankruptcies. With those assumptions written out, you can track over time whether management decisions and future earnings reports support or undermine the case you are making today.
Share your own Narrative for FirstCash Holdings and set out the assumptions behind your valuation.
The FirstCash Holdings share price is only one piece of your decision
Price multiples tell you how the market values today's earnings, but broker models also map out where they think this business could be a few years from now, giving you another lens to compare with today's valuation. Explore where analysts expect FirstCash Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com