


RUM Group (RUM) reported third quarter 2026 results that combined sharply higher sales with a wider loss, giving investors fresh numbers to weigh its AI infrastructure pivot against continued spending.
RUM Group’s Q3 release landed after a sharp 1-day share price return of 16.63%. This extended a short streak of gains but came against a 30-day share price return that is down 12.87% and a 90-day share price return that is down 20.95%. The 3-year total shareholder return of 20.40% contrasts with a 5-year total shareholder return that is down 39.03%, pointing to momentum that has recently cooled after earlier gains.
Scan how RUM Group’s AI pivot compares with other potential breakouts by checking a curated set of 53 AI infrastructure stocks in the same emerging buildout theme.
RUM Group now appears to be a fast-growing AI infrastructure and media platform paired with steep losses and a volatile share price. After this spike, to what extent does the valuation already assume that story plays out?
Most Popular Narrative: 75% Undervalued
RUM Group’s last close of $5.96 sits well below the $23.50 fair value in the analyst consensus Narrative on Simply Wall St. This estimate reflects detailed revenue, margin and contract assumptions rather than a single person’s opinion.
Expanding commercial partnerships with companies such as Tether, Cumulus Media, leading AI customers and MoonPay now sit alongside contracts worth US$270 million with Together AI and approximately US$13.7b with a major U.S. AI customer. These developments can deepen enterprise relationships and broaden RUM Group’s revenue base beyond advertising into long duration AI infrastructure services.
See why 24 investors see RUM Group as 75% undervalued.
Result: Fair Value of $23.50 (UNDERVALUED)
Still, RUM Group’s bullish AI narrative depends on funding a sizable GPU buildout and on managing potential dilution from the large warrant package tied to its US$13.7b contract.
Find out about the key risks to this RUM Group narrative.
Another View: What RUM Group’s Sales Multiple Is Saying
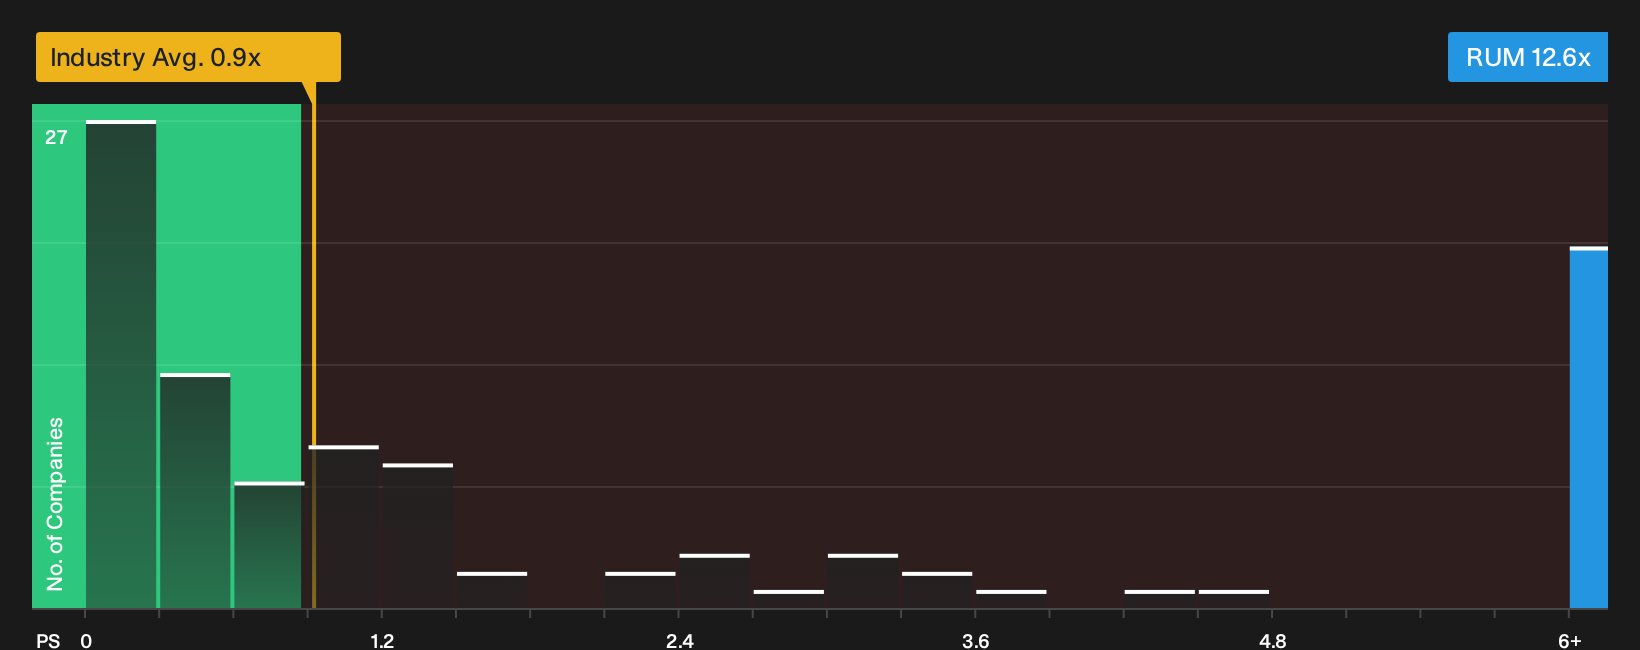
The analyst fair value narrative paints RUM Group as undervalued, yet the current P/S ratio of 12.6x is far above peers at 1.9x and the US Interactive Media and Services industry at 0.9x. It even exceeds the fair ratio of 10.8x, which points to valuation risk if sentiment cools.
For readers who want to see how the numbers stack up when earnings eventually matter more than revenue, the valuation breakdown based on this sales multiple helps frame that trade off, especially for a business still reporting losses and past shareholder dilution. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on RUM Group’s value story can be confusing, especially with both risks and bright spots in play. It helps to move fast and stress test the data yourself while sentiment is still unsettled. To weigh that balance directly, start with the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond RUM Group?
If RUM Group caught your attention, do not stop here. Fresh opportunities often show up where valuation, balance sheet quality and income potential quietly line up.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that combines quality fundamentals with compressed expectations.
- Strengthen capital preservation by reviewing a 30 resilient stocks with low risk scores that filters for resilient businesses with more measured risk profiles.
- Grow your watchlist with a 19 high quality undiscovered gems built around lesser-known companies that already post strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com