


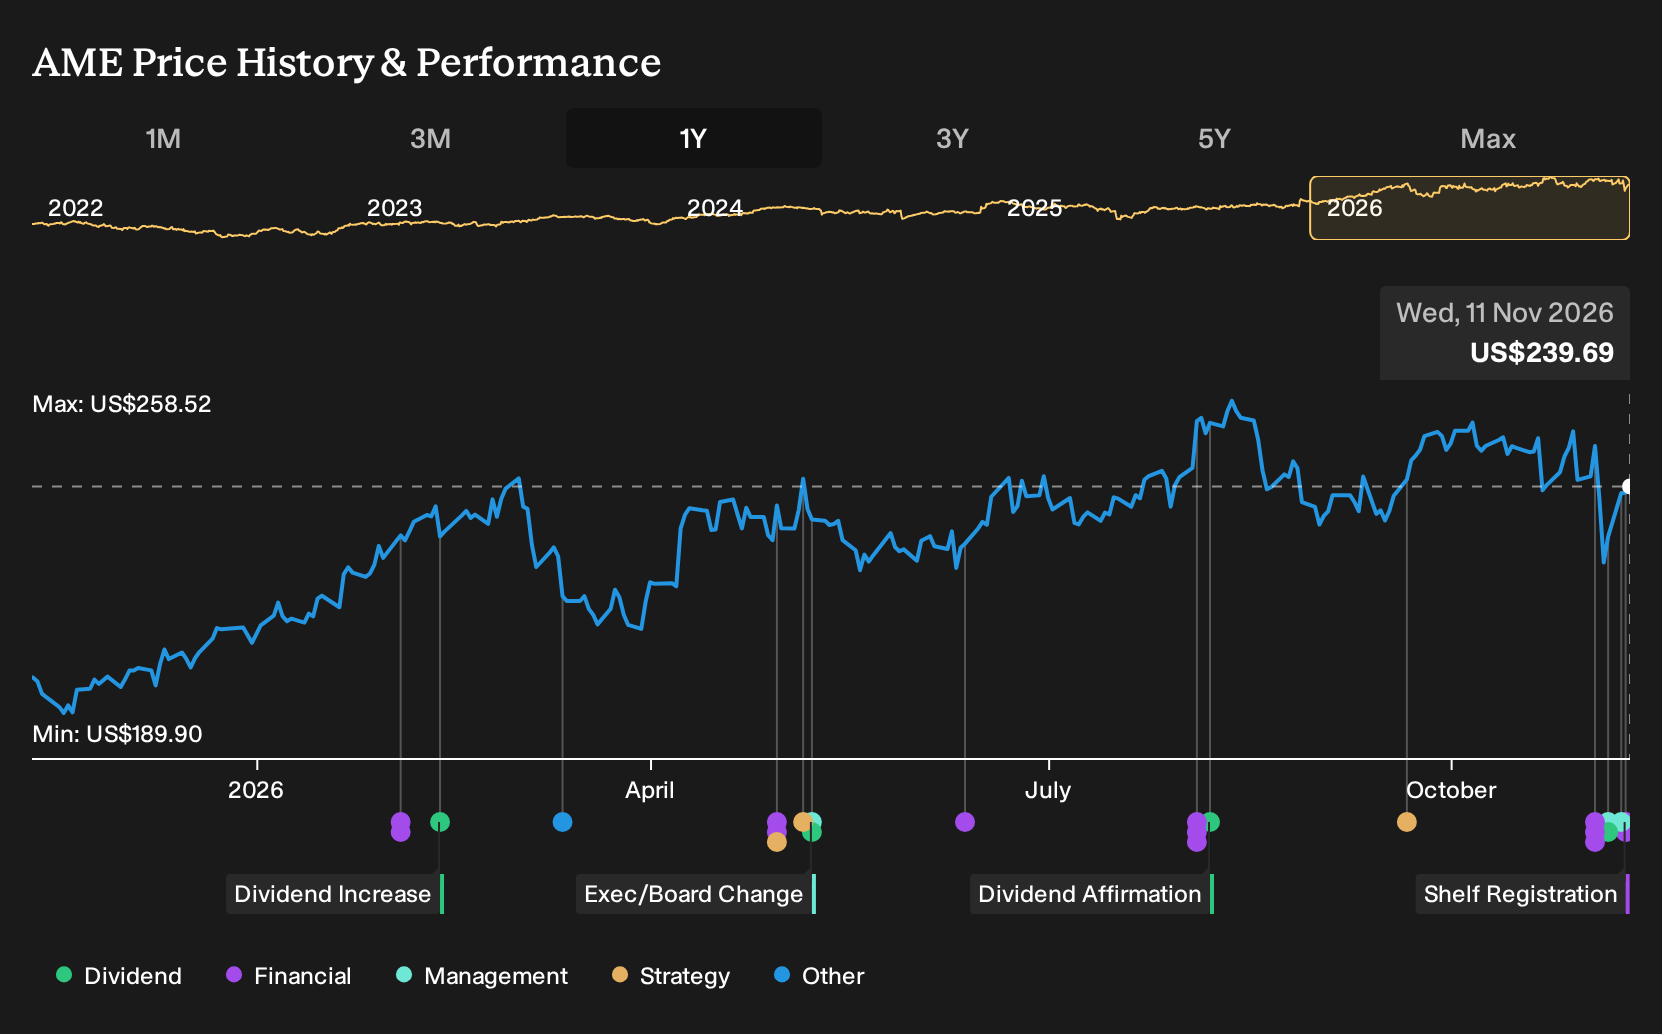
- AMETEK reported third quarter 2026 sales of US$2,220.31 million and net income of US$426.3 million, raised full year earnings guidance, confirmed fourth quarter expectations, affirmed a US$0.3400 quarterly dividend and filed an omnibus shelf registration covering multiple types of securities.
- The combination of stronger quarterly fundamentals, higher earnings targets and fresh financing flexibility through the universal shelf filing gives AMETEK added room to fund acquisitions, capital spending and general corporate needs without relying on a single source of capital.
- We will now look at how AMETEK's stronger third quarter earnings and raised guidance interact with its existing long term investment narrative.
AMETEK Investment Narrative Recap
To own AMETEK, you need to be comfortable with a premium P/E and a story built around steady execution in AI related instrumentation, aerospace and defense, power infrastructure and automation rather than rapid headline growth. The raised full year and fourth quarter earnings guidance reinforces that this execution focused narrative is still intact.
In the near term, the key catalyst is continued delivery on high margin instrumentation and acquisition integration, including platforms like Indicor, while keeping cash generation strong. The main risk is sentiment toward paying up for industrials. The recent results and guidance update are supportive, but do not fundamentally change that valuation sensitivity.
The universal shelf registration looks most relevant for assessing what happens next. AMETEK now has the flexibility to issue common equity, preferred shares, debt or warrants. This gives it more optionality to fund acquisitions in areas like automation, MedTech or power and process instrumentation that feature prominently in the analyst consensus Narrative on Simply Wall St.
Flexibility cuts both ways for investors. Expanded funding tools can help management pursue higher margin, recurring revenue targets, but they can also introduce dilution or higher leverage if used heavily. For a story already tied to a premium multiple and meaningful debt, how AMETEK chooses to use that shelf is a central part of both the catalyst and risk discussion.
AMETEK's current earnings of US$1.6b are projected by analysts to rise to US$2.3b by 2029, which implies an earnings increase of about US$700m. The same consensus view points to revenue of US$10.5b by that year and an annual top line growth rate of 8.6%.
Uncover why AMETEK's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value views on AMETEK from the Simply Wall St Community already span a wide band, from about US$174 per share to roughly US$285, across three separate contributors. You are seeing private investors baking in very different expectations just as the universal shelf filing, dividend affirmation and board changes reshape the risk and opportunity mix.
Explore 2 other AMETEK fair value estimates, including one that suggests as much as 27% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your AMETEK research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AMETEK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMETEK's overall financial health at a glance.
Looking for more AMETEK sized investment ideas?
If AMETEK has sharpened your thinking about quality, funding flexibility and valuation, use that same lens to scan a broader watchlist with the Simply Wall St Screener.
- For investors who want potential upside with a margin of safety, start by reviewing companies that screen as attractively priced through our 32 high quality undervalued stocks.
- If income and resilience matter most to you, focus on businesses that combine meaningful yields with robust fundamentals via the 6 dividend fortresses.
- When capital preservation is a priority, concentrate on businesses that show stronger balance sheets and steadier metrics using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com