


Why FIGS stock is back in focus
FIGS (FIGS) moved onto investor radar after its latest earnings release for the September quarter, along with updated guidance for year-end revenue growth and a new uniform partnership with European Wax Center.
FIGS stock has been on a strong run, with a 31.91% 1 month share price return and a 57.68% move over 90 days. The 1 year total shareholder return of 133.53% and 3 year total shareholder return of about 2.6x reflect building momentum off the back of the earnings beat, raised full year revenue guidance and the European Wax Center uniform deal.
Scan for other apparel and consumer brands showing similar post earnings momentum to FIGS using the hand picked 19 high quality undiscovered gems list.
FIGS has already delivered a triple digit 1 year return. The sharper question now is whether recent earnings strength and the European Wax Center deal still leave meaningful upside on the table, or if the big move has already happened.
Most Popular Narrative: 63% Overvalued
FIGS last closed at $23.40, while the most followed narrative on Simply Wall St places fair value closer to $14.39, implying a wide gap between current enthusiasm and that fair value estimate based on a 9% discount rate.
According to julio, an investor in the Simply Wall St Community who wrote the narrative, the appeal of FIGS sits in how the business mixes brand strength, product focus and reinvestment, rather than in any single financial metric.
FIGS concentrates on a specific niche within the healthcare industry, medical professionals. The company sells primary apparel, as well as related products. By catering to the unique needs and preferences of this market segment, FIGS tailors its products to precisely match their requirements. This has allowed the company to develop a brand synonymous with this segment, improving its competitive positioning.
See why 25 investors see FIGS as 63% overvalued.
The narrative balance is clear. Revenue of $749.11m and net income of $72.46m show a profitable, growing apparel platform, yet the community fair value still sits well below the market price. That fair value view reflects expectations of revenue growth around 11%, profit margins at 9% and a 9% discount rate applied to future cash flows rather than the recent share price surge.
Result: Fair Value of $14.39 (OVERVALUED)
Still, the FIGS story can break if revenue growth slows further, or if its premium positioning proves sensitive to weaker spending from healthcare workers.
Find out about the key risks to this FIGS narrative.
Another View: FIGS through a cash flow lens
The first community narrative values FIGS at $14.39, well below the recent $23.40 share price. The SWS DCF model tells a different story. It places future cash flow value at $28.61, which is above where the stock trades today. Which version of fair value seems more reasonable to you?
Look into how the SWS DCF model arrives at its fair value.
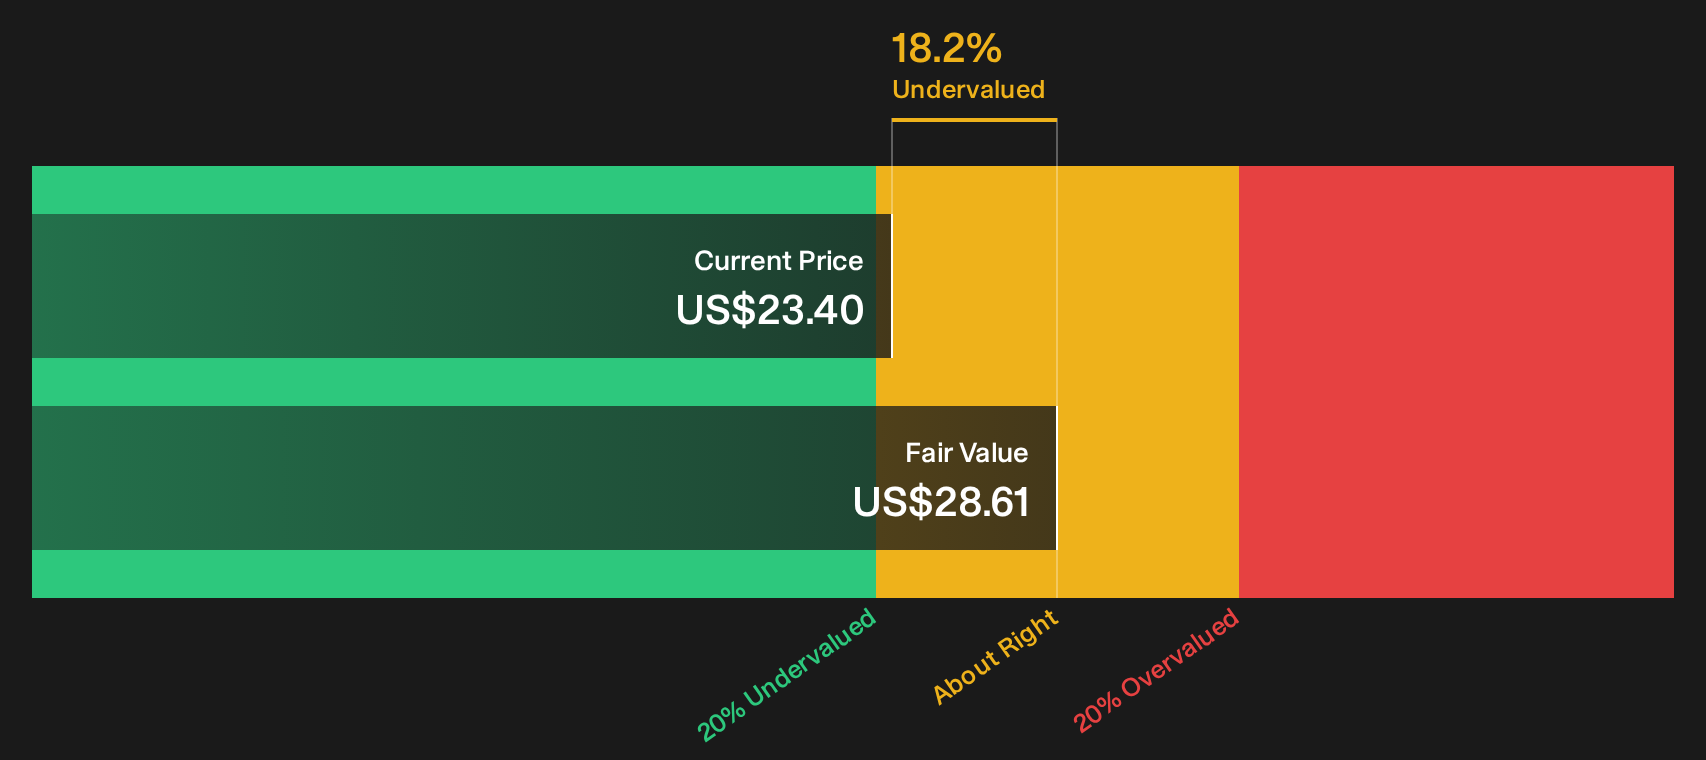
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FIGS for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinion is clearly split on FIGS right now, with valuation tools pointing in different directions. Act while the data is fresh and stress test the optimistic case using the 2 key rewards.
Looking for more FIGS-like investment ideas?
If FIGS has sharpened your focus on quality and valuation tension, broaden your watchlist now and keep your next move grounded in clear, comparable data.
- Target resilient balance sheets first, then filter the noise using the focused list of solid balance sheet and fundamentals (23 results) for companies with fundamentals that aim to support durability.
- Zero in on potential mispricing by scanning the curated 32 high quality undervalued stocks that highlights financially solid businesses trading at what may be discount levels.
- Keep an eye on quieter opportunities and widen your hunting ground with the hand picked 19 high quality undiscovered gems before the crowd turns its attention there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com