


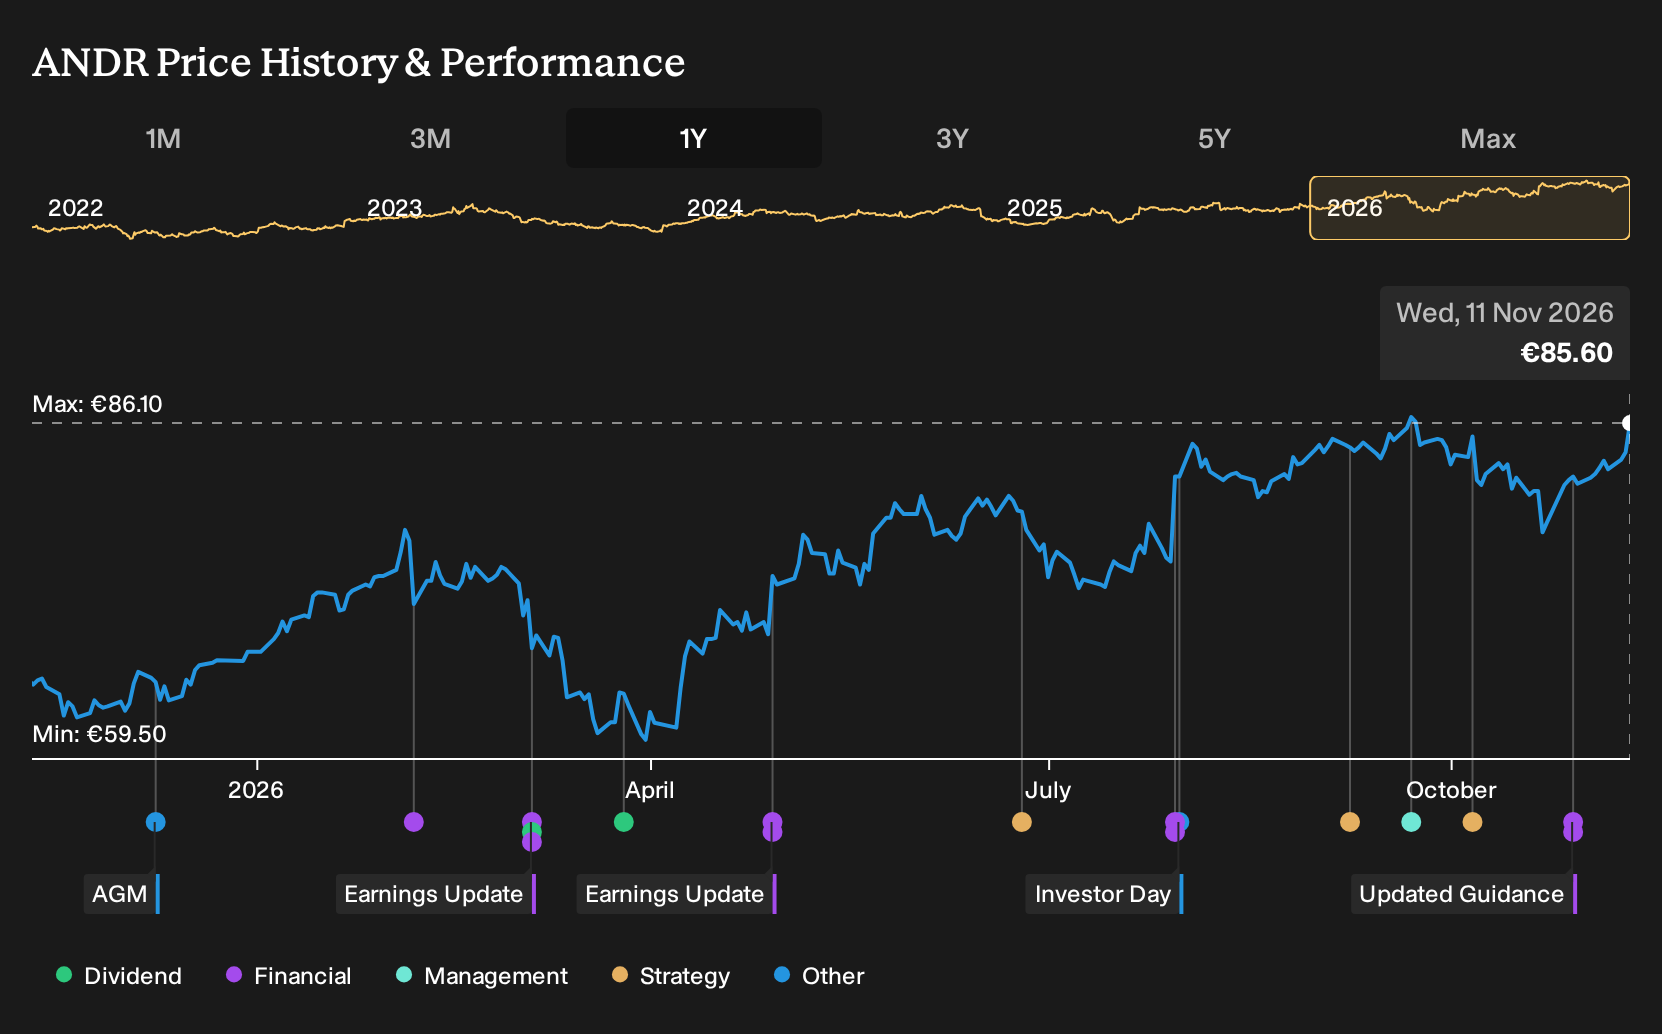
- Andritz confirmed its full year 2026 earnings outlook in late October, reiterating a revenue range of €8.0b to €8.3b and stating that it expects a return to growth.
- The reiterated guidance underlines management’s focus on turning a large order backlog, a higher service share and automation offerings into steady revenue and earnings quality instead of revising targets mid year.
- We will explore how Andritz’s investment narrative is affected by the reaffirmed 2026 revenue guidance and management’s expressed confidence in future performance.
Andritz Investment Narrative Recap
To own Andritz, you need to be comfortable with a story built on turning a record €12.9b order backlog into steadier earnings, with a heavier lean on higher margin services, automation and hydropower projects. The confirmed 2026 revenue range of €8.0b to €8.3b supports that focus, but it does not change the immediate thesis in a dramatic way.
The key short term swing factor is still execution on converting that backlog, especially in Hydropower and services, into timely, profitable delivery. The biggest near term risk sits in Environment & Energy, where order intake and revenue already declined, and where leadership disruption could slow decisions just as newer energy transition offerings are under pressure.
The analyst consensus Narrative on Simply Wall St ties much of the outlook to that large backlog, the higher service mix and the roughly €800m automation and digitalization activity around the Metris platform. The reiterated 2026 guidance lines up with that framing, since it points to management relying on existing orders and services to support the revenue range rather than leaning on a surge in new, unproven areas.
No major new announcements sit alongside this guidance. As a result, the most relevant reference point is still the shift in business mix described in that narrative. For you, the question is whether Andritz can offset softer Environment & Energy demand and management churn with execution in Hydropower, Pulp & Paper service work and automation, where recurring revenue and digital projects are expected to be important earnings drivers.
Andritz's narrative projects €9.7b revenue and €660.6 million earnings by 2029. This aligns with analysts who assume 6.2% yearly revenue growth and an earnings increase of about €195 million from €465.5 million today.
Uncover why Andritz's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist in the alternate Andritz story is operating cash flow. Some higher end analysts leaned on the €653 million in 2025 and €291 million in H1 2026 to justify faster mix improvement and earnings near €750.7 million on about €10.2b in revenue by 2029. Those pre news views may shift after the reiterated 2026 outlook, so compare them to your own expectations.
Explore 5 other Andritz fair value estimates, including one that suggests the potential for as much as 75% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Andritz research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Andritz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Andritz's overall financial health at a glance.
Looking For More Investment Ideas Beyond Andritz?
Once you have a view on Andritz, it can help to sanity check that thinking against a wider field of opportunities using the Simply Wall St Screener.
- If you want potential value paired with balance sheet strength, start with a list of solid balance sheet and fundamentals (193 results) that can handle tougher conditions without stretching finances.
- For investors who care most about capital resilience, scan a 208 resilient stocks with low risk scores that aims to keep surprises in check.
- When you are hunting for underfollowed ideas with solid fundamentals, look through a 563 high quality undiscovered gems that may not yet be widely owned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com