


Performance Food Group (PFGC) grabbed investor attention after reporting first quarter sales of $18.0b and net income of $129.5m, along with reaffirmed guidance for both the second quarter and full fiscal 2027.
On the market side, Performance Food Group’s recent earnings and reaffirmed guidance have arrived alongside firm share price momentum, with a 30 day share price return of 17.4% contributing to a 26.3% year to date gain and a 5 year total shareholder return of 148.4%.
Scan how Performance Food Group compares with other distributors showing strong momentum and scale by running the curated 32 high quality undervalued stocks.
Performance Food Group has just posted stronger quarterly numbers, and the share price has sprinted ahead, yet the stock still trades below analyst targets. Is that a reasonable safety margin, or a sign the market sees risks others are glossing over?
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Performance Food Group screens as undervalued, with a fair value of $125.75 against the latest close of $111.21. This points to upside in that framework while still leaving a gap to the Street target.
Procurement initiatives that are expected to reach or exceed the high end of the US$120m to US$125m synergy target by fiscal 2028, together with the reported US$0.34 per case gross profit uplift in Q4 2026, set up a structural tailwind for net margins and EBITDA.
See why 3 investors see Performance Food Group as 12% undervalued.
Result: Fair Value of $125.75 (UNDERVALUED)
Still, the analyst story around Performance Food Group could weaken if Cheney Brothers integration costs remain elevated for an extended period or if fuel price volatility continues to compress margins.
Find out about the key risks to this Performance Food Group narrative.
Another View on Performance Food Group’s Valuation
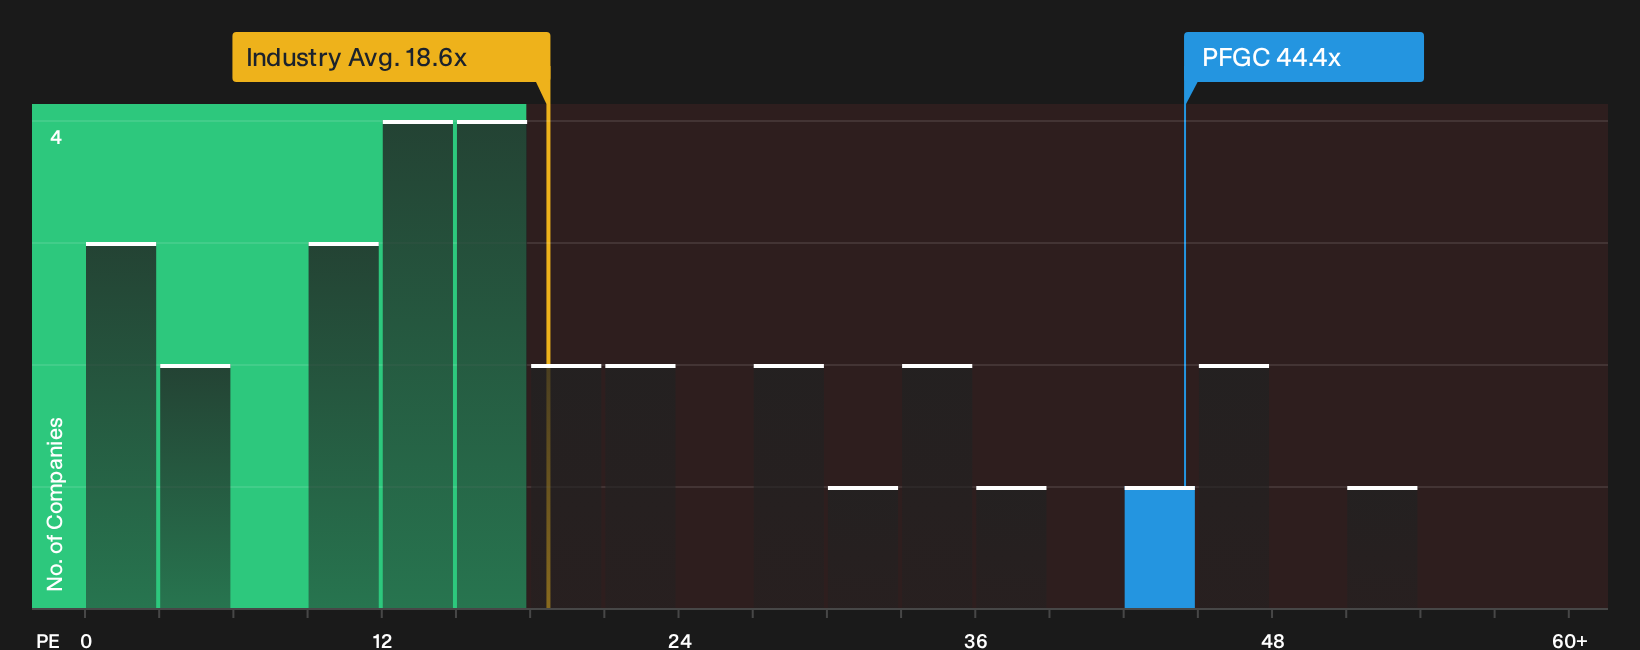
The analyst narrative presents Performance Food Group as undervalued relative to a fair value of $125.75. The P/E picture, however, suggests a more demanding valuation. At 44.4x earnings versus a US Consumer Retailing average of 18.6x and a peer average of 32.6x, the stock trades at a premium that is also above its fair ratio of 29.6x. This kind of gap can act as a headwind if sentiment cools. The key question is whether the growth and margin profile is compelling enough for investors to continue paying this higher multiple.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Performance Food Group’s valuation are already clear, with both risks and bright spots on the table. Consider acting promptly and test the assumptions against your own thresholds using the 2 key rewards and 1 important warning sign.
Looking for more Performance Food Group style ideas?
If Performance Food Group has sharpened your focus on valuation, momentum and quality, broaden your watchlist now so you do not miss the next opportunity.
- Spot potential mispricings early by scanning a curated 32 high quality undervalued stocks that filters for companies combining quality fundamentals with attractive valuations.
- Strengthen portfolio resilience by using a focused 30 resilient stocks with low risk scores that highlights businesses with lower risk profiles based on key financial metrics.
- Get ahead of the crowd with a targeted 19 high quality undiscovered gems that surfaces smaller companies with strong underlying fundamentals before they hit the spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com