


- Marzetti reported first quarter 2026 results with sales of US$481.52 million and net income of US$29.3 million, both lower than the prior year, while also continuing a 64 year streak of rising regular cash dividends.
- The planned collaboration with Tajín on a shelf stable dressing line, targeting uses beyond salads, signals a push to broaden usage occasions and refresh Marzetti's licensing approach beyond restaurant brand partnerships.
- We will now see how Marzetti's investment narrative around branded growth and margins could be affected by softer earnings and the Tajín partnership.
Scan how Marzetti's mix of softer earnings, a long dividend streak, and new licensing efforts compares with other food and consumer staples stocks screened for 30 resilient stocks with low risk scores.
Marzetti Investment Narrative Recap
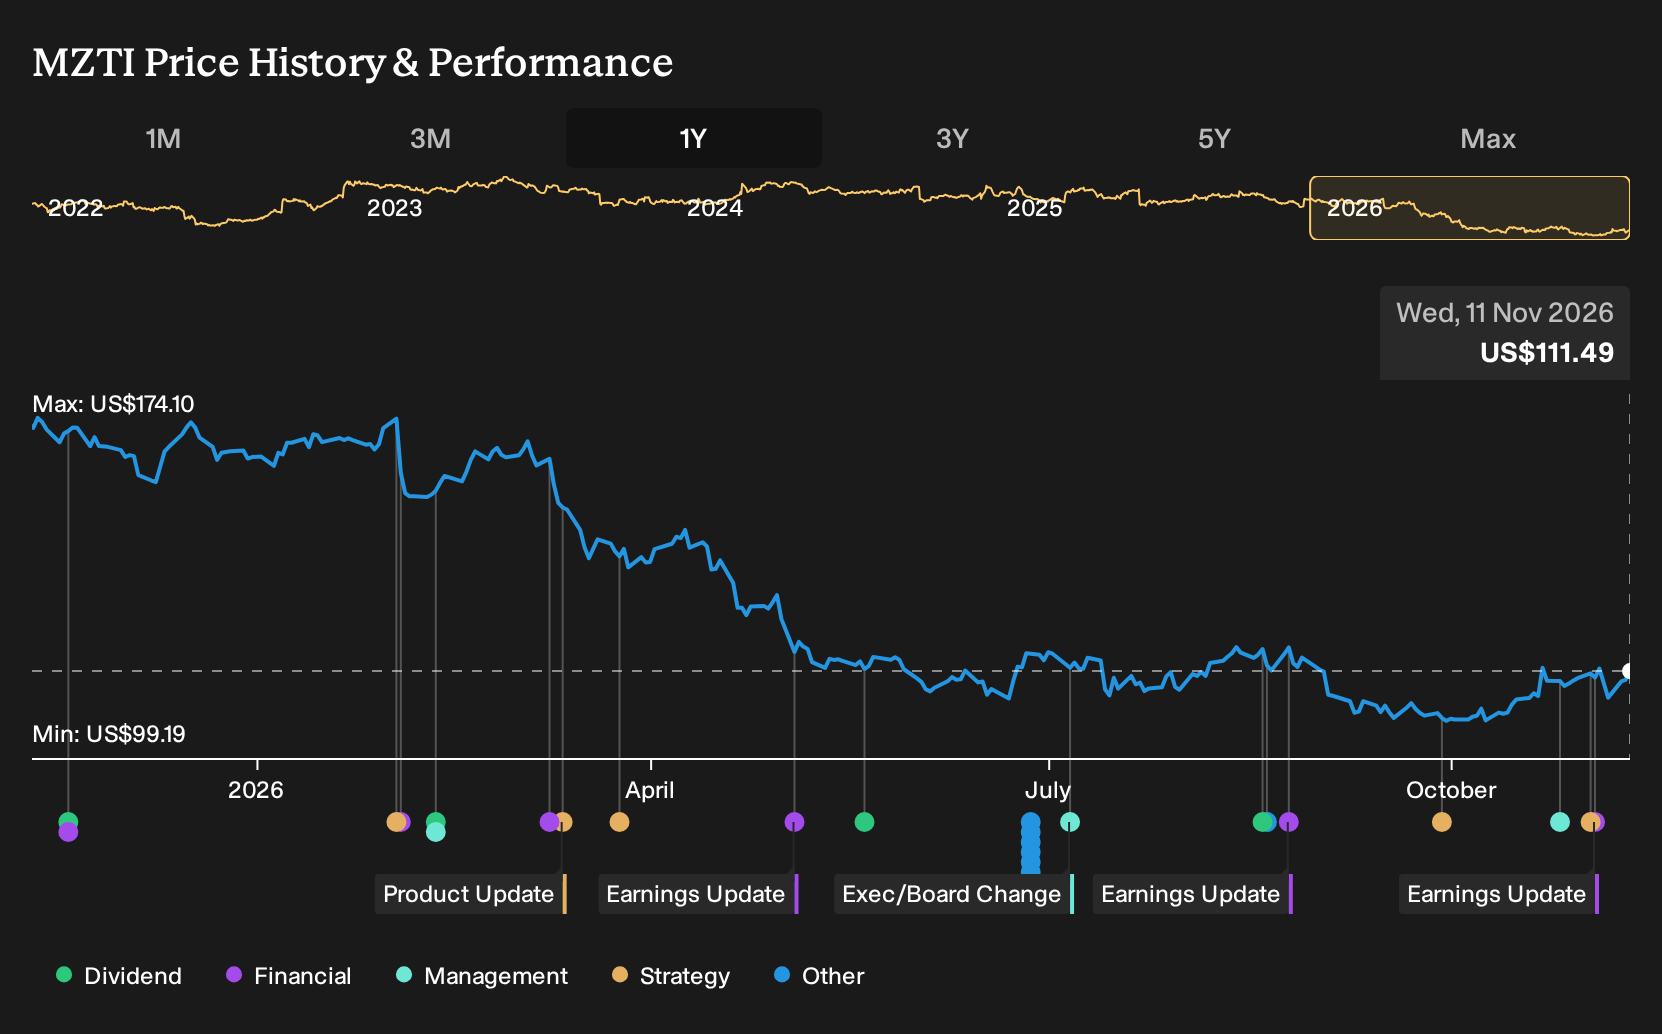
To own Marzetti, you need to believe this is a steady specialty food producer that can steadily refine its mix, protect margins and keep cash returns flowing even when a quarter is soft. The latest results show sales at US$481.52 million and net income at US$29.3 million, both below the prior year, which keeps short term focus firmly on cost discipline and product mix rather than headline growth.
The analyst consensus Narrative on Simply Wall St leans on measured earnings expansion and margin improvement over time. That story now meets a near term risk that pricing power and volumes stay under pressure while input costs remain volatile. Earnings softness is a watchpoint, but it does not yet rewrite the long term thesis built around branded products, supply chain efficiency and reliable dividends.
The Tajín collaboration sits closest to that thesis, because it plugs directly into the push for licensed and branded products that analysts see as a key catalyst. Marzetti brings dressings expertise and retail reach, and Tajín provides flavor recognition. Together they test whether new flavor platforms can support volume and premium pricing beyond traditional salad usage.
This new line, expected to pilot in Spring 2027, also speaks to one of Marzetti's bigger risks. A relatively narrow portfolio and consumer shifts toward fresher or cleaner foods could weigh on demand if the product set does not evolve. Execution on Tajín, alongside existing branded launches like Texas Roadhouse rolls mentioned in the analyst consensus Narrative on Simply Wall St, will be important signals for how effectively the business adapts to those pressures.
Analysts expect Marzetti to reach about US$2.1b in revenue and US$199.2 million in earnings by 2029. This implies revenue growth of 3.4% per year and an earnings increase of roughly US$25.8 million from earnings of US$173.4 million today.
Uncover why Marzetti's fair value indicates a 21% potential upside to its current price before that discount gap tightens.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Marzetti’s margin story, not just the Tajín launch. Before these results, the bullish camp was penciling in earnings of about US$192.0 million by 2029 on roughly US$2.1b of revenue, along with a higher future P/E. You can compare that view with today’s softer quarter and decide whether those assumptions still feel realistic.
Explore 2 other Marzetti fair value estimates, including one that indicates a potential 66% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Marzetti research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Marzetti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marzetti's overall financial health at a glance.
Looking for more investment ideas beyond Marzetti?
Once you have formed a view on Marzetti, it often helps to compare that thesis with other opportunities that share similar qualities or offer something very different. The Simply Wall St Screener can help you quickly surface stocks that match the kind of balance sheet strength, income profile, or valuation style you prefer, so your portfolio is driven by a clear plan rather than just the latest headline.
- If capital preservation and steadier business profiles matter most to you, start with a 30 resilient stocks with low risk scores that score well on resilience.
- If income is your focus, you can hunt for companies with meaningful yields that still look robust by running a 6 dividend fortresses built around stronger fundamentals.
- If you want to broaden your watchlist with potential future leaders rather than the usual blue chips, filter for a 19 high quality undiscovered gems that pair quality metrics with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com