


EZCORP earnings spark fresh look at the stock
EZCORP (EZPW) just released fourth quarter and full year results, with revenue, net income and earnings per share for both periods higher than a year earlier. This has put fresh attention on the pawn lender.
At a share price of $28.30, EZCORP has given investors a 41.08% year to date share price return. The 1 year total shareholder return of 62.55% and 3 year total shareholder return above 3x suggest strong longer term momentum, even after a 14.42% decline in the 1 month share price return as expectations around earnings and risk have reset.
Scan more pawn and specialty finance stocks that are experiencing similar earnings momentum with our handpicked list of 19 high quality undiscovered gems.
After a sharp run over the past year and a pullback of more than 14% in the last month, EZCORP now forces a choice: lean into this reset or wait for a cleaner entry as the valuation picture comes into focus next.
Most popular narrative: 31% undervalued
On the latest analyst consensus Narrative on Simply Wall St, EZCORP screens as undervalued, with a fair value of $40.80 compared to the recent $28.30 close. That gap frames how analysts are considering earnings power and risk.
Continued focus on core pawn profitability, with most recent EBITDA and gross profit growth coming from pawn operations rather than scrap gold, positions future earnings and net margins to depend more on recurring loan demand and merchandise sales than on gold price movements.
See why 21 investors see EZCORP as 31% undervalued.
Result: Fair Value of $40.80 (UNDERVALUED)
Still, the EZCORP narrative can break if acquisitions drag on costs without lifting earnings, or if tighter pawn rules cap fees and squeeze profitability.
Find out about the key risks to this EZCORP narrative.
Another view on EZCORP valuation
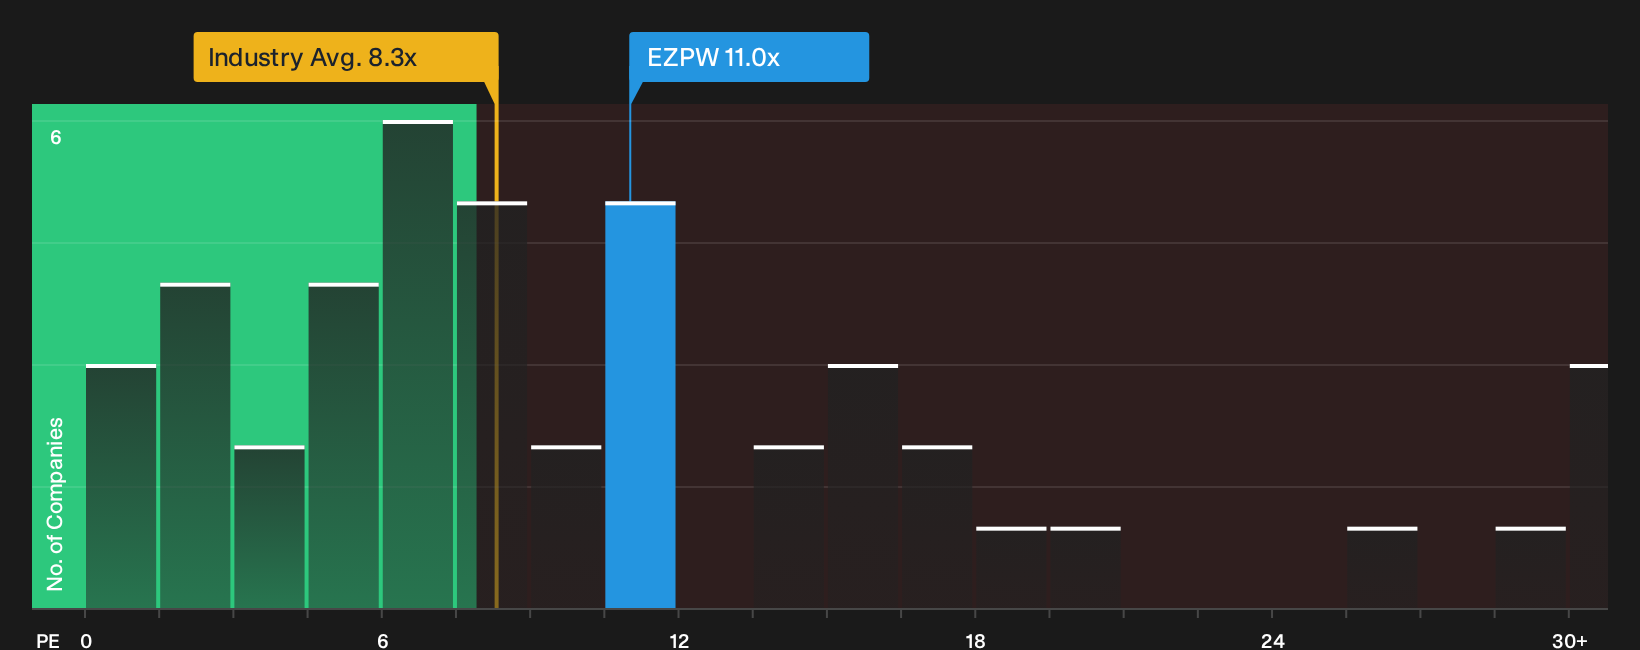
Analyst models point to EZCORP trading below a fair value of about $40.80, yet the current P/E of 11x adds a different twist. That multiple is higher than both the US Consumer Finance industry at 8.3x and its peer average of 8.3x, while only slightly below a fair ratio of 11.6x. For investors, that mix of discounted fair value and rich peer comparison raises a simple question: Is the market underestimating earnings resilience or already paying up for it?
For a closer look at how the current price compares with peers and the fair ratio, and what that might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed message or clear opportunity? If you want to move quickly and base your decision on the full picture, consider both sides with the 4 key rewards and 1 important warning sign.
Looking for more EZCORP-sized opportunities?
If EZCORP has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted idea pools that many investors overlook.
- Target resilient performers by scanning a 30 resilient stocks with low risk scores that already filters for businesses with steadier profiles and less volatile risk scores.
- Hunt for mispriced potential with a 32 high quality undervalued stocks that highlights companies where quality and current pricing look meaningfully out of sync.
- Strengthen your shortlist by pulling ideas from a list of solid balance sheet and fundamentals (23 results) so you are focusing on businesses backed by healthier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com