


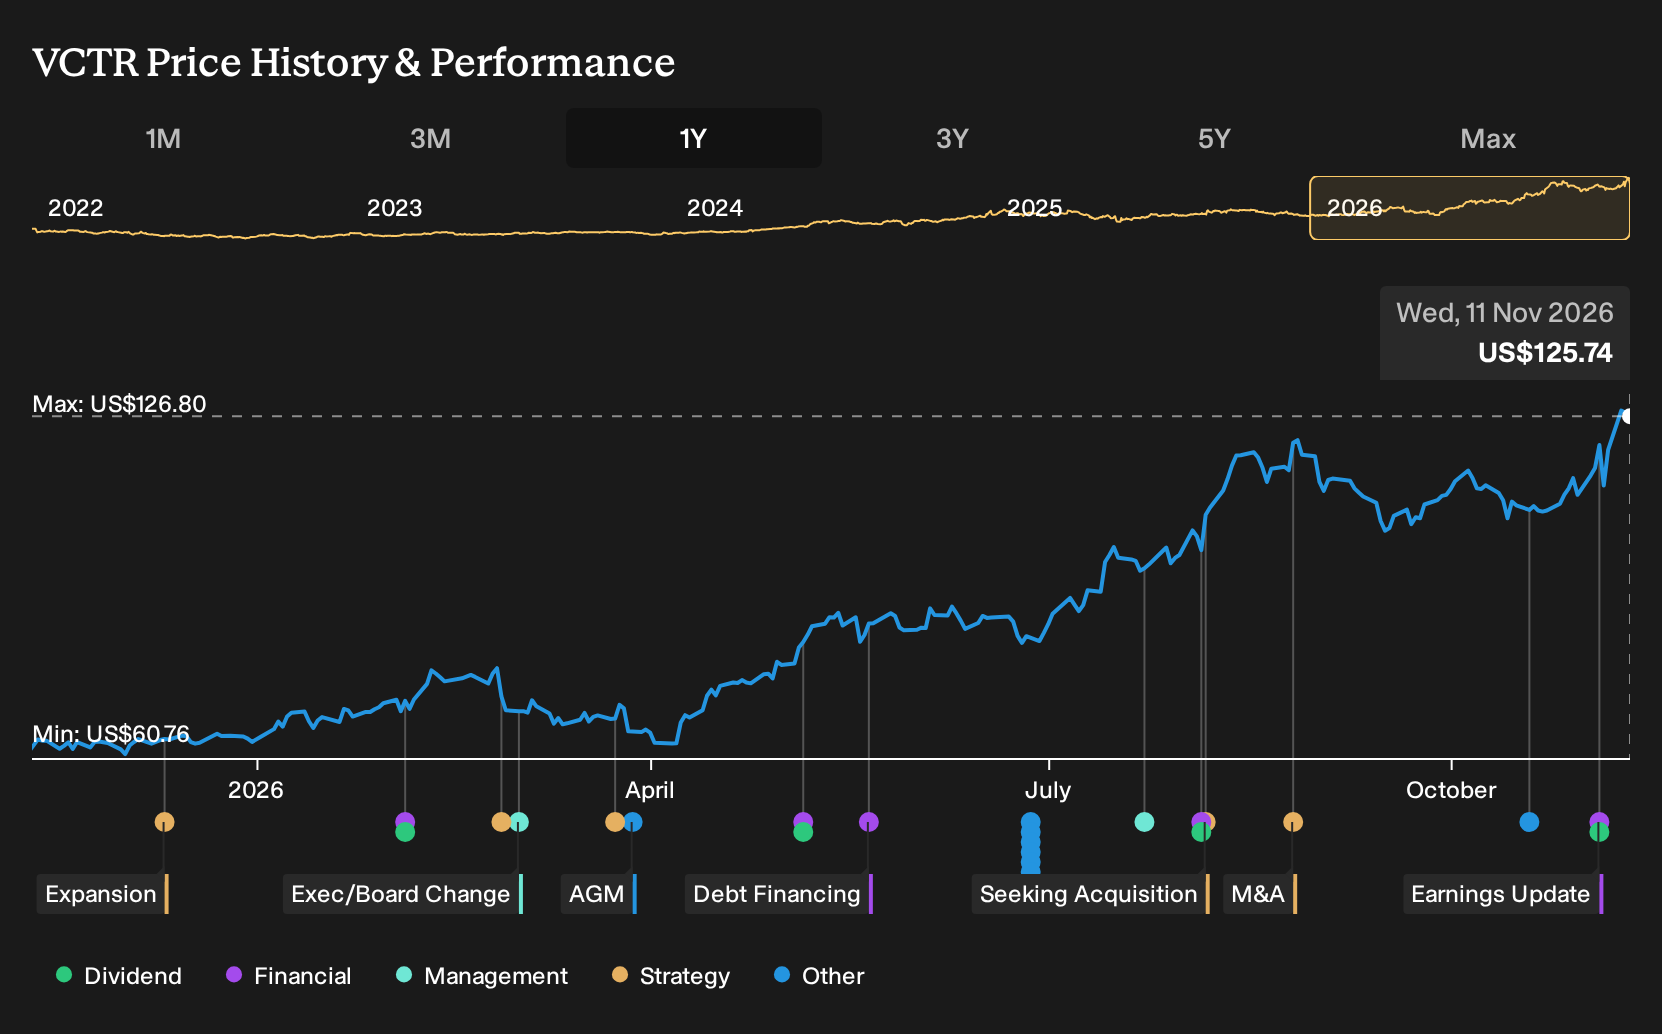
- Victory Capital Holdings reported third quarter 2026 revenue of US$396.57 million and net income of US$91.3 million, with nine month revenue of US$1.22b and net income of US$342.85 million, and reaffirmed a US$0.50 quarterly dividend payable in December 2026.
- Total client assets reached US$360.5b at the end of October 2026, which indicates that Victory Capital Holdings already operates at substantial scale ahead of any impact from the planned First Eagle acquisition.
- We will now examine how Victory Capital Holdings' higher nine month net income affects the investment narrative that analysts outlined earlier.
Scan how Victory Capital Holdings compares with other large-scale asset managers by reviewing the hand-picked list of solid balance sheet and fundamentals (23 results) that may offer similar earnings resilience and balance sheet strength.
Victory Capital Holdings Investment Narrative Recap
Owning Victory Capital Holdings means believing the asset management platform can keep scaling earnings while absorbing the planned First Eagle acquisition and higher leverage. The nine month net income of US$342.85 million helps support that view, although the flat quarterly EPS alongside lower quarterly net income keeps execution quality in focus rather than materially shifting the near term story.
The key short term catalyst from the analyst consensus Narrative on Simply Wall St remains how cleanly Victory Capital Holdings closes and integrates First Eagle, including the targeted US$280 million of net expense synergies. The biggest risk is still the jump in net debt to adjusted EBITDA and any stumble on cost saves or client retention.
The reaffirmed US$0.50 quarterly dividend payable in December 2026 is the announcement that ties closest to this earnings update. It signals that Victory Capital Holdings is keeping its current capital return plans in place at the same time as it prepares for a larger balance sheet once the First Eagle transaction completes.
For you as a shareholder, that dividend decision sits alongside rising nine month revenue of about US$1.22b and total client assets of US$360.5b as you weigh catalysts and risks. It keeps income expectations steady while attention stays on leverage, the US$280 million synergy plan, and whether the integration track record highlighted in the analyst consensus Narrative on Simply Wall St holds at a bigger scale.
Victory Capital Holdings' narrative projects US$2.8b revenue and US$1.8b earnings by 2029. This assumes revenue growth of 20.7% per year and an earnings increase of about US$1.45b from US$348.1 million today.
Uncover why Victory Capital Holdings' fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Victory Capital Holdings leans heavily on fee pressure as the key risk. The most cautious analysts were pencilling in revenue of about US$1.9b and earnings of roughly US$1.1b by 2029, well below the consensus narrative. Those estimates came before this latest earnings and dividend news, so you may see those stories evolve in different directions once analysts refresh their models.
Explore 2 other Victory Capital Holdings fair value estimates, including one that suggests as much as 32% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Victory Capital Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Victory Capital Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Victory Capital Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Victory Capital Holdings?
If this update on Victory Capital Holdings sharpened your thinking, apply that same lens across a broader watchlist. The Simply Wall St Screener allows you to focus on the traits that matter to you, from balance sheet strength to income potential.
- If you prefer durability and capital preservation first, start with a basket of companies screened for resilience through the 30 resilient stocks with low risk scores.
- If you are hunting for quality at a sensible price, shortlist opportunities that combine fundamentals with attractive pricing through the 32 high quality undervalued stocks.
- If you are looking to anchor your portfolio with regular cash payouts, build a watchlist of income ideas sourced from the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com