


Hokkaido Electric Power Company (TSE:9509) has just paired its half year earnings release with an increase in its interim dividend, even as net income moved lower compared with last year.
The recent earnings update and dividend lift have landed alongside a solid run in Hokkaido Electric Power Company's shares, with a 90 day share price return of 9.92% and a year to date gain of 4.27%. That short term strength sits on top of a 1 year total shareholder return of 8.79%. The 3 year and 5 year total shareholder returns of 97.21% and 174.35% suggest long term holders have already experienced very strong compounding, so the latest dividend decision and board actions are being read against an already powerful track record of value creation rather than a fresh turnaround story.
Scan beyond Hokkaido Electric Power Company and compare this dividend story with a curated 29 dividend fortresses that currently offers income profiles many investors are watching closely.
After a fresh dividend lift and a sharp earnings drop, Hokkaido Electric Power Company now trades with a clear gap between its current ¥1,147 share price and valuation estimates near ¥1,370. Is that discount justified?
Preferred P/E of 11.7x: Is it justified?
On the surface, Hokkaido Electric Power Company looks modestly priced, with a current P/E of 11.7x against a share price of ¥1,147 and analyst valuation estimates pointing closer to ¥1,370.
The P/E ratio compares what investors are paying today to each unit of earnings the business generates. For a regulated electric utility such as Hokkaido Electric Power Company, this yardstick often reflects how confident the market is in the durability of profits and the clarity of future cash generation rather than rapid revenue expansion.
Relative to the broader Japanese market on 13.1x earnings, the stock screens as cheaper. This suggests investors are not paying a premium for its current profit base. That said, compared with a peer group P/E of 10.5x, the shares look more expensive within the domestic utilities cluster, so buyers are accepting a higher earnings multiple than some sector alternatives.
The fair value P/E estimate of 14.1x points to a level that is materially higher than the present 11.7x. That gap signals the market is valuing Hokkaido Electric Power Company at a discount to where earnings could be priced if sentiment and fundamentals eventually line up with that fair ratio benchmark.
Explore the SWS fair ratio for Hokkaido Electric Power Company.
Result: Price-to-Earnings of 11.7x (UNDERVALUED)
Still, the Hokkaido Electric Power Company investment case could be knocked off course if regulated returns tighten or if capital spending needs exceed cash generation.
Find out about the key risks to this Hokkaido Electric Power Company narrative.
Another view using our DCF model
A second lens tells a different story. While Hokkaido Electric Power Company looks inexpensive on its 11.7x P/E compared with the Asian utilities average of 14.4x and its own 14.1x fair ratio, our DCF model points to a value near ¥996.57, below the current ¥1,147 share price. This raises the question of whether earnings based pricing is giving you a margin of safety or a false sense of comfort.
Look into how the SWS DCF model arrives at its fair value.
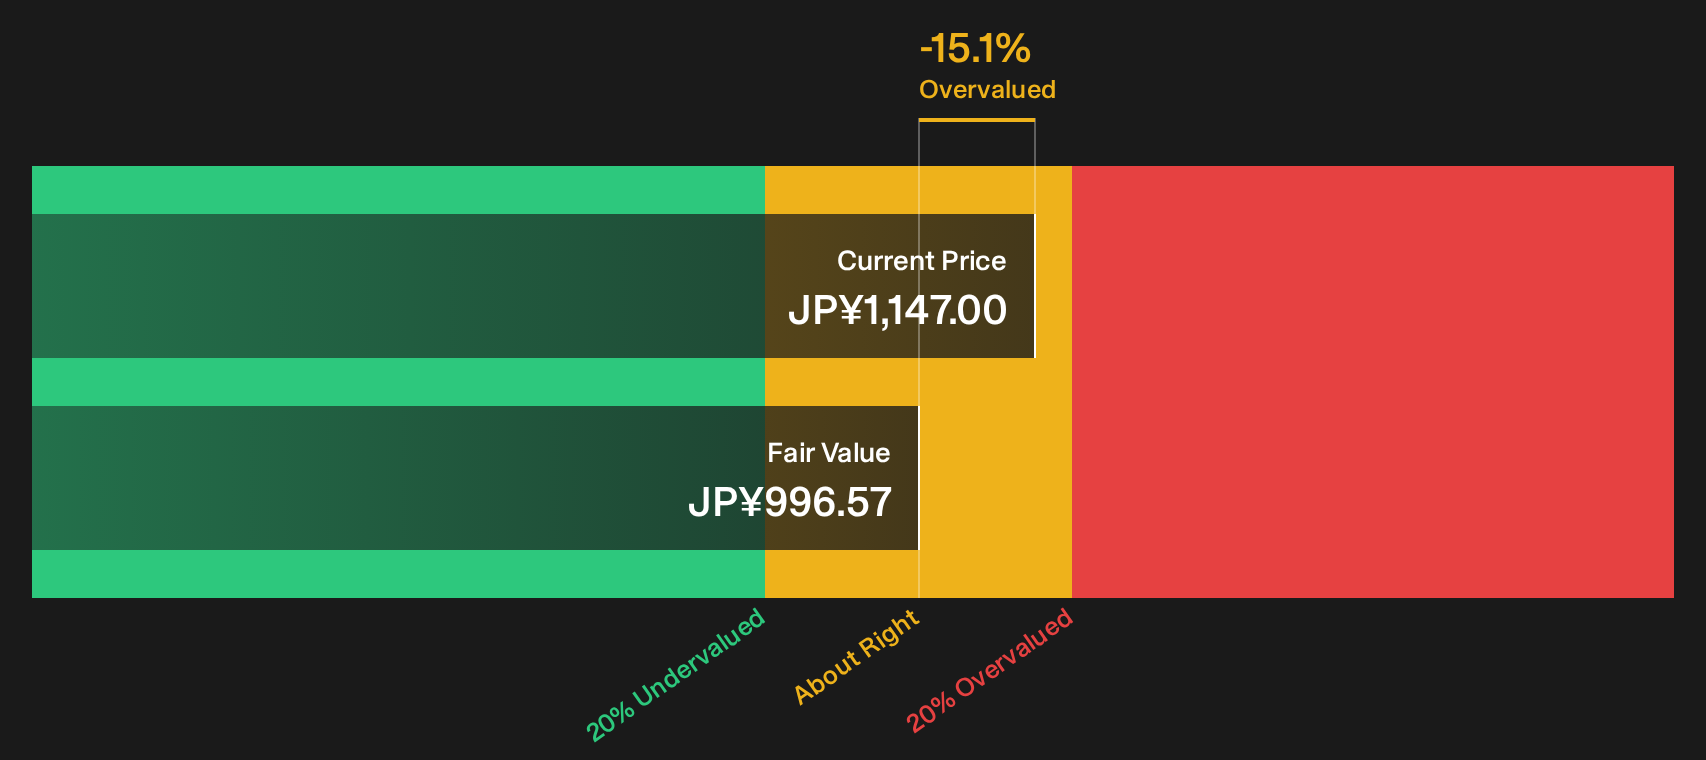
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hokkaido Electric Power Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 24 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading Hokkaido Electric Power Company's mixed signals on value and cash flows and wondering what really matters most for you as a shareholder right now? Act quickly, pull up the full picture, and weigh both the optimism and the caution by reviewing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Hokkaido Electric Power Company?
If Hokkaido Electric Power Company has sharpened your focus on valuation and income, do not stop here. Broader idea hunting can strengthen your portfolio decisions.
- Target resilient returns by scanning a 19 resilient stocks with low risk scores that many investors use when they want potential stability front and center.
- Hunt for mispriced quality with a focused 24 high quality undervalued stocks that surfaces companies combining attractive valuations with solid business fundamentals.
- Build a stronger income stream by reviewing a curated list of solid balance sheet and fundamentals (23 results) that highlights businesses aiming to pair dividends with financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com