


Cousins Properties (CUZ) is back in focus after its third quarter update, which showed higher sales, revenue, and net income compared with the same period in 2025, even as nine month earnings remained lower.
That quarterly beat has arrived alongside a share price of US$29.64 and a year to date share price return of 14.35%. Meanwhile, the 1 year total shareholder return of 19.13% and 3 year total shareholder return of 68.14% suggest momentum around Cousins Properties has been building rather than fading.
Scan beyond Cousins Properties and see how other real estate investment trusts with similar momentum and fundamentals line up in our hand picked list of solid balance sheet and fundamentals (23 results)
Cousins Properties now trades at what looks like a meaningful discount to both analyst targets and some fair value estimates, even after the recent run. Is the market rightly cautious, or is it mispricing the rebound story here?
Most Popular Narrative: 11.6% Undervalued
Cousins Properties is framed as undervalued in the analyst consensus Narrative on Simply Wall St, which places fair value at $33.55 versus the recent $29.64 share price, using a 7.93% discount rate to weigh future cash flows.
Consistent flight to high quality, amenitized office space, reflected in 49 consecutive quarters of positive second generation cash rent roll ups and net effective rents in 2026 that are 8.5% to 16.8% above 2025 levels, is giving Cousins Properties pricing power that can support higher rental revenue and cash NOI.
See why 3 investors see Cousins Properties as 12% undervalued.
Result: Fair Value of $33.55 (UNDERVALUED)
Still, the narrative around Cousins Properties can crack if Sun Belt office demand cools or if large lease expirations leave space sitting empty for longer.
Find out about the key risks to this Cousins Properties narrative.
Another View: Cousins Properties Through The Sales Lens
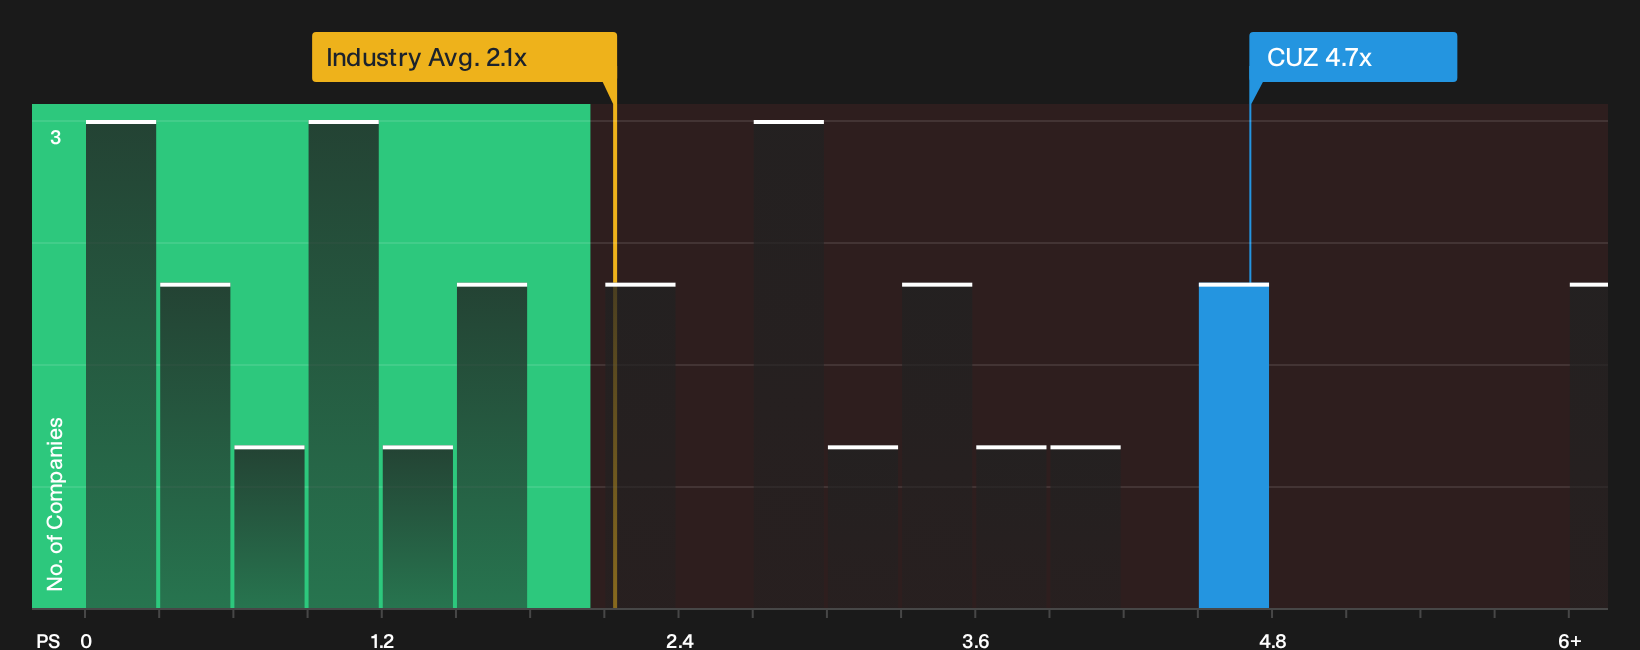
The cash flow work points to Cousins Properties trading at roughly a 35.2% discount to an estimated future cash flow value of $45.73. The picture looks different when you switch to the P/S lens. CUZ trades on 4.7x sales against 2.1x for the US Office REITs group and 4x for peers, while the fair ratio sits closer to 4.9x.
That mix of a premium to sector and peers, yet near the fair ratio, leaves an awkward question for investors. Is this setting up more as valuation risk if sentiment cools, or as compensation for CUZ’s specific portfolio and earnings outlook, compared with cheaper but slower moving REITs.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Cousins Properties so far, with both pressure points and bright spots showing up in the data, so move quickly and dig into the details that matter for you. To weigh those cross currents for yourself, start with the 2 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Cousins Properties?
If Cousins Properties has your attention, do not stop there. Use the Simply Wall St screener to quickly surface other potential opportunities that fit your approach.
- Target dependable income and stability by reviewing a focused 6 dividend fortresses that may suit investors who want yield plus resilience.
- Hunt for quality at a discount by scanning a curated 32 high quality undervalued stocks that aligns stronger fundamentals with potentially appealing prices.
- Prioritize capital protection by zeroing in on a 30 resilient stocks with low risk scores that filters for businesses with more defensive profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com