


Sezzle (NasdaqCM:SEZL) drew fresh attention on November 4 after reporting third quarter 2026 results with higher sales, net income and earnings per share, and raising its full year revenue growth guidance to 42.5%.
That earnings beat and guidance upgrade came on top of strong trading momentum, with a 1-week share price return of 11.68% and a 30-day gain of 16.99%. The year-to-date share price return of 134.31% and a 1-year total shareholder return of 166.45% suggest powerful recent enthusiasm for Sezzle that builds on a very large 3-year total shareholder return of around 79x.
See how Sezzle's surge compares with other fast-moving fintech and payment platforms by reviewing our curated list of 19 high quality undiscovered gems in the same broader space.
After a move this sharp, the real tension is between a Sezzle share price near US$153 and valuation estimates that still point higher. Where does fair value actually land in that spread?
Most Popular Narrative: 18.8% Undervalued
On the narrative view, Sezzle's fair value sits at $187.88, above the last close at $152.65. This frames the current market debate clearly. According to J_Tyrader, an investor in the Simply Wall St Community who wrote the narrative, the key question is how much growth and profitability the market is willing to price in.
On a two-stage model running 10 years of +25.0% growth fading to a 2.5% terminal rate, discounted at 14.5%, the shares are worth USD 187.88 against a market price of USD 111.38, a 41% discount, or +69% to fair value.
The business earns 52.4% on invested capital on a 40.4% operating margin struck against 74.6% gross margins. Of USD 531.89M in trailing revenue, 61.6% converts all the way to free cash flow, and the balance sheet carries debt at 0.52 times equity.
See why 3 investors see Sezzle as 19% undervalued.
Result: Fair Value of $187.88 (UNDERVALUED)
Still, two pressure points could puncture that Sezzle narrative quickly: a weaker than expected upcoming earnings print, or any restatement of the financial data underpinning the model.
Find out about the key risks to this Sezzle narrative.
Another View: What Sezzle's P/E Is Telling You
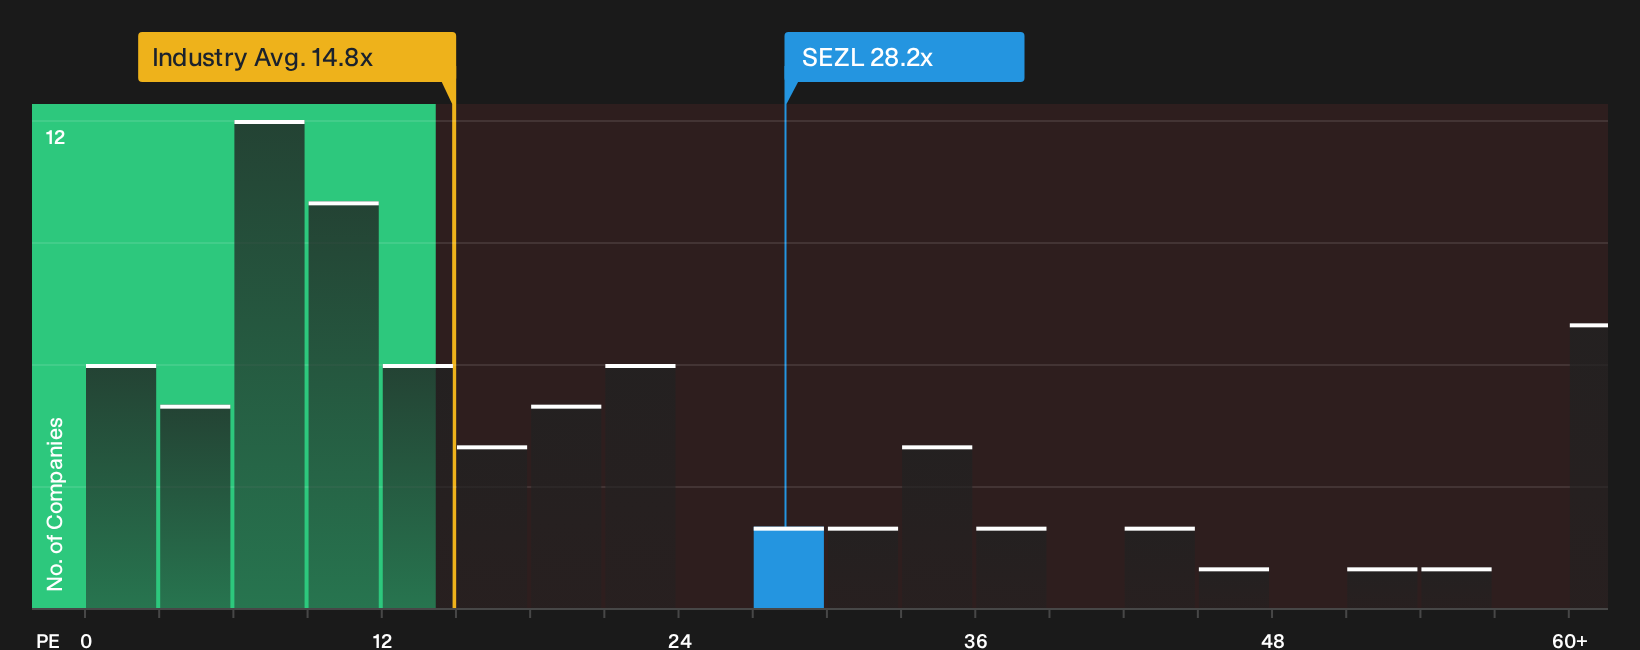
The Sezzle community narrative leans on a cash flow model that points to undervaluation. A simple P/E check paints a different picture. At 28.2x earnings versus a fair ratio of 18.2x, the stock carries a sizeable valuation premium.
Relative to the wider US Diversified Financial industry on 14.8x and a peer group around 33x, Sezzle sits in the middle. That mix of being above its own fair ratio yet below some peers suggests investors are already paying up for growth, leaving less room for error if expectations change.
To see how that gap between market P/E, fair ratio and peer pricing could affect your risk and return trade off, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Sezzle's valuation can be energising or uncomfortable, depending on your risk appetite. Act while the data is fresh and test the bullish and cautious angles against your own expectations through the 3 key rewards and 1 important warning sign.
Looking for more Sezzle style investment ideas?
If Sezzle has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist now or risk missing the next compelling setup.
- Target potential value opportunities by scanning a 32 high quality undervalued stocks that match strong fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that emphasise steadier balance sheets and lower overall risk profiles.
- Strengthen your core holdings by checking a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com