


- Cronos Group reported third quarter 2026 revenue of US$63.45 million and net income of US$13.8 million, with year to date net income of US$59.64 million compared with a loss in the prior period.
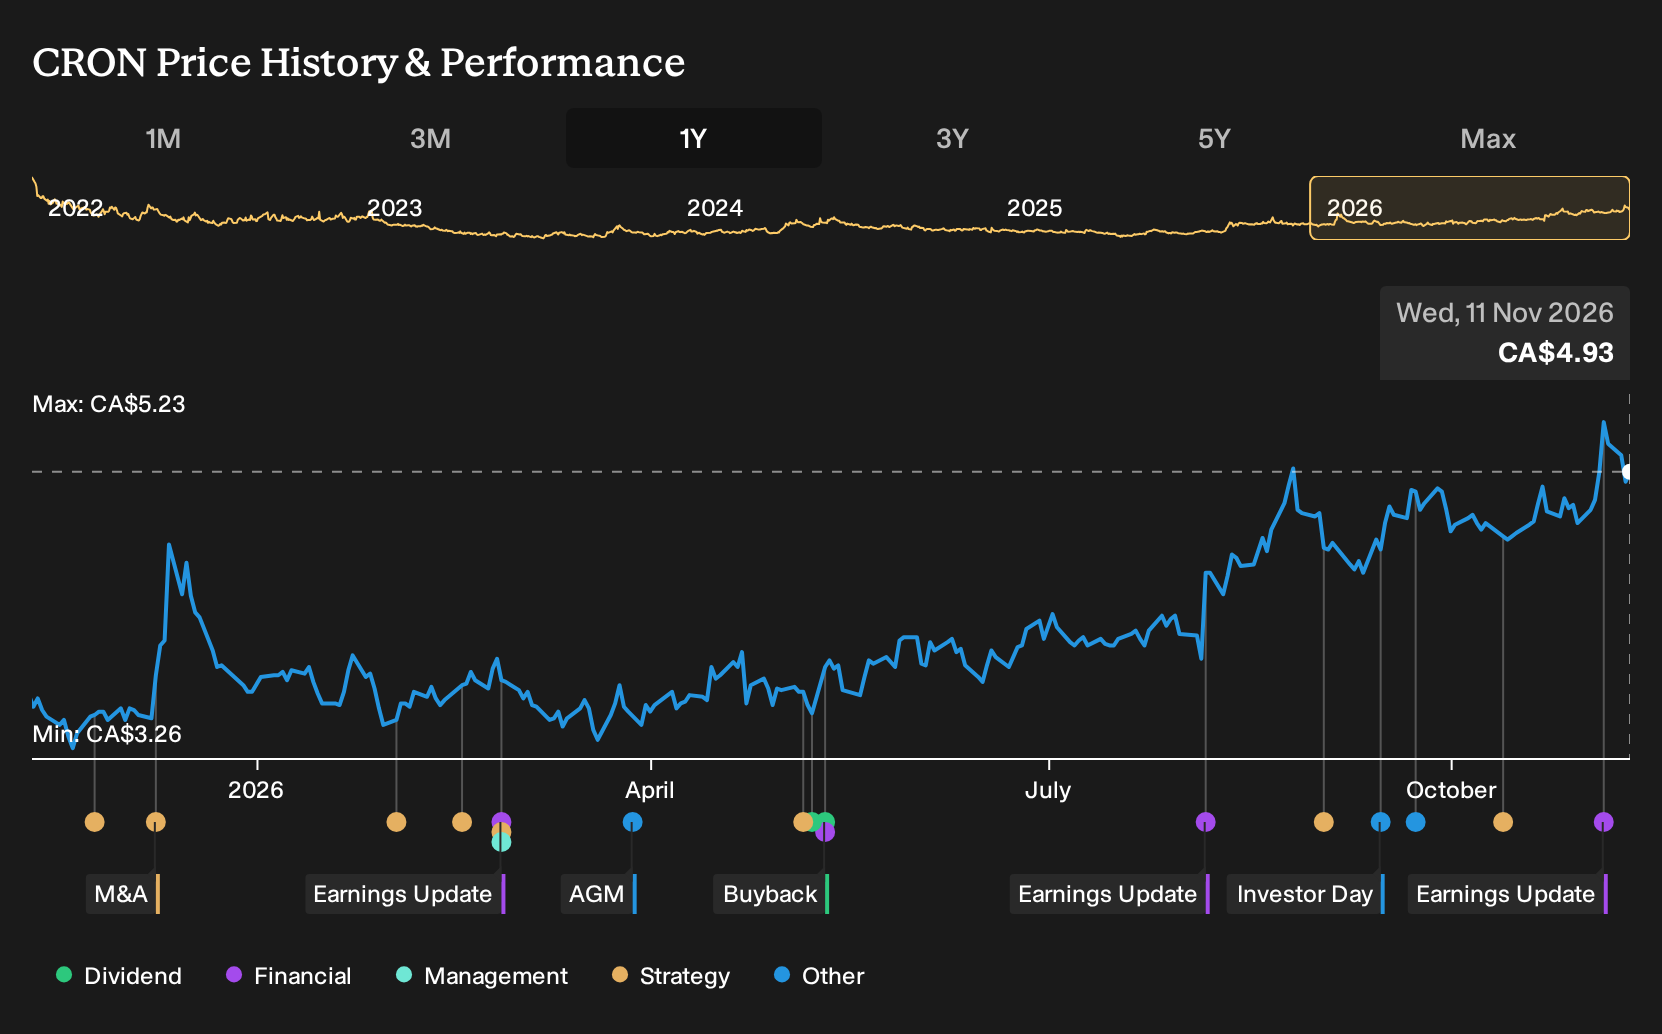
- The company completed a US$16.8 million share repurchase equal to 1.6% of shares while remaining net income positive, which tightens the share count and highlights its use of cash alongside expanding international operations.
- We will now look at how Cronos Group's investment narrative is influenced by the latest quarter of profitability and buybacks.
Scan other cannabis and consumer stocks showing real earnings progress and disciplined capital returns with the curated list of 16 elite penny stocks with strong financials that share some of Cronos Group's key financial traits.
Cronos Group Investment Narrative Recap
Cronos Group appeals to shareholders who buy into a simple idea. The business needs to keep turning branded cannabis demand in Canada and abroad into consistent earnings while using its cash rich balance sheet carefully. The analyst consensus Narrative on Simply Wall St focuses on genetics led production, brand strength and international expansion as the key ingredients.
The latest quarter keeps that story intact. Revenue and year to date profit stayed positive, which supports the short term catalyst around executing the GrowCo capacity build out and the CanAdelaar integration. The bigger risk is still operational, especially any setback at GrowCo or regulatory changes in Israel that hit export revenue and margins.
The most relevant update right now is the completion of the US$16.8 million buyback, which retired 1.6% of Cronos Group’s shares while the company remained net income positive. That is small in absolute size, yet it makes every remaining share a little more tightly tied to the current earnings base.
For catalysts, this capital return sits next to the large net cash position, ongoing positive adjusted EBITDA and the Dutch adult use exposure through CanAdelaar. Together these factors give Cronos Group several levers if operating trends hold. However, any future cash burn or weaker cash generation could reduce flexibility to keep funding expansion and similar repurchases.
What Analyst Forecasts Signal For Cronos Group
Cronos Group's narrative projects US$319.4 million revenue and US$88.7 million earnings by 2029. This assumes 21.3% yearly revenue growth and about US$18.7 million earnings increase from the current US$70.0 million earnings base.
Discover why Cronos Group's fair value indicates a 20% potential upside to its current price, which may materialize more quickly than many investors anticipate.
Exploring Other Perspectives
One optimistic angle on Cronos Group leans hard into CanAdelaar. The most bullish analysts were already modelling about US$369.0 million in revenue and US$115.9 million earnings by 2029 before this earnings beat and completed buyback. You can treat that as a ceiling scenario, and compare it with more cautious views to see how opinions might shift now.
Explore 2 other Cronos Group fair value estimates, including one that suggests as much as 224% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cronos Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cronos Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cronos Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cronos Group?
Once you have a view on Cronos Group, it can help to line it up against a few other stocks that share traits you care about, whether that is financial resilience, growth potential or income.
- If capital protection is a priority, start with sturdier balance sheets and lower risk profiles using the 9 resilient stocks with low risk scores as a filter for ideas that may suit a more cautious approach.
- For investors who want growth potential backed by solid finances, scan the 8 high quality undiscovered gems and see which under the radar businesses meet your quality and valuation checks.
- If steady income matters most, shortlist potential dividend payers by focusing on companies in the 3 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com