


Amkor Technology has delivered a long run of gains for shareholders, yet the current price around US$38.10 now raises a simple question for you as an investor: Are you paying a fair amount for the earnings power that this outsourced chip packaging and testing specialist is generating today?
- Over the past 5 years the stock has returned 66.7%, which puts real pressure on the current earnings multiple to justify that kind of wealth creation.
- The business model relies on turning semiconductor demand into profitable packaging and test work, so the durability of those margins may support or constrain how much earnings Amkor can produce relative to its price.
- The analysts covering Amkor Technology have run their own numbers. See what analysts think Amkor Technology's shares could be worth.
The issue now is whether Amkor Technology's current share price is appropriately aligned with the earnings the company is generating and expected to sustain.
To see whether this same earnings test points you toward other opportunities beyond Amkor Technology, scan the 32 high quality undervalued stocks for ideas that line up with your valuation checklist.
Is Amkor Technology a Bargain on Earnings?
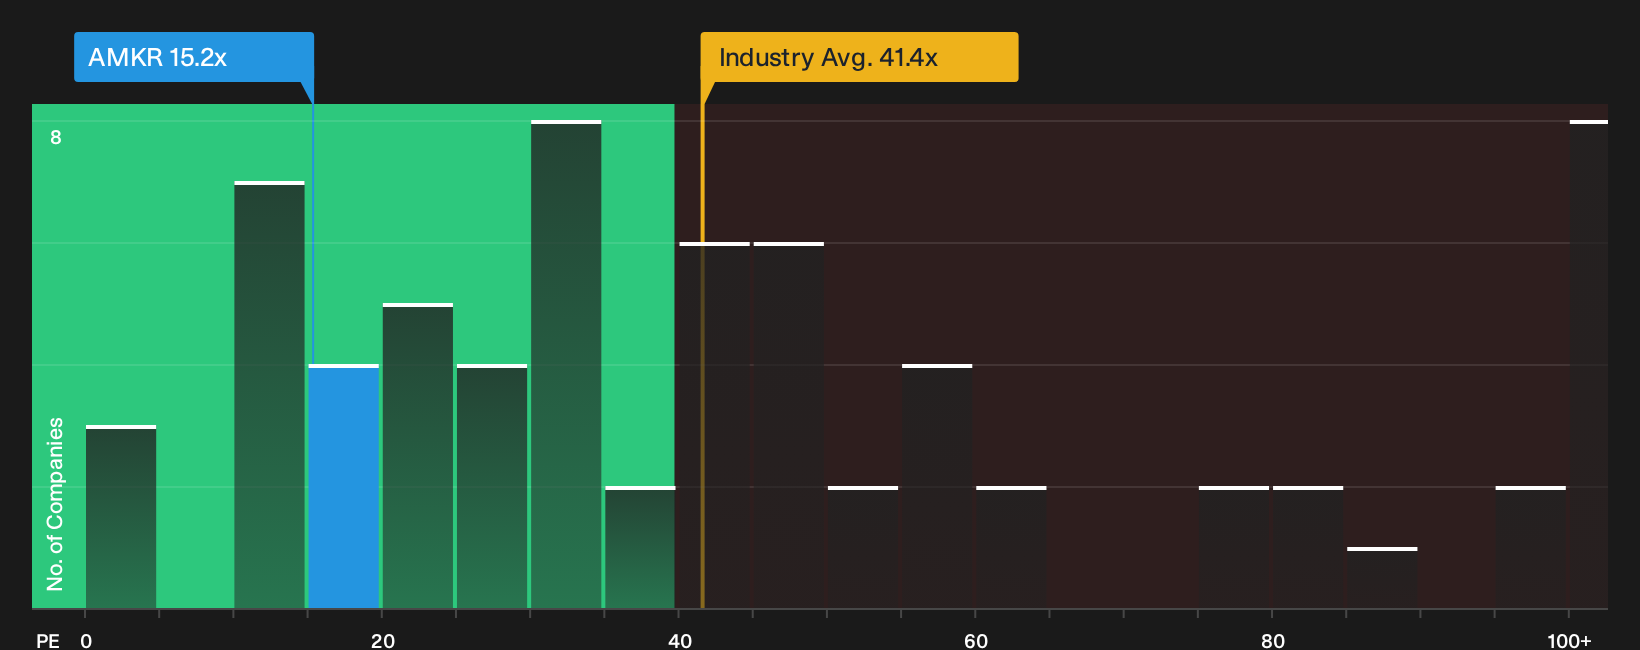
The P/E ratio is a useful fit for Amkor Technology because earnings are a key focus for a mature, capital intensive chip services business. At around 15.2x, the stock trades well below the semiconductor industry average P/E of about 41.4x and also below a peer group that clusters closer to 43.7x. That gap indicates the market is currently assigning a lower earnings multiple to Amkor than to many packaging and chip related stocks.
The Fair Ratio model, which blends factors such as growth expectations, profitability, sector context and risk profile, points to a higher P/E than the one the market is currently paying for Amkor Technology. On this framework the shares screen as undervalued on earnings. The key question for you is whether the company can keep converting its position in outsourced chip assembly into an earnings stream that justifies a richer multiple over time. Explore the numbers behind Amkor Technology's P/E valuation.
The Amkor Technology Narrative: What Would Justify Today's Price?
Narratives for Amkor Technology pick up where this valuation puzzle leaves off by explaining what kind of future path for growth, profitability and earnings would need to hold for the current P/E to appear either too low or too demanding. Rather than relying on a single multiple or model result, each scenario lays out the specific assumptions behind its view of fair value so you can track those expectations against actual results as they are reported on Simply Wall St's Community page.
One of the top narratives on Amkor Technology: 42% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Acceleration in AI data center and high performance computing programs, including HDFO CPU ramps and multiple 2.5D and high density fan out engagements, is increasing demand for advanced packaging…"
Discover why this Narrative puts Amkor Technology at 42% undervalued.
Amkor Technology’s valuation leaves one crucial piece of the puzzle unanswered
Price and earnings only tell part of the story, because the people setting priorities, capital allocation and risk appetite, and how they are rewarded for those choices, can tilt outcomes in ways the headline numbers never show. See who runs Amkor Technology and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com