


- Keurig Dr Pepper reported third quarter 2026 sales of US$7.344b and net income of US$882m, reaffirmed full year 2026 net sales guidance of US$25.9b to US$26.4b, and recently introduced the higher priced Keurig Alta at home coffee system with compostable AltaRounds pods.
- The combination of stronger quarterly earnings and the Keurig Alta launch with plastic free and aluminum free pods illustrates how Keurig Dr Pepper is attempting to balance demand for premium, café style drinks at home with growing consumer focus on waste reduction and product convenience.
- We will now examine how Keurig Dr Pepper's investment narrative is influenced by reaffirmed guidance alongside the Keurig Alta launch.
Scan how Keurig Dr Pepper's latest earnings and the Keurig Alta launch compare to peers by reviewing 19 high quality undiscovered gems with similar product momentum and solid fundamentals.
Keurig Dr Pepper Investment Narrative Recap
Keurig Dr Pepper asks you to believe that its beverage and coffee platforms can both carry their weight while the group reshapes into two focused businesses. The third quarter showed US$7.344b in sales and US$882m in net income, with full year 2026 net sales guidance reaffirmed at US$25.9b to US$26.4b, so the near term revenue story has not radically shifted.
The short term swing factor remains execution in U.S. Coffee and cost control, given earlier pressure from input costs and weaker pod volumes in that segment. The biggest risk is that coffee category strain, including competitive pricing and tariffs on green coffee or brewers, persists long enough to keep margins soft while leverage and separation work continue.
The launch of the Keurig Alta system is the clearest operational catalyst tied to these results. Alta introduces higher priced at home brewing hardware with compostable AltaRounds, and it remains compatible with existing K Cup pods. This extends the installed base rather than abandoning it and targets more premium, café style occasions.
For investors tracking the analyst consensus Narrative on Simply Wall St, Alta sits alongside the planned separation into Beverage Co and a global coffee focused company as a practical test of coffee execution. Uptake of a US$499.99 system and US$9.99 to US$10.99 pod packs, and how that mixes with existing pods, will matter for both volume resilience and how quickly Keurig Dr Pepper can offset cost and pricing pressure in its coffee operations.
Keurig Dr Pepper's current analyst storyline points to revenues of US$32.4b and earnings of US$3.2b by 2029, based on forecasts that assume about 11.9% yearly revenue growth and an earnings increase of roughly US$1.7b from US$1.5b today.
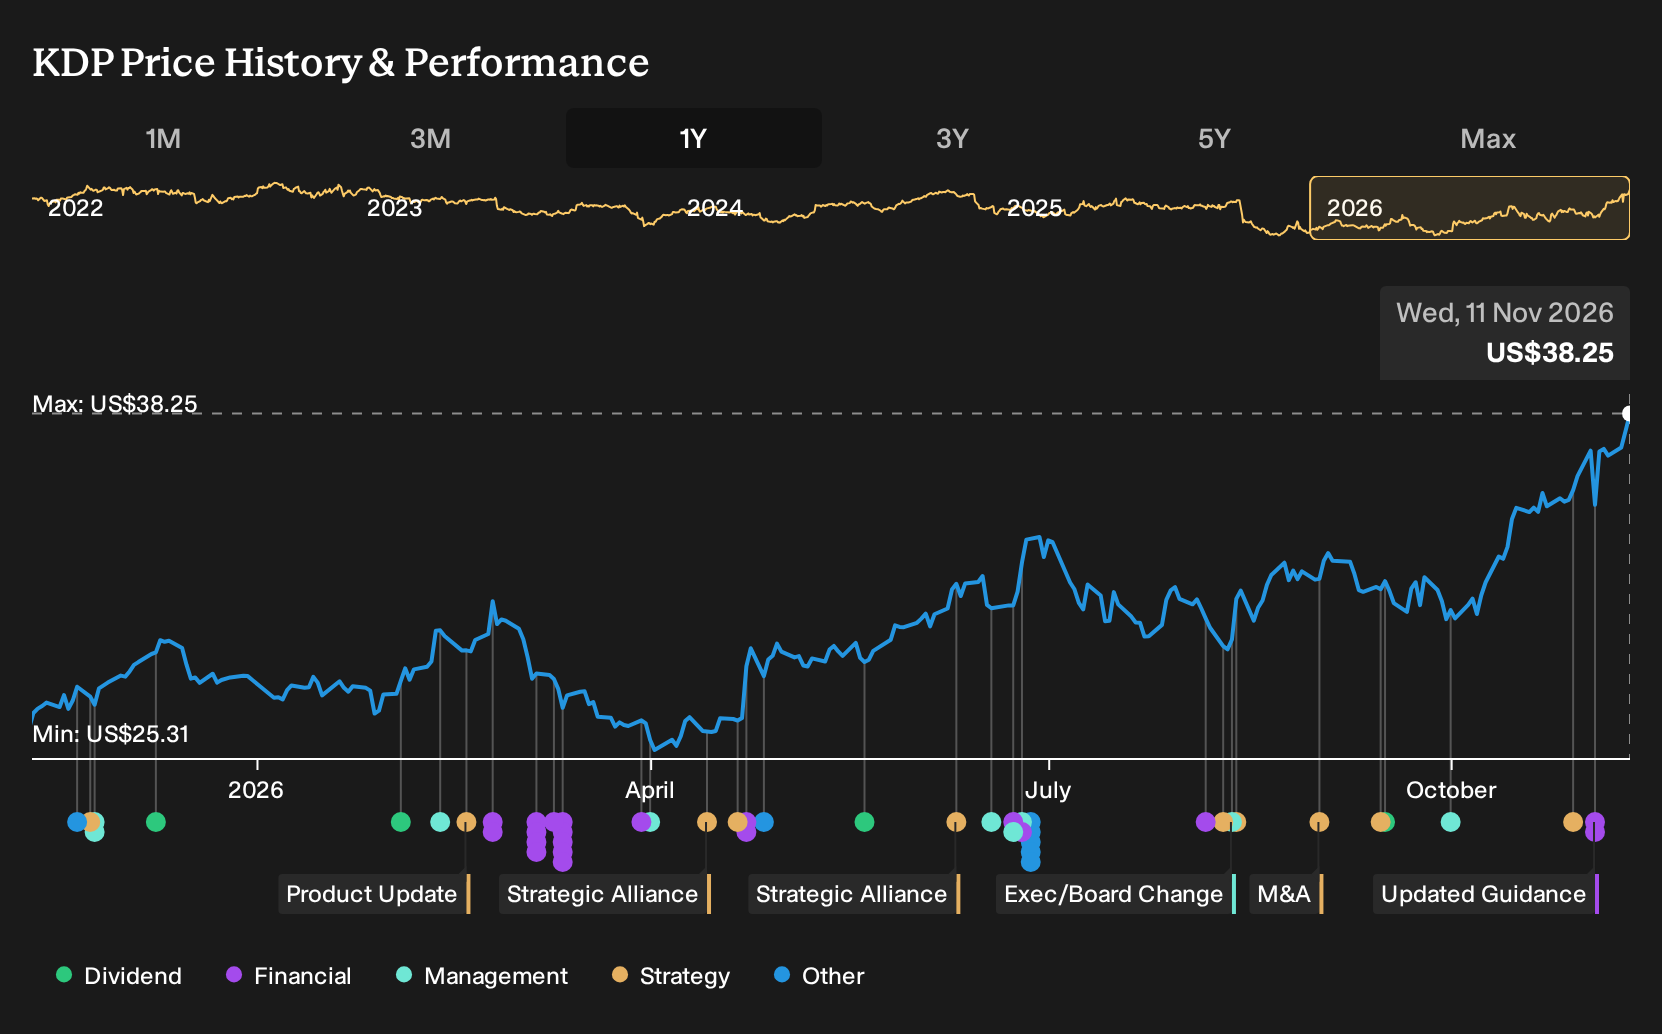
Uncover why Keurig Dr Pepper's fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community span a wide band, from US$35.50 at the low end to about US$103.50 at the top. Opinion on Keurig Dr Pepper is therefore far from settled. Set that against coffee segment cost pressure and the Alta rollout, and you are looking at genuinely different paths for future performance.
Explore 3 other Keurig Dr Pepper fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Keurig Dr Pepper research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Keurig Dr Pepper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keurig Dr Pepper's overall financial health at a glance.
Looking for more Keurig Dr Pepper investment ideas?
If the Keurig Dr Pepper story has sharpened your thinking, use that momentum to broaden your watchlist with other stocks that match the kind of balance sheet strength, income potential, or value profile you want to focus on next.
- For investors who want resilience first and potential upside second, scan a 30 resilient stocks with low risk scores that score well on both stability and fundamentals.
- If reliable income is a priority, review a curated set of 6 dividend fortresses that combine high yields with robust underlying businesses.
- To spot companies the market might be overlooking, browse a 19 high quality undiscovered gems that pair strong financial quality with under-the-radar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com