


Conference appearance puts Home BancShares in focus
Home BancShares (HOMB) is set to join a Fireside Chat at the Stephens Annual Investment Conference on November 17, 2026, giving investors a fresh window into management priorities.
The session with Centennial Bank includes a live webcast and a replay available for the past 3 months, which provides investors with an opportunity to review the bank’s recent performance metrics and capital deployment choices in greater detail.
Recent price action for Home BancShares has been mixed, with the share price easing 0.8% over the past week after a 6.0% gain across the last month. The 1-year total shareholder return of 13.8% and 3-year total shareholder return of 47.3% point to momentum that has built over a longer window as investors reassess both growth prospects and perceived risk around the bank ahead of events like the upcoming conference appearance.
Scan beyond Home BancShares and evaluate other regional financials, which could be setting up for the next leg higher, with our curated 30 resilient stocks with low risk scores
After a punchy 1 year and 3 year run, while the latest 90 day pullback has cooled things a little, does Home BancShares still offer a risk reward profile that tilts in buyers’ favour at around $30?
Most Popular Narrative: 9% Undervalued
On the analyst consensus Narrative on Simply Wall St, Home BancShares is framed as undervalued, with a fair value of $33.25 versus the latest $30.21 close and a discount rate of 7.24% anchoring that view.
The main factor that has to go right is that Home BancShares maintains its conservative underwriting, strong capital and reserve position, and disciplined loan and deposit pricing while continuing to execute earnings accretive bank deals like Mountain Commerce and associated share repurchases.
See why 2 investors see Home BancShares as 9% undervalued.
Result: Fair Value of $33.25 (UNDERVALUED)
Still, the Home BancShares story can unravel if loan growth turns choppy again or if future acquisitions like Mountain Commerce prove harder to integrate cleanly.
Find out about the key risks to this Home BancShares narrative.
Another Look At Home BancShares Valuation
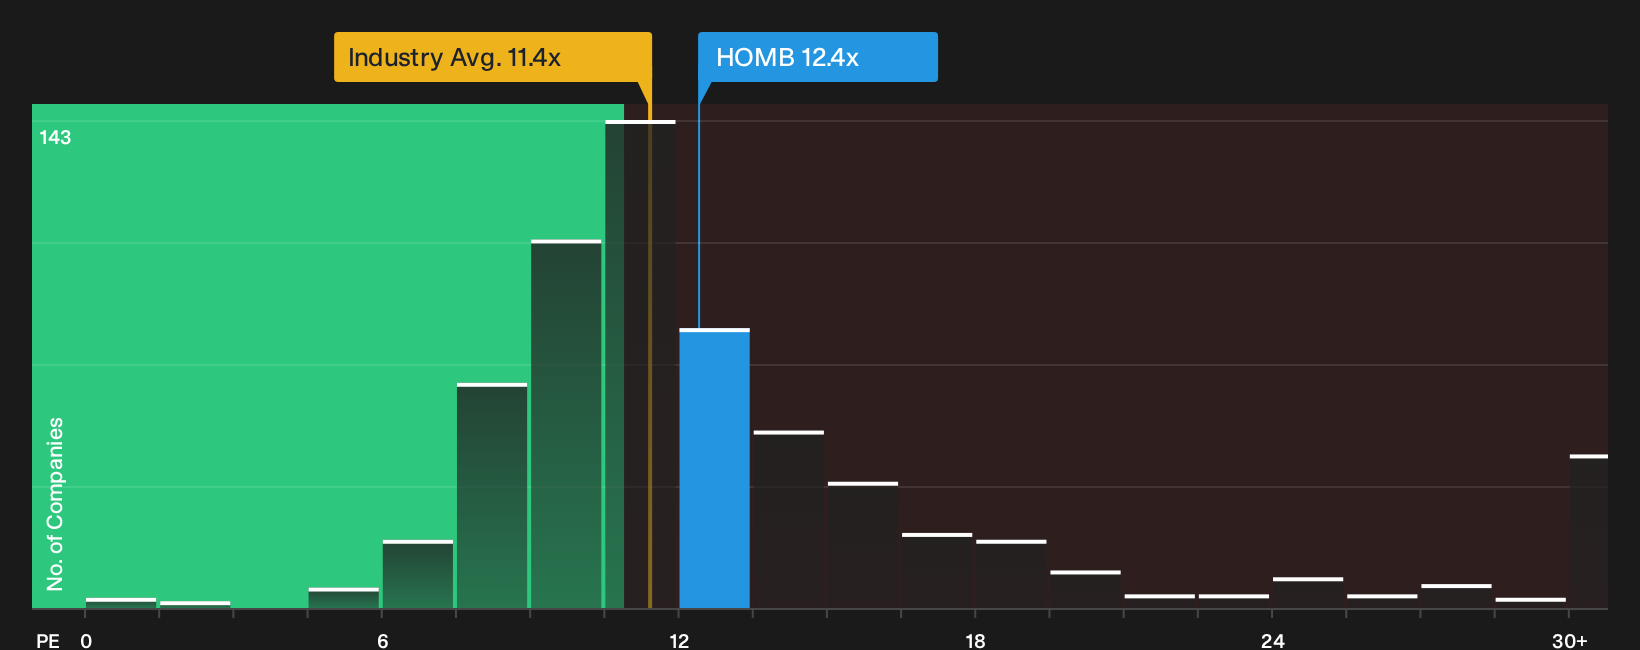
Analyst narratives often focus on discounted cash flows and future earnings targets, yet the current market price for Home BancShares can look different when viewed through straightforward P/E math. The shares trade on a P/E of 12.4x versus 11.4x for peers, while the fair ratio is 11.5x.
That premium suggests investors already pay more for the bank relative to the sector and where the fair ratio sits. This can reduce the margin for error if growth or returns soften. The key question is whether you view that gap as a sign of resilience being reflected in the price, or as room for the multiple to move closer to the fair ratio over time.
To compare this view with the current numbers, use the valuation breakdown to see what the market might be assuming at different earnings and P/E combinations See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of data points on Home BancShares pull in different directions, so do not sit on the fence when you can test the numbers yourself and weigh both caution and optimism with the full 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Home BancShares?
If Home BancShares has your attention, consider broadening your watchlist with a few focused stock ideas that emphasize quality, value and income potential.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (23 results) for potential anchors in a choppy market.
- Look for potentially mispriced quality by reviewing the 19 high quality undiscovered gems that pair solid financials with quieter market attention.
- Explore ways to support your income stream by checking companies in the 6 dividend fortresses that focus on yield with backing from their underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com