


Lamar Advertising (LAMR) updated its 2026 earnings outlook and released third quarter numbers, giving investors fresh data on profitability, revenue trends and how current operations align with full year expectations.
The guidance upgrade and solid third quarter arrive after a strong run in the stock, with Lamar Advertising’s share price up 31.02% year to date, supported by a 33.75% 1 year total shareholder return. The 94.63% 3 year total shareholder return signals sustained momentum rather than a short lived spike.
Scan how Lamar Advertising’s guidance revision compares to other real estate players by checking hand picked list of solid balance sheet and fundamentals (23 results) aligned with consistent earnings profiles.
After a run like this and fresh guidance on the table, Lamar Advertising now sits at a very different entry point. Is the current valuation still offering enough reward for the risk you are taking?
Most Popular Narrative: 0% Overvalued
Lamar Advertising last closed at $162.62, almost exactly in line with the analyst consensus Narrative on Simply Wall St, which assigns a fair value of $162.20 using a 7.97% discount rate and detailed earnings and revenue forecasts.
The main thing that has to go right is that Lamar Advertising successfully executes on its margin and capital allocation playbook, including sustaining high EBITDA margins while deploying over US$1b of investment capacity into tuck in M&A, UPREIT deals, and land and easement purchases without eroding returns.
The current narrative that Lamar Advertising is undervalued implies the share price does not fully reflect its record 49.2% EBITDA margin, raised 2026 AFFO per share and dividend guidance, and balance sheet capacity for further acquisitions and shareholder returns.
See why 18 investors see Lamar Advertising as 0% overvalued.
Result: Fair Value of $162.20 (ABOUT RIGHT)
Still, higher acquisition related expenses and ongoing equity issuance could pressure Lamar Advertising’s margins and dilute returns, which may challenge the current fair value narrative.
Find out about the key risks to this Lamar Advertising narrative.
Another View On Lamar Advertising’s Value
While the Simply Wall St fair value Narrative pegs Lamar Advertising close to $162 on earnings forecasts and a target P/E of 27.3x, the in house DCF work paints a very different picture. That model values future cash flows at $248.41 per share, which implies the stock trades at a sizeable discount.
The SWS DCF model is not a crystal ball. It simply weighs long term cash generation more heavily than near term multiples. If both frameworks are based on reasonable inputs, the gap between $162 and $248.41 becomes the real question for you as an investor.
Look into how the SWS DCF model arrives at its fair value.
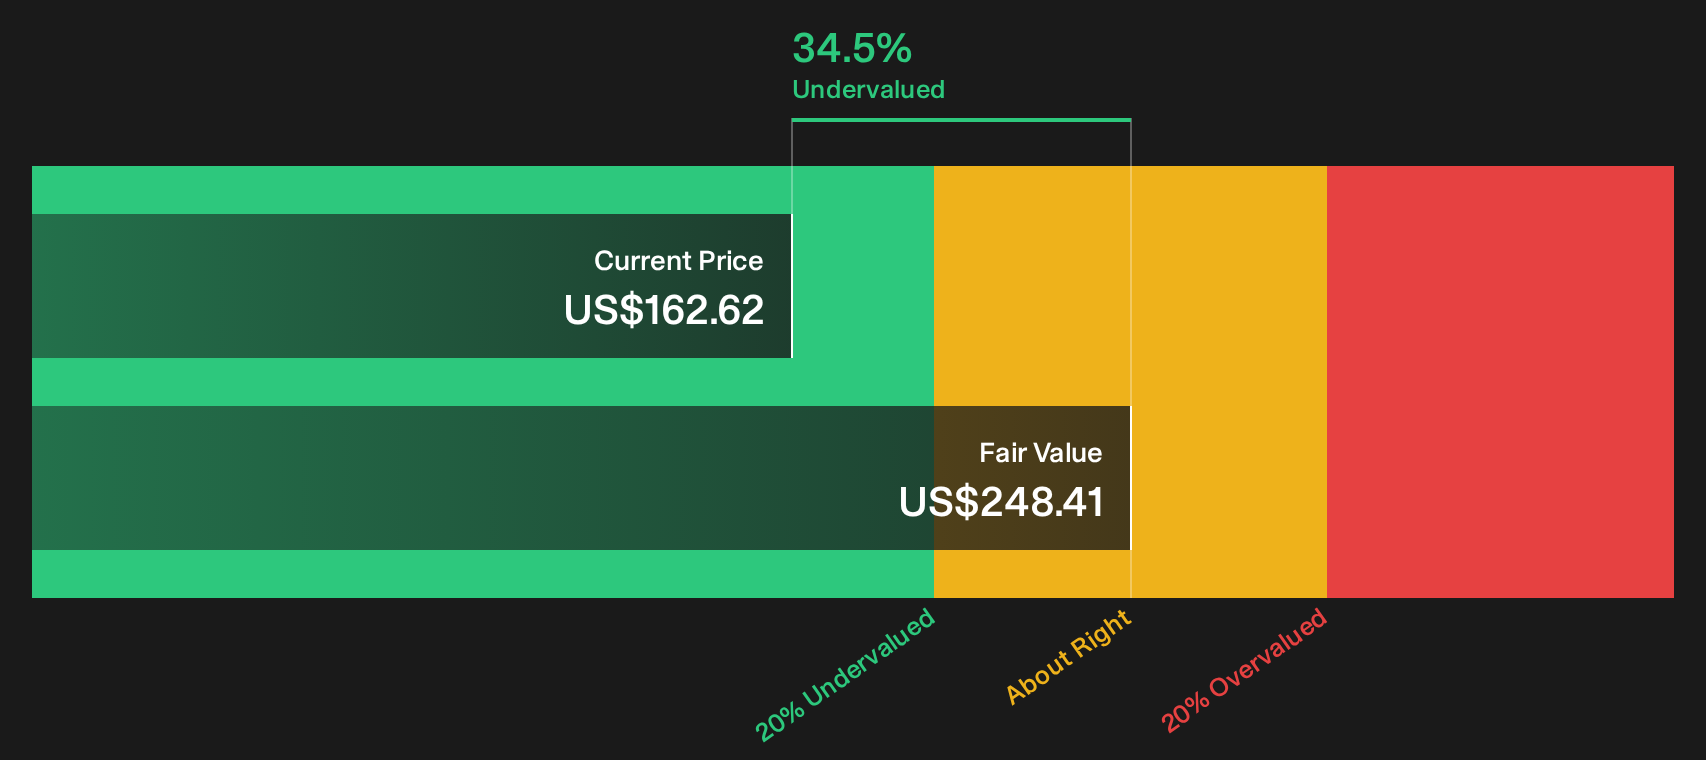
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lamar Advertising for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does this mix of enthusiasm and caution match your own read on Lamar Advertising, or does the gap in narratives feel too wide to ignore? Move quickly, review the full risk and reward breakdown, and stress test your thesis against the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Lamar Advertising?
If Lamar Advertising’s setup has you thinking harder about risk and reward, you could broaden your opportunity set with a few focused screens on Simply Wall St’s tools.
- Target steadier compounding by scanning a 30 resilient stocks with low risk scores that emphasises resilient balance sheets and historically less volatile share price behaviour.
- Hunt for potential mispricings by running a 32 high quality undervalued stocks built around quality fundamentals paired with what may be conservative expectations.
- Build a watchlist of potential future leaders by filtering through a 19 high quality undiscovered gems that highlights strong financial traits outside the usual spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com