


With a market cap of $216.9 billion, American Express Company (AXP) is a global payments and premium lifestyle company that leverages technology to deliver differentiated financial products, services, and experiences to consumers and businesses worldwide. The company has built its brand around trust, security, innovation, and premium membership value, serving millions of customers and merchants through its global network.
Shares of the credit card and payments company have lagged behind the broader market over the past 52 weeks. AXP stock has decreased 12.7% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 11.3%. Moreover, shares of the company are down 12.7% on a YTD basis, compared to SPX’s 11.3% gain.
In addition, shares of the New York-based company have underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 10.2% return over the past 52 weeks.
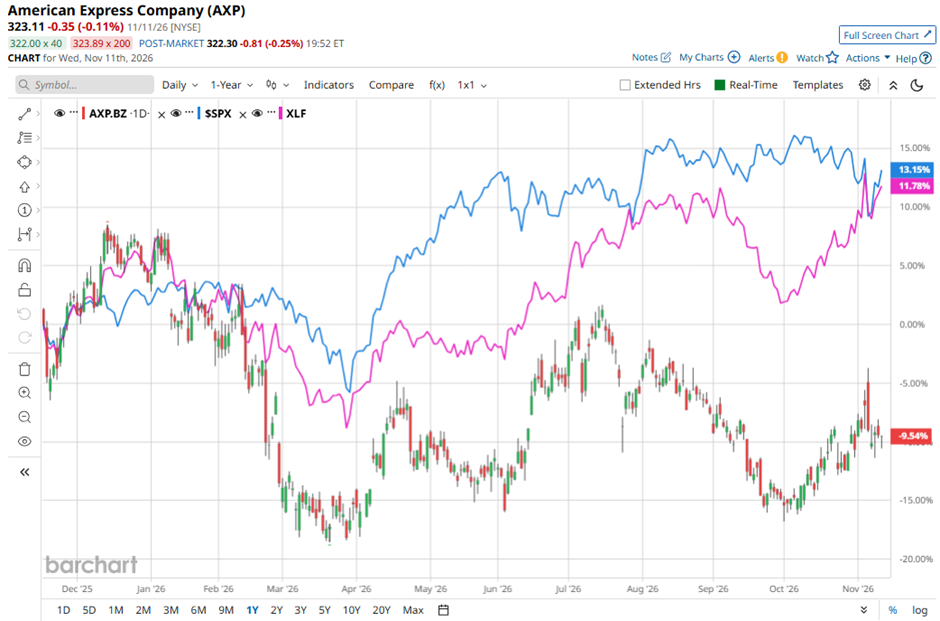
American Express shares fell 3.7% on Oct. 23 as investors focused on weaker-than-expected payment activity, with Q3 2026 total network volume of $517.9 billion missing the consensus, while year-over-year growth slowed to 8% from 9% in Q2 and billed business growth also decelerated to 8% from 9%. Despite adjusted EPS of $4.68 beating the estimate and revenue of $20.1 billion meeting expectations, the slowdown in network volume and spending growth raised concerns about weakening cardholder activity.
For the fiscal year ending in December 2026, analysts expect American Express’ adjusted EPS to grow 16.9% year-over-year to $17.98. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 30 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on 14 “Strong Buy” ratings, two “Moderate Buys,” and 14 “Holds.”
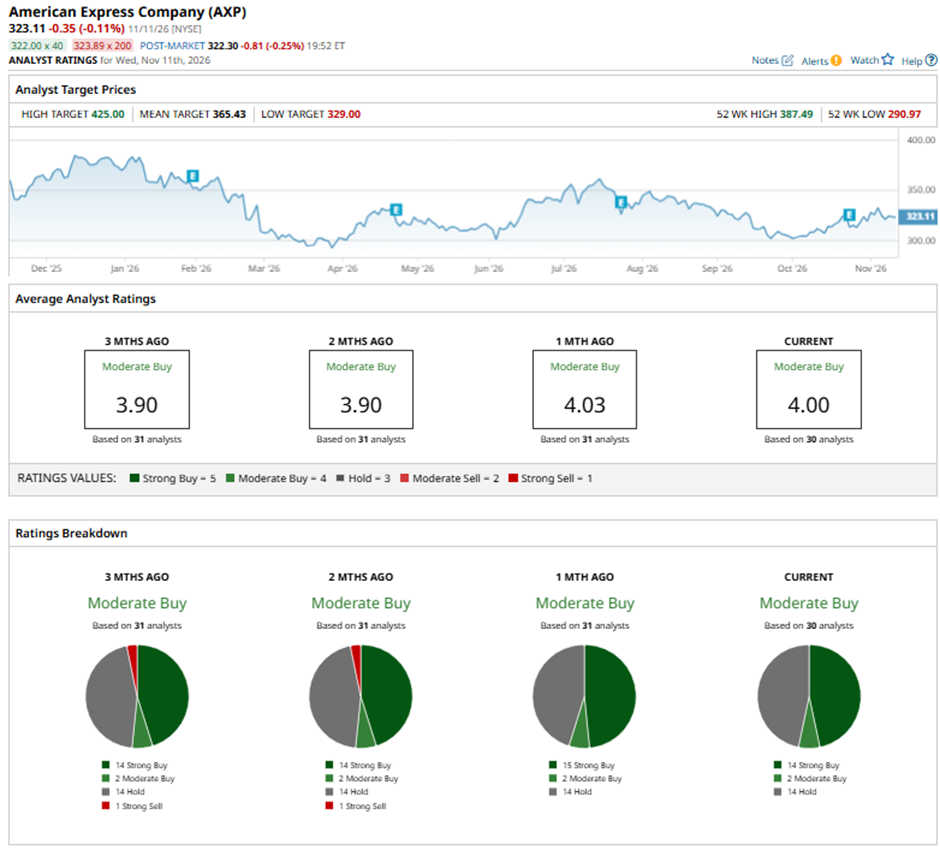
This configuration has remained unchanged over the past three months.
On October 23, RBC Capital analyst Jon Arfstrom maintained a “Buy” rating on American Express, with a price target of $400.
The mean price target of $365.43 represents a 13.1% premium to AXP’s current price levels. The Street-high price target of $425 suggests a 31.5% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.