


Costco Wholesale has delivered a powerful run over the past several years, and recent headlines around a large special dividend and buyback program have kept the stock in focus. With that backdrop, the live question for investors is whether the current share price is adequately supported by Costco Wholesale's earnings profile.
- Over the past 5 years the stock has gained 116.8%, which puts real pressure on the earnings story to explain how much of that move is rooted in profit power rather than sentiment.
- The planned US$30 per share special dividend and US$4b repurchase authorization signal confidence in Costco Wholesale's cash generation, which can shape how investors think about the durability and timing of future earnings that are meant to justify today's valuation.
- There is a second opinion on Costco Wholesale worth weighing. See what analysts think Costco Wholesale's shares could be worth.
The stock's next move may depend on whether Costco Wholesale's current earnings are strong enough to justify the price implied by that recent performance.
If you want more context for Costco Wholesale's run and the special dividend story, compare it with other resilient retailers filtered through the 30 resilient stocks with low risk scores.
Has Costco Wholesale Run Too Far on Earnings?
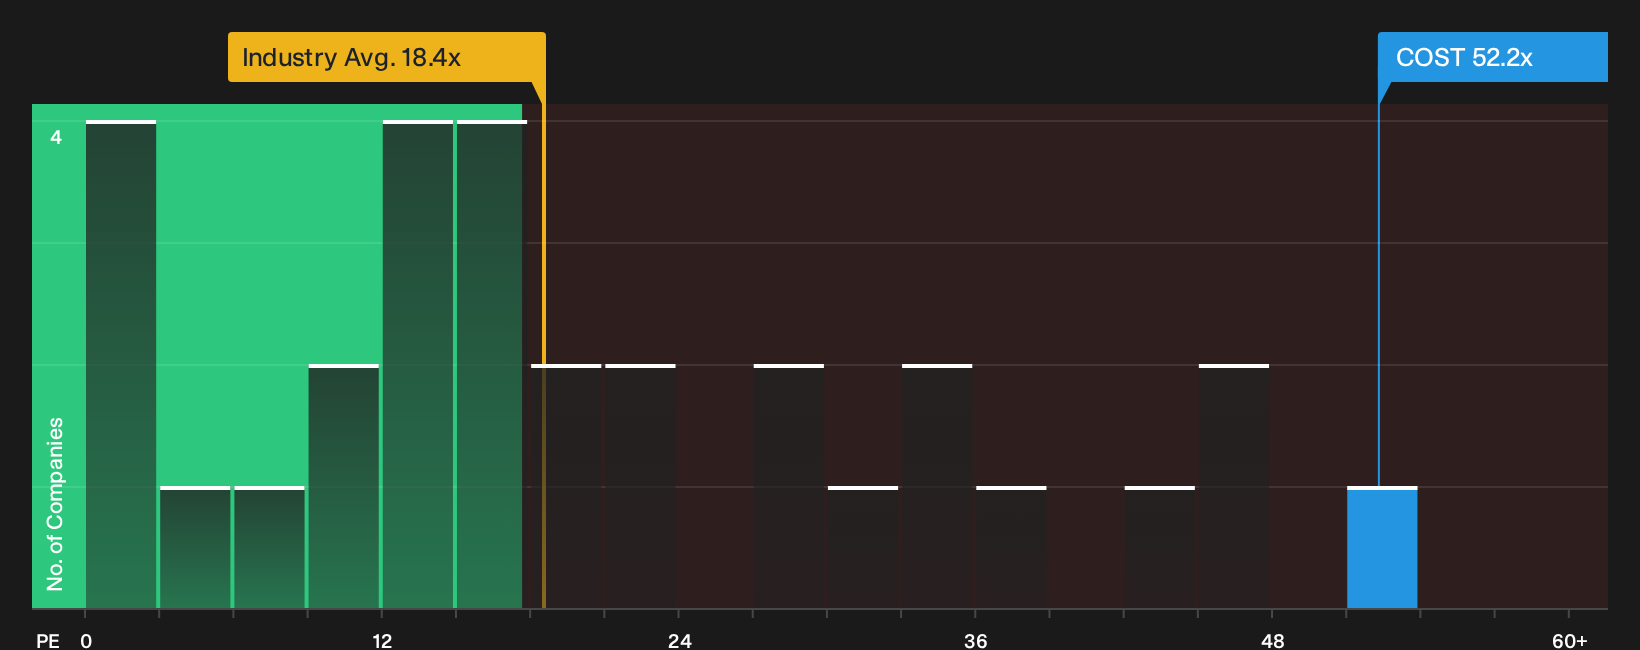
The P/E ratio fits Costco Wholesale because investors often weigh earnings power heavily for established retailers. On this yardstick, the stock trades on about 52.2x earnings, which is far above the Consumer Retailing industry average of roughly 18.4x and also well ahead of the peer group near 24.1x. That gap means buyers today are paying a much richer price for each dollar of Costco Wholesale profit than for many similar businesses.
There is also a more tailored benchmark that blends Costco Wholesale's growth profile, margins, scale and risk into an expected P/E, and the current 52.2x sits above that reference point, so the shares screen as overvalued on this framework. Despite the planned US$30 special dividend and US$4b buyback underlining strong cash generation, the market is already attaching a premium valuation that assumes a lot from future performance. For readers, the key question is whether Costco Wholesale's earnings quality and resilience justify paying this level of multiple for the stock today. Explore the numbers behind Costco Wholesale's P/E valuation.
The Costco Wholesale Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Costco Wholesale pick up where this valuation puzzle leaves off, as they explain what future growth, margin and earnings paths would need to look like for the stock to trade meaningfully above or below today's level. They are available on the Community page. Each narrative links a specific fair value estimate to a clear story about Costco Wholesale's possible catalysts and risks so you can track which version of events appears to be unfolding over time.
Bulls and bears are reading the same Costco Wholesale metrics and coming to sharply different conclusions about how much is already priced in.
Bull case: 29% undervalued
According to Follower, an investor in the Simply Wall St Community, the Costco Wholesale story starts with the membership engine and pricing model.
"Costco’s biggest strengths are its ultra-sticky memberships (~90% renewal), strong pricing power, and inflation-resilient “low-price leader” model…"
Discover why this Narrative puts Costco Wholesale at 29% undervalued.
Bear case: 50% overvalued
TibiT, a Simply Wall St Community investor who wrote the Narrative, focuses on what happens if Costco Wholesale is already "priced for perfection."
"With a P/E near 50x, the market assumes double-digit growth is guaranteed, even decent operational performance can result in poor shareholder returns…"
Explore why this Narrative puts Costco Wholesale at 50% overvalued.
One more Costco Wholesale check that sits outside the earnings story
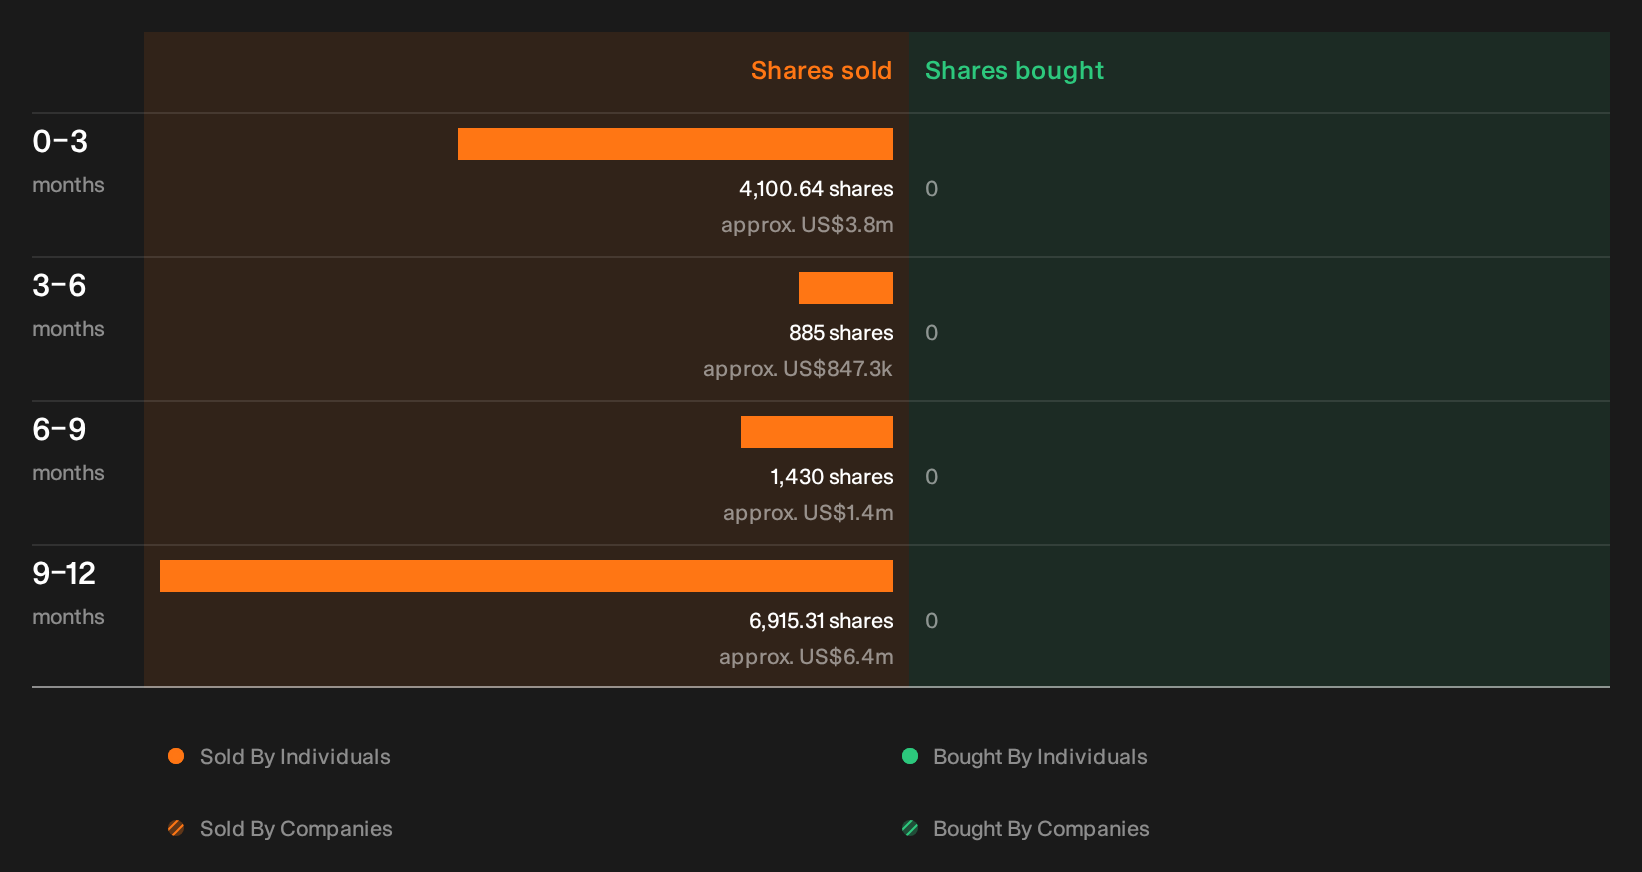
Share price and profit multiples are only part of the Costco Wholesale picture, because the recent insider trading patterns our checks picked up leave an important set of seller details and context for you to review. See the recent insider selling flagged for Costco Wholesale.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com