


Walmart has delivered strong returns over the past several years, which puts a spotlight on whether the current share price around US$125.67 still lines up with what its earnings can support. With fresh investment plans, technology partnerships and regulatory scrutiny all in play, the question is how much of that earnings story is already embedded in the valuation.
- Over the past 5 years the stock has returned 182.7%, which raises the stakes on whether the earnings profile has kept pace with the move.
- The expanded US$6b automation rollout with Symbotic across distribution centers may support efficiency, margins and future profit capacity that investors could be trying to price in today.
- There is a second opinion on Walmart worth weighing. See what analysts think Walmart's shares could be worth.
The issue now is whether Walmart's current market value is appropriately supported by its earnings when you compare it with the Fair Ratio benchmark.
To pressure test Walmart's earnings story and its automation and AI push, it often helps to compare it with other businesses that have similar themes using 42 profitable AI stocks that aren't just burning cash.
Is Walmart Fairly Priced on Earnings?
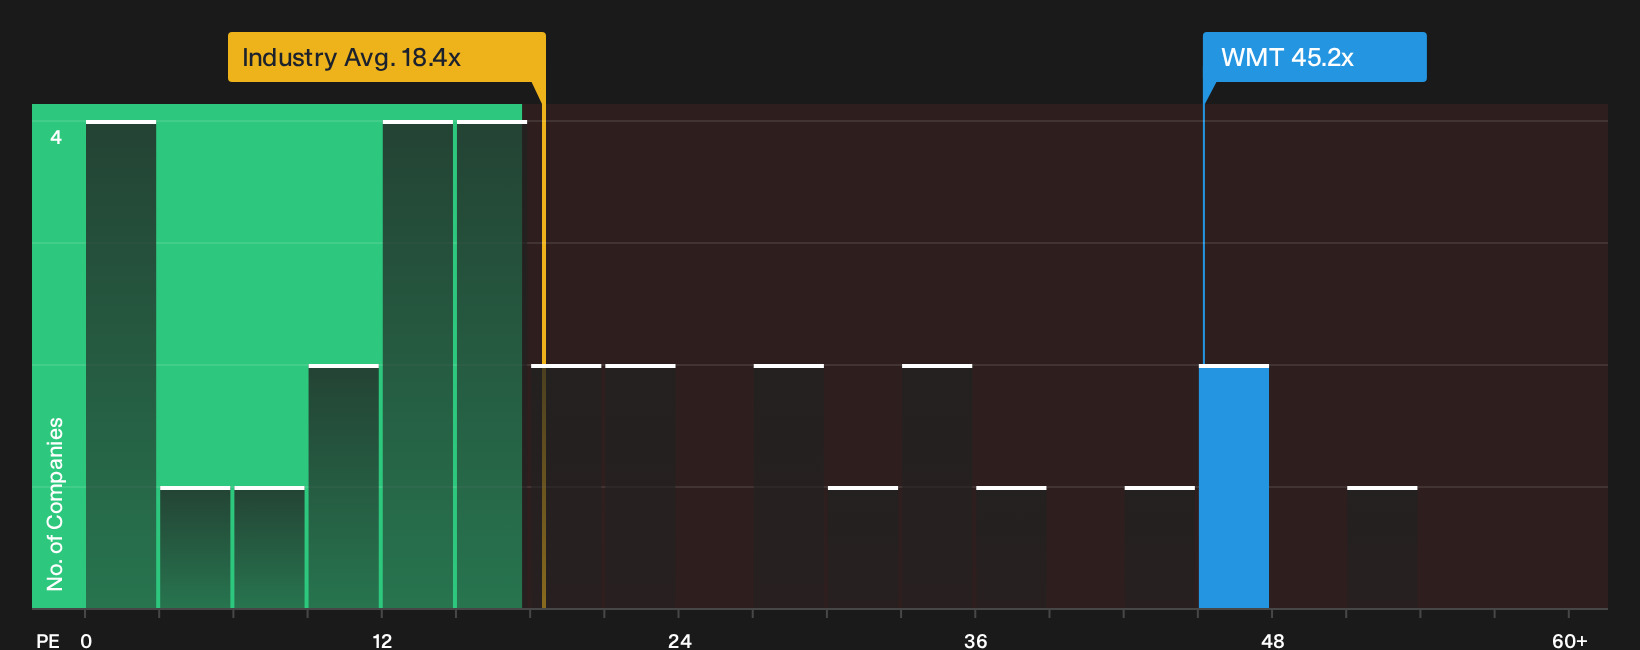
The P/E ratio fits Walmart because earnings are still the main anchor for how investors frame this retailer and its newer AI and automation efforts. Walmart trades on a P/E of about 45.2x compared with a Consumer Retailing industry average near 18.4x and a peer group around 25.9x, so buyers today are paying a materially richer price for each dollar of profit than they would for many large retail peers.
The Fair Ratio model, which aligns P/E with Walmart's specific mix of growth prospects, margins, scale and risk, points to a level slightly below the current earnings multiple. On this framework, the stock screens as about right overall rather than clearly cheap or expensive. Because the expanded US$6b automation rollout and broader AI push are front of mind for the market, that premium P/E already reflects a fair amount of optimism about what those initiatives might deliver over time. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Narratives for Walmart pick up where the valuation question leaves off, by spelling out which paths for growth, profitability and earnings would need to play out for the stock to justify a meaningfully higher or lower price than today. Rather than rely on a single P/E or model output, each storyline sets out its own fair value assumptions so you can compare those inputs with Walmart's reported results as they arrive on Simply Wall St's Community page.
One of the top community narratives on Walmart: 19% undervalued
According to prakhar_ef9px, a Simply Wall St Community investor who wrote this Narrative, Walmart’s "Other" segment is starting to matter more for the equity story.
"The SBU “Other” has emerged as a dynamic growth engine, capturing new opportunities beyond traditional retail, and leveraging innovation and agility to capture new market share…"
Discover why this Narrative puts Walmart at 19% undervalued.
One more angle on Walmart that could change how you see this stock
Everything so far has focused on what Walmart looks like today. However, professional coverage also sketches out where they expect earnings and cash flows to be a few years from now. Explore where analysts expect Walmart to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com