


CRISPR Therapeutics has been in the spotlight after a series of clinical updates and partnership news, yet the share price history raises a different question for investors who focus on hard assets and balance sheet strength. With the stock closing at US$45.75 and long term returns still in the red, the live issue is whether that market value can be squared with what the company’s book value supports.
- Over the past 5 years the stock has fallen 46.9%, which puts extra weight on the question of whether the current valuation is now more closely aligned with the equity the business has built up on its balance sheet.
- Recent positive trial data for zugo cel in autoimmune disease and early progress from therapies like Casgevy and CTX310 may support expectations for future revenue and capital needs, which can influence how much of a premium or discount investors are willing to place on CRISPR Therapeutics relative to its book value and the industry average.
- The analysts covering CRISPR Therapeutics have run their own numbers. See what analysts think CRISPR Therapeutics's shares could be worth.
The stock’s next move may depend on whether investors decide that today’s US$45.75 price is adequately backed by CRISPR Therapeutics’ book value when set against the industry average.
If you are weighing whether CRISPR Therapeutics at US$45.75 feels well supported by its book value, it can help to compare that question across solid balance sheet and fundamentals stocks screener (23 results).
Is CRISPR Therapeutics Getting Expensive on Book Value?
P/B fits CRISPR Therapeutics because investors often anchor early stage biotech valuations to the cash and other net assets on the balance sheet rather than current earnings.
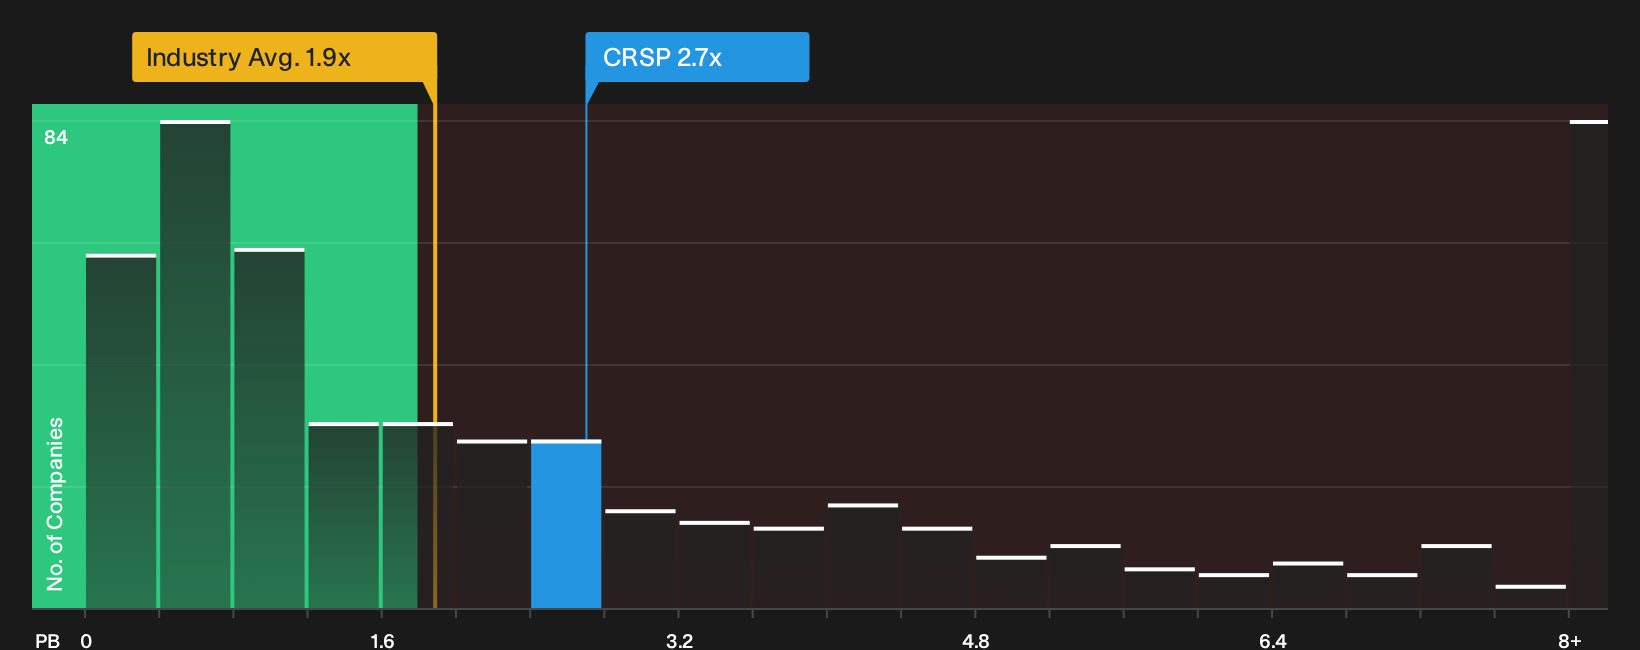
At a P/B of 2.7x, CRISPR Therapeutics trades above the Biotechs sector average of 1.9x and below the peer group average of 5.4x. The stock therefore screens as overvalued relative to the broader industry on this yardstick, even if it does not reach the richer end of specialist biotech peers.
Because the positive zugo cel data and updates around Casgevy and CTX310 have highlighted the pipeline in recent months, this premium to the industry average suggests investors are already paying up for that potential in relation to the company’s current equity base. For anyone weighing the shares, the P/B multiple mainly raises the question of whether the extra price over the sector’s 1.9x level feels justified once the risk, timelines and funding needs across CRISPR Therapeutics' portfolio are factored in. Explore the numbers behind CRISPR Therapeutics's P/B valuation.
The CRISPR Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the CRISPR Therapeutics valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to look much cheaper or much richer than today’s price. Each scenario links its number to a clear view on how CRISPR Therapeutics' growth, profitability and risk profile might evolve, giving you something concrete to revisit as fresh information arrives.
Bulls see CRISPR Therapeutics as a multi asset story in the making, while bears think the pipeline risk keeps the stock closer to fully priced.
Bull case: 38% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on a multi program late stage pipeline.
"Analysts expect CRISPR Therapeutics to build on CASGEVY revenue and move toward a multi-asset, multi-modality business as CTX310, CTX611, and zugo-cel advance…"
Discover why this Narrative puts CRISPR Therapeutics at 38% undervalued.
Bear case: roughly fairly valued
This angle is drawn from the bearish analyst Narrative on Simply Wall St, which focuses on execution risk and capital demands.
"Bearish analysts expect CRISPR Therapeutics to face slow commercial uptake for CASGEVY and execution risk across a broad gene-editing and siRNA pipeline despite its strong cash position…"
Explore why this Narrative puts CRISPR Therapeutics at roughly fairly valued.
CRISPR Therapeutics is more than today's share price tag
Valuation tells you what investors are paying today, but analyst projections for CRISPR Therapeutics over the next few years offer a different lens on how the story might evolve and where expectations really sit. Explore where analysts expect CRISPR Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com