


- Strathcona Resources reported third quarter 2026 revenue of C$1,260 million and net income of C$298 million, alongside total production of 123,486 boe/d and a quarterly dividend that was lifted 7% to C$0.32 per share.
- The board linked the higher dividend directly to production growth per share, signalling that Strathcona Resources is tying cash returns to operating delivery rather than headline commodity prices.
- We will look at how Strathcona Resources' investment narrative is shaped by the 7% dividend increase that follows stronger quarterly production.
Scan how Strathcona Resources’ latest production and dividend move compares with other income-focused operators by checking the hand picked 3 dividend fortresses in the same corner of the market.
Strathcona Resources Investment Narrative Recap
For Strathcona Resources, the big picture is about turning long life heavy oil assets into steady cash generation while keeping a close grip on costs and differentials. The latest quarter showed C$1,260 million in revenue and C$298 million in net income, with production at 123,486 boe/d. That operating base underpins near term execution on projects like Meota and export options. The analyst consensus Narrative on Simply Wall St focuses on earnings growth forecasts, but the recent numbers highlight that quarterly results can move around.
The most important short term catalyst still looks operational rather than financial. Delivery against production targets, including the ramp up of Meota Central and any early signs around new export routes, is what really tests the story. The biggest immediate risk remains exposure to oil prices and heavy oil differentials, which influence free cash flow and dividend coverage. The Q3 figures do not remove that risk, although the higher production per share gives the business a bit more breathing room if differentials worsen.
The dividend increase to C$0.32 per share sits at the center of this earnings update. Management tied the 7% bump directly to production growth per share rather than spot pricing, which is consistent with the idea that operating delivery should decide how much cash is returned to shareholders. That alignment matters if you are tracking catalysts around Meota, the 300,000 bbl/d by 2035 plan, and potential new marketing routes.
The same dividend decision also highlights the key risk flagged in the analyst consensus Narrative on Simply Wall St. Oil prices and heavy oil differentials still influence the free cash flow that funds this payout. If differentials widen for an extended period or benchmark prices soften, coverage for that higher dividend could come under pressure, which would quickly affect how investors view both the production growth plan and any future capital returns.
Strathcona Resources' current earnings are CA$427.0 million and the analyst consensus points to CA$1.4 billion of earnings on CA$4.3 billion of revenue by 2029, which implies revenue growth of 1.6% per year and an earnings increase of roughly 3 times from today by that same forecast year.
Uncover why Strathcona Resources' fair value indicates a 42% potential upside to its current price that may not last much longer.
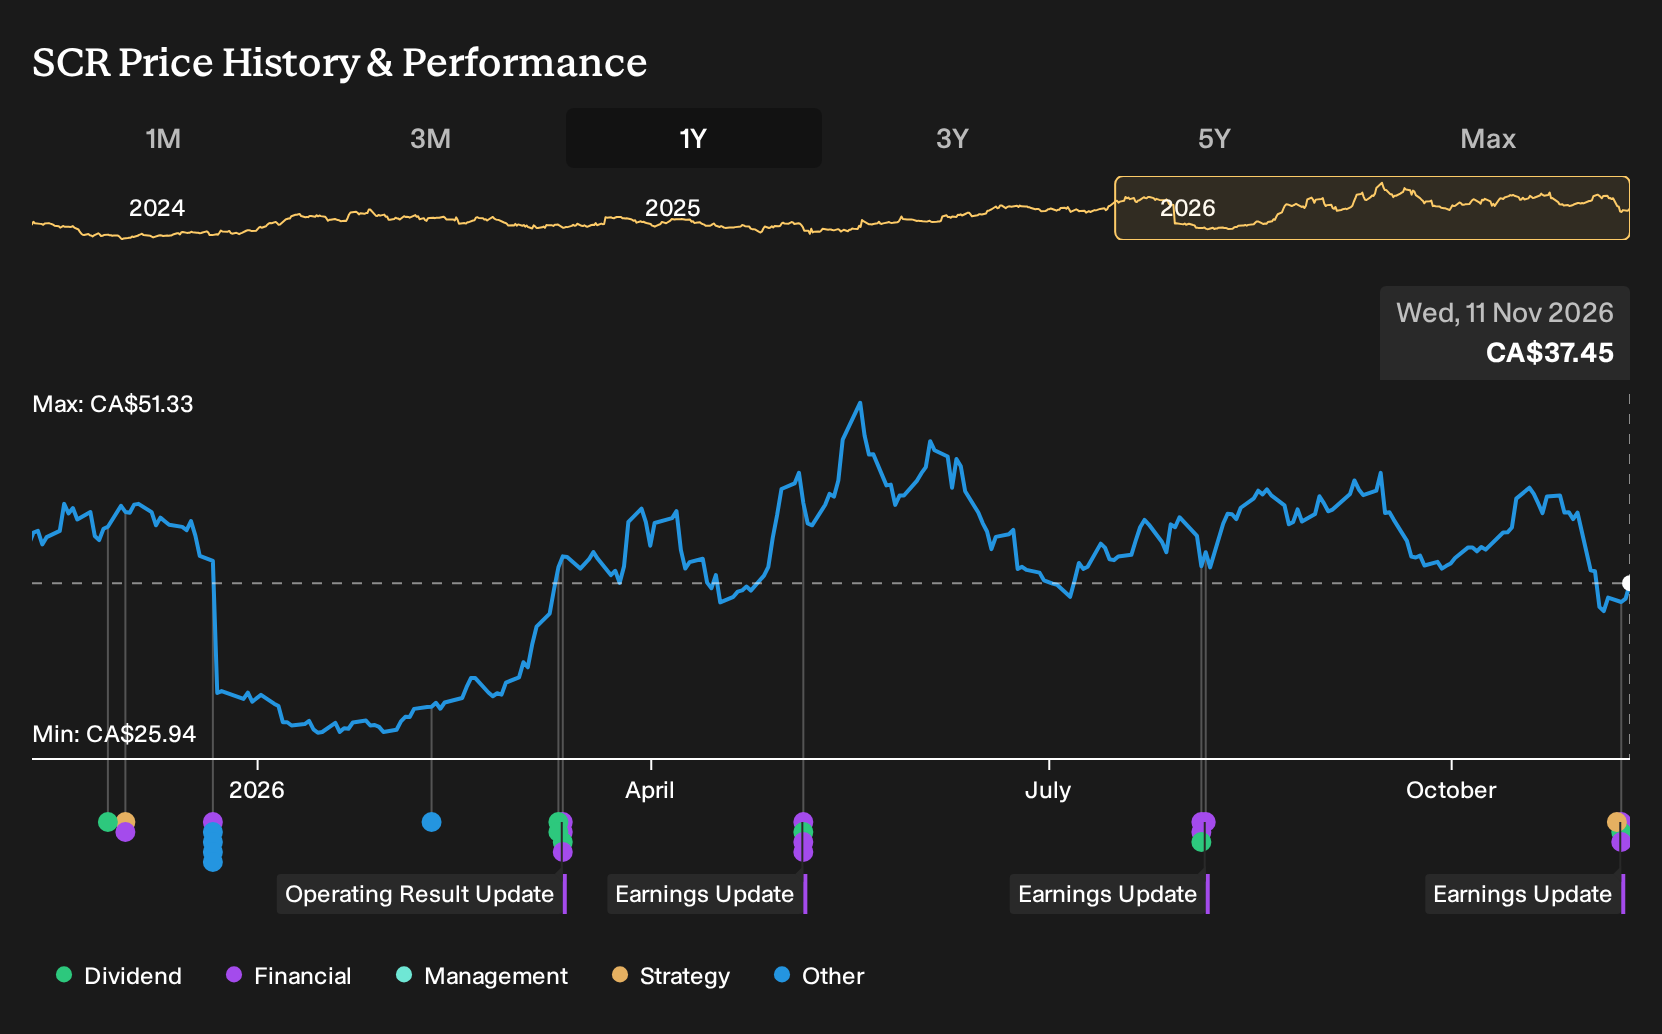
Exploring Other Perspectives
One alternative view focuses on revenue rather than production. The most cautious analysts were using forecasts that Strathcona Resources might reach about C$3.8b of revenue and C$1.1b of earnings by 2029, which already reflected a softer top line. You can interpret this dividend hike and Q3 result as a potential test of that more pessimistic outlook, so it is useful to compare several viewpoints before deciding what you think about the situation.
Explore 4 other Strathcona Resources fair value estimates, including one that suggests it could be worth just CA$40.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Strathcona Resources research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Strathcona Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Strathcona Resources' overall financial health at a glance.
Looking for more Strathcona Resources style income ideas?
If this update on Strathcona Resources has sharpened your thinking, the next step is to widen the opportunity set and pressure test your income and total return ideas against comparable stocks using the Simply Wall St Screener.
- For readers who want income with less balance sheet stress, filter for businesses that pair conservative leverage with consistent fundamentals through the list of solid balance sheet and fundamentals (5 results).
- If your focus is on dividend strength and payout resilience, scan a curated 3 dividend fortresses that share a similar income profile while offering different risk drivers to Strathcona Resources.
- For those hunting outside the obvious tickers, surface potential future leaders with healthier cash generation using the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com