


Norfolk Southern (NSC) is back in focus after a new agreement with Schneider National that ties Schneider's large intermodal fleet and logistics know-how to Norfolk Southern's eastern U.S. rail network and infrastructure projects.
Recent trading tells a mixed story. Norfolk Southern’s 1-month share price return of 3.52% and year-to-date share price gain of 14.86% signal positive momentum building again after a 7-day pullback of 3.94% and a softer 90-day stretch.
Over a longer horizon, total shareholder return of 17.35% over one year and 69.65% over three years indicates that investors who stayed in the stock have been rewarded as the railroad pursued intermodal expansion. The Schneider agreement has added another catalyst to that ongoing freight shift toward rail.
Capitalize on freight-to-rail momentum by scanning a curated group of rail and logistics players with resilient fundamentals using the list of solid balance sheet and fundamentals (23 results).Norfolk Southern shares have already moved on the Schneider news and recent intermodal traction. This leaves a practical question for investors: Does paying today’s price still stack up against waiting for a cheaper entry point when the valuation math is laid out?
Most Popular Narrative: 7% Undervalued
Norfolk Southern last closed at $330.59, while the analyst consensus Narrative on Simply Wall St anchors fair value at $356.11 using an 8.75% discount rate. That gap underpins the current upside story, but the Narrative hangs on some key execution points.
The main thing that has to go right is that Norfolk Southern converts its service and safety improvements into durable truck-to-rail share gains and better operating discipline, even as fuel costs and inflation put pressure on expenses.
The company's focus on increasing customer confidence through consistent service improvements is leading to meaningful market share gains, particularly in merchandise and intermodal segments, which could bolster future revenue growth.
See why 12 investors see Norfolk Southern as 7% undervalued.
Result: Fair Value of $356.11 (UNDERVALUED)
Still, the story around Norfolk Southern can change quickly if higher fuel expenses squeeze margins further or if the contested Union Pacific merger drags on longer than expected.
Find out about the key risks to this Norfolk Southern narrative.
Another View: Norfolk Southern Through A Cash Flow Lens
The analyst Narrative frames Norfolk Southern as undervalued, but the SWS DCF model tells a very different story. On that measure, the recent $330.59 share price sits above an estimated future cash flow value of $238.36, which points to an overvalued outcome instead.
That gap highlights a simple trade off for investors. Earnings based targets rely on improving margins and productivity, while the cash flow view reflects more caution about how much cash the railroad might ultimately generate. Which picture feels closer to how you see Norfolk Southern?
Look into how the SWS DCF model arrives at its fair value.
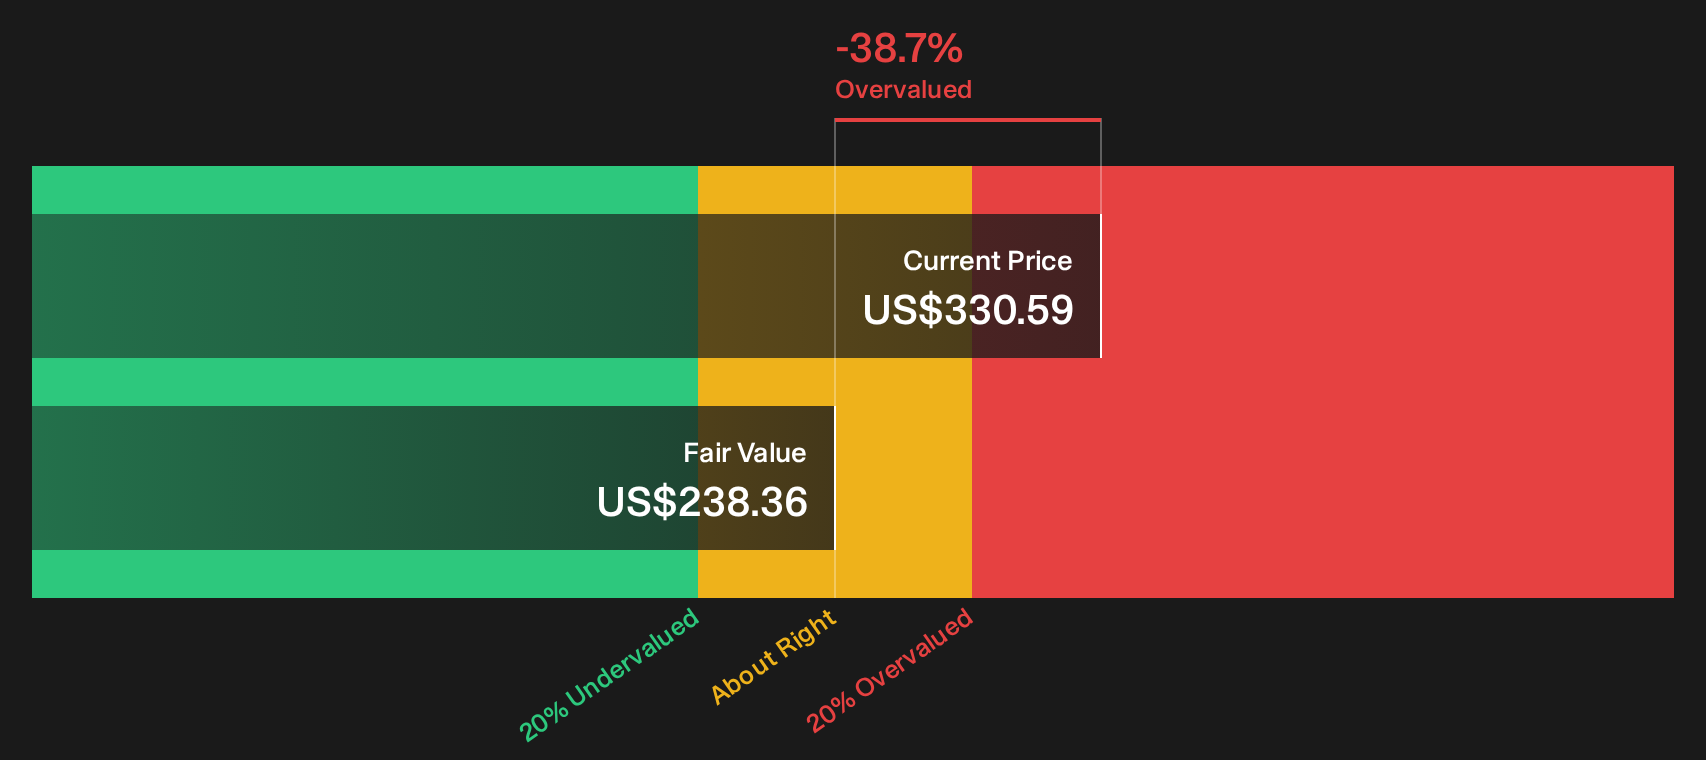
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norfolk Southern for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Norfolk Southern so far. Use the full dataset, compare the risks with the potential rewards, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Norfolk Southern investment ideas?
If Norfolk Southern has sharpened your interest in rail and infrastructure, broaden your watchlist now. Fresh ideas often show up where fewer investors are paying attention.
- Target value-focused opportunities by scanning a curated pool of companies trading at attractive valuations using the 32 high quality undervalued stocks.
- Strengthen your downside protection by concentrating on financially resilient businesses through the 30 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking a focused set of under-the-radar prospects with solid fundamentals using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com