


Chubb (CB) has drawn fresh attention after appointing Lucas Scortecci as head of Financial Lines for Continental Europe, the Middle East and North Africa, with responsibility for underwriting across these regions.
For context, Chubb’s share price has climbed 7.3% over the past month and 19.4% year to date, while its 1-year total shareholder return of 27.1% and 5-year total shareholder return of 107.7% point to momentum that has been building rather than fading around executive moves such as the Scortecci appointment.
See how Chubb’s executive reshuffle compares with peers by reviewing a hand picked list of insurers in the 30 resilient stocks with low risk scores that have kept risk in tight focus.
Chubb looks like a high quality insurer with broad reach and fresh leadership in key regions after the Scortecci move. The open question is whether that strength is already fully reflected in a US$370 share price.
Most Popular Narrative: 1% Overvalued
Chubb’s last close at $370.33 sits slightly above the analyst consensus Narrative fair value of $365.91. This implies a small premium that the analyst consensus Narrative on Simply Wall St connects to its earnings power and capital return profile, using a 7.06% discount rate.
Capital management that includes a new US$7.5b open ended share repurchase authorization, ongoing quarterly buybacks of about US$1.0 to 1.1b and a 33 year record of dividend increases sets up continued deployment of excess capital that can affect earnings per share and total shareholder yield.
See why 89 investors see Chubb as 1% overvalued.
Result: Fair Value of $365.91 (OVERVALUED)
Still, the narrative around Chubb can unravel if casualty loss costs keep running ahead of pricing or if shedding underpriced property significantly reduces premium volume.
Find out about the key risks to this Chubb narrative.
Another View: Chubb Through A Cash Flow Lens
Chubb looks slightly expensive next to the analyst Narrative fair value of $365.91, yet the SWS DCF model paints a very different picture. On that framework, the shares trade about 44.5% below an estimated future cash flow value of $666.81, which points to a much wider valuation gap. Which story do you think comes closer to reality for a capital intensive insurer with long dated liabilities?
Look into how the SWS DCF model arrives at its fair value.
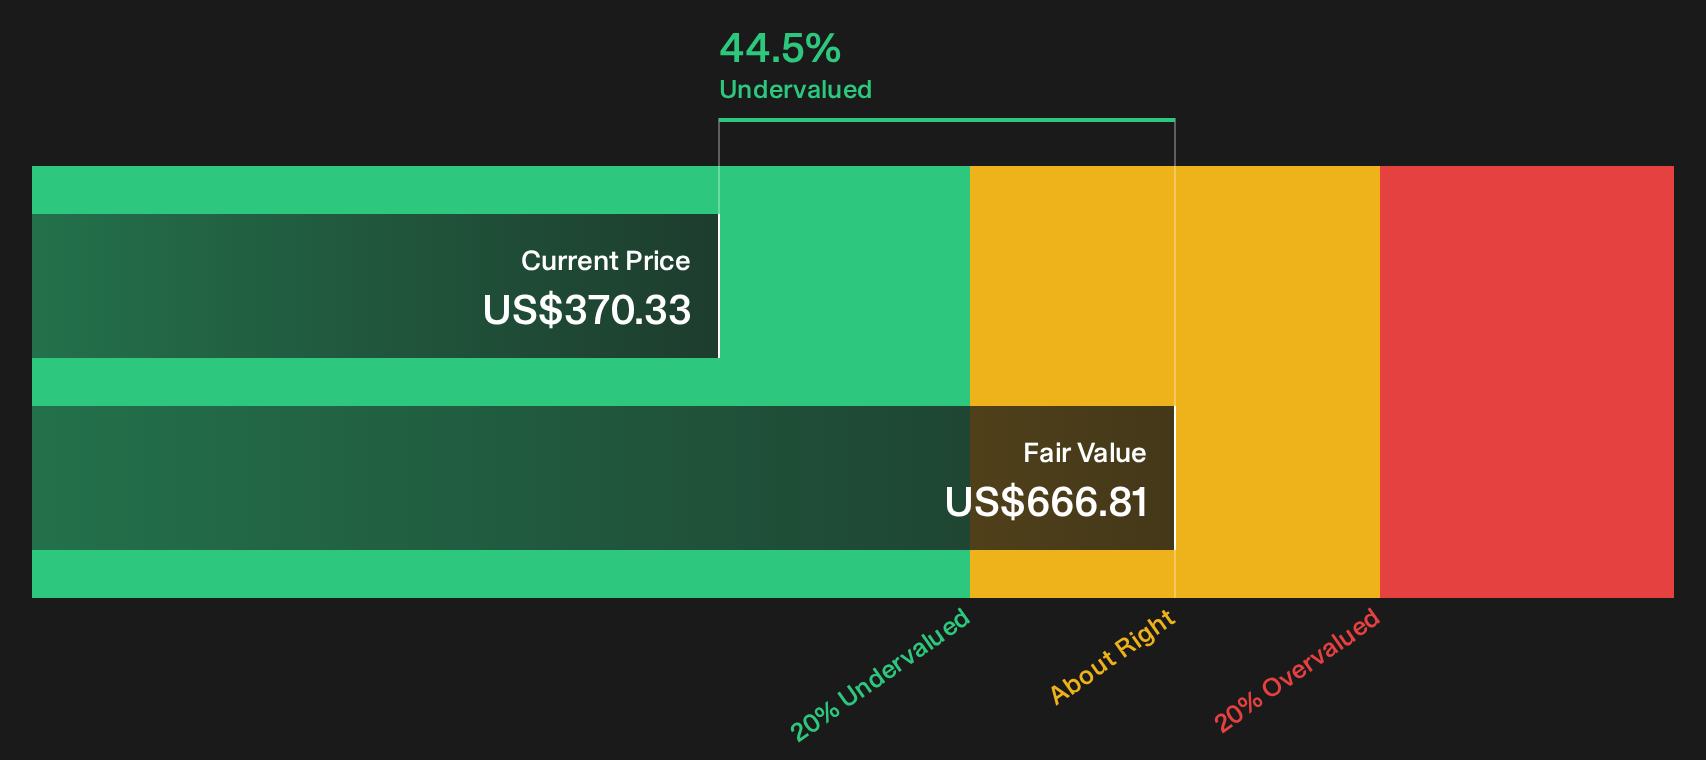
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chubb for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Chubb’s valuation and risk reward profile can trigger debate, so review the underlying numbers, weigh both sides, and then check the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Chubb?
If Chubb has sharpened your focus on quality, broaden your watchlist with other targeted ideas that can round out your portfolio and help you uncover fresh opportunities.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) to identify candidates that can help anchor a portfolio when conditions get noisy.
- Explore quality at a discount by running through the 32 high quality undervalued stocks and see which businesses combine fundamentals with pricing that has not fully caught up.
- Review income-focused candidates in the 6 dividend fortresses to help you build a more reliable cash return stream alongside capital appreciation potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com