


Interparfums (IPAR) just packed three key updates into one day: reporting third quarter earnings, nudging full year 2026 sales guidance higher, and affirming a regular quarterly dividend of $0.80 per share.
Interparfums shares have eased in the very short term, with a 1-day share price return of 1.75% lower and a 7-day share price return of 1.54% lower. However, the 30-day and 90-day share price returns of 16.77% and 16.19%, together with a 55.89% year-to-date share price gain and 57.42% 1-year total shareholder return, point to momentum that has been building ahead of and around the latest earnings, guidance tweak, and dividend affirmation.
Scan how Interparfums stacks up against other fragrance and consumer stocks showing strong balance sheets and fundamentals by checking our hand picked list of solid balance sheet and fundamentals (23 results) today.
After a sharp year-to-date run and only modest tweaks to sales guidance and earnings, Interparfums now faces a harder question: Does the current price still leave enough upside to justify fresh risk, or not?
Most Popular Narrative: 5.1% Overvalued
Interparfums last closed at $133.19, above the analyst consensus Narrative fair value of $126.67. The story hinges on whether investors agree with the earnings and cash flow path baked into that estimate from the analyst consensus Narrative on Simply Wall St, which uses a 7.55% discount rate to weigh those future numbers.
The decision to make 2026 an off cycle year focused on line extensions, while preparing a concentrated wave of new blockbuster pillars for brands already above US$100m of sales in 2027 and further launches in 2028, supported by higher advertising and promotion spending that reached 18.8% of sales in the first half of 2026 and is guided toward about 21% for the full year, sets up a product cycle that can support higher revenue, operating margin and earnings power.
See why 9 investors see Interparfums as 5% overvalued.
Result: Fair Value of $126.67 (OVERVALUED)
Still, the Interparfums narrative could be knocked off course if licensed partners walk away from key agreements, or if war related disruption continues to weigh on Middle East and Africa sales.
Find out about the key risks to this Interparfums narrative.
Another View: Interparfums Through The Earnings Multiple Lens
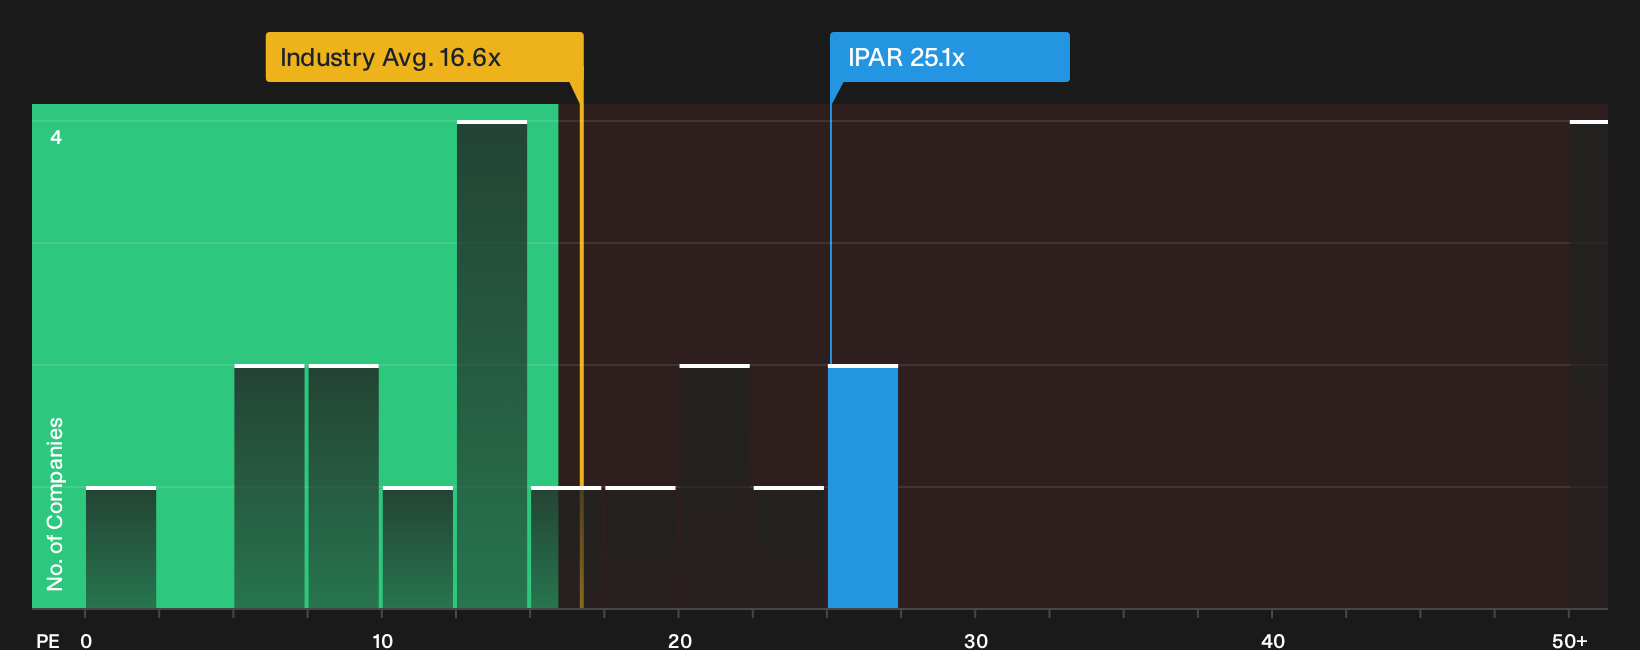
Interparfums may appear 5.1% overvalued compared with the analyst narrative fair value, yet the earnings multiple suggests a different perspective. The stock trades on a 25.1x P/E. That is below peers at 50.8x, but above the global Personal Products average of 16.8x and its own fair ratio of 16.1x.
This combination of cheaper pricing than direct peers, richer pricing than the wider industry, and a premium to the fair ratio leaves investors considering whether they see more valuation risk or potential opportunity ahead.
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Pockets of optimism and concern now surround Interparfums, so move quickly, review the underlying data, and decide where you stand on its risk reward trade off with 3 key rewards and 1 important warning sign.
Ready for more investment ideas beyond Interparfums?
If Interparfums has sharpened your focus, use that energy now. Fresh ideas often appear when you compare similar quality, income, and resilience across other opportunities.
- Target potential mispricing by scanning a curated pool of quality stocks that combine strong fundamentals with appealing valuations through the 32 high quality undervalued stocks.
- Reinforce your income stream by reviewing companies that pair higher yields with balance sheet strength via the 6 dividend fortresses.
- Dial down portfolio stress by concentrating on companies with robust finances and low risk profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com