


European banks and insurers tied to government bond markets sit in a tricky spot right now. Confidence across industry and services has picked up, yet inflation at 4.0% and energy costs rising 20% keep pressure on funding and balance sheets, especially where sovereign debt loads are heavy. This article highlights three stocks from that exposure theme and shows where current conditions may help or hurt investors searching for opportunity.
The stocks covered next are just a sample from this theme. The full screen surfaced 22 more eurozone banks and insurers with equally compelling sovereign risk stories that are not detailed here. To identify and analyze the highest conviction ideas from this group, go straight to the Eurozone Banks and Insurers Exposed to Sovereign Credit Risk screener.
Crédit Agricole (ENXTPA:ACA)
Overview: Crédit Agricole is a large French banking group whose retail, corporate and insurance activities are tightly linked to eurozone government debt markets.
Operations: Crédit Agricole reports €23.8 billion from segment adjustments and €3.8 billion from French Retail Banking LCL, while the Corporate Centre shows a €242 million reduction.
Market Cap: €47.5 billion
Crédit Agricole sits near the front of this sovereign risk theme because its French and Italian lending ties directly into government bond markets. The bearish analyst Narrative on Simply Wall St focuses on how certain business lines could influence that exposure.
"Crédit Agricole continues to carry sizeable exposure to mobility and auto finance through Leasys, Drivalia and GAC Sofinco, and further residual value and used car remarketing adjustments similar to those already applied in 2025 and early 2026 could keep these activities breakeven or loss making, weighing on associate income and dragging on group net profits."
What really matters now is how one less visible pressure on Crédit Agricole feeds through to margins just as funding conditions stay sensitive.
That funding squeeze is only part of the story, and the full narrative for Crédit Agricole shows how Crédit Agricole's broad eurozone footprint could turn today’s pressure into tomorrow’s potential upside.

UniCredit (BIT:UCG)
Overview: UniCredit is a pan European commercial bank headquartered in Milan that lends to households, companies and public sector clients across Italy, Germany and Central and Eastern Europe, tying its fortunes closely to local government bond markets and sovereign funding conditions.
Operations: UniCredit generates about €11.0b of revenue in Italy, €5.3b in Germany, €4.8b across Central and Eastern Europe excluding Austria, and €2.6b in Austria.
Market Cap: €126.2b
UniCredit sits near the front of this sovereign risk screen because its Italian and Central European banking franchises channel savings and credit directly into local government bond markets. The analyst consensus Narrative on Simply Wall St argues that the way those balance sheet ties mix with fee led banking really matters right now.
"Expansion of capital light fee and insurance activities, with fee and insurance income contributing roughly 31 to 48% of net revenues across major regions and growing at 8 to 14% year on year in early 2026, continues to shift UniCredit’s mix toward more recurring, higher margin revenue streams that can support earnings quality."
What investors will likely watch most closely is how one unresolved pressure on UniCredit’s sovereign linked loan book interacts with that richer fee mix.
That pressure point is the starting line, and the full narrative for UniCredit shows how UniCredit’s sovereign exposure, fee engine and capital actions could be quietly decoupling.

Société Générale Société anonyme (ENXTPA:GLE)
Overview: Société Générale Société anonyme is a large French bank that earns most of its income in Europe, closely tied to eurozone government debt markets.
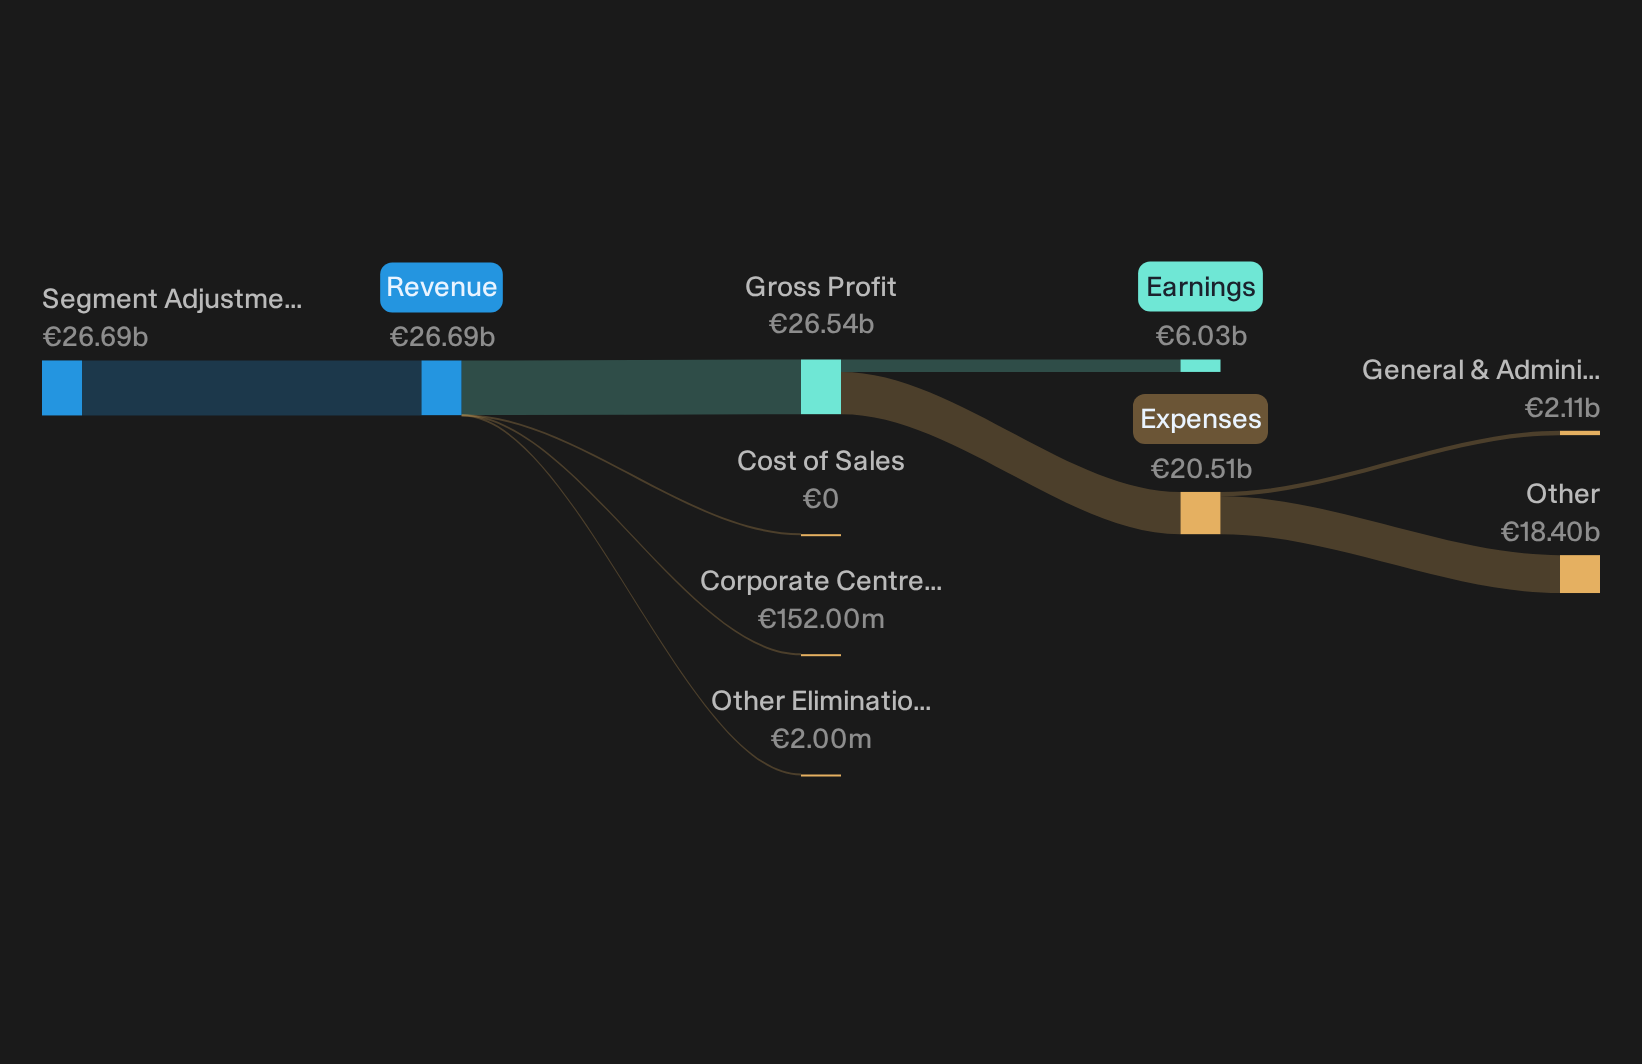
Operations: Société Générale Société anonyme reports about €26.7b of segment adjustment income, partly offset by a €152m decline in Corporate Centres.
Market Cap: €48.5b
Société Générale Société anonyme matters for this sovereign risk theme because its lending, trading and insurance activities all interact directly with eurozone government bond markets. In addition, the analyst consensus Narrative on Simply Wall St sets clear conditions for how that exposure could translate into returns.
"The main thing that has to go right is that Société Générale Société anonyme delivers the planned further cost base reduction, IT and AI savings, and French retail transformation so that group cost to income moves below 55% while maintaining a CET1 ratio above 13% and a cost of risk near 25 to 30bp."
What really moves the needle for Société Générale Société anonyme is how one unseen funding pressure interacts with those cost and capital targets.
If that hidden funding strain is what worries you, the full narrative for Société Générale Société anonyme explains how Société Générale Société anonyme could still turn tighter costs into accelerating earnings power.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, early momentum and under the radar stories rarely stay quiet for long before prices get caught flying or dropping, so consider acting promptly.
- Spot potential turnarounds early and scan through the 565 high quality undiscovered gems curated to highlight under-followed businesses before the crowd pays attention.
- Review the 212 dividend fortresses to explore companies with dividend policies and balance sheets that aim to support ongoing payouts.
- Track where current earnings power intersects with AI-related activity and work through the 42 profitable AI stocks that aren't just burning cash while valuations still reflect businesses investing from actual cash profits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com